
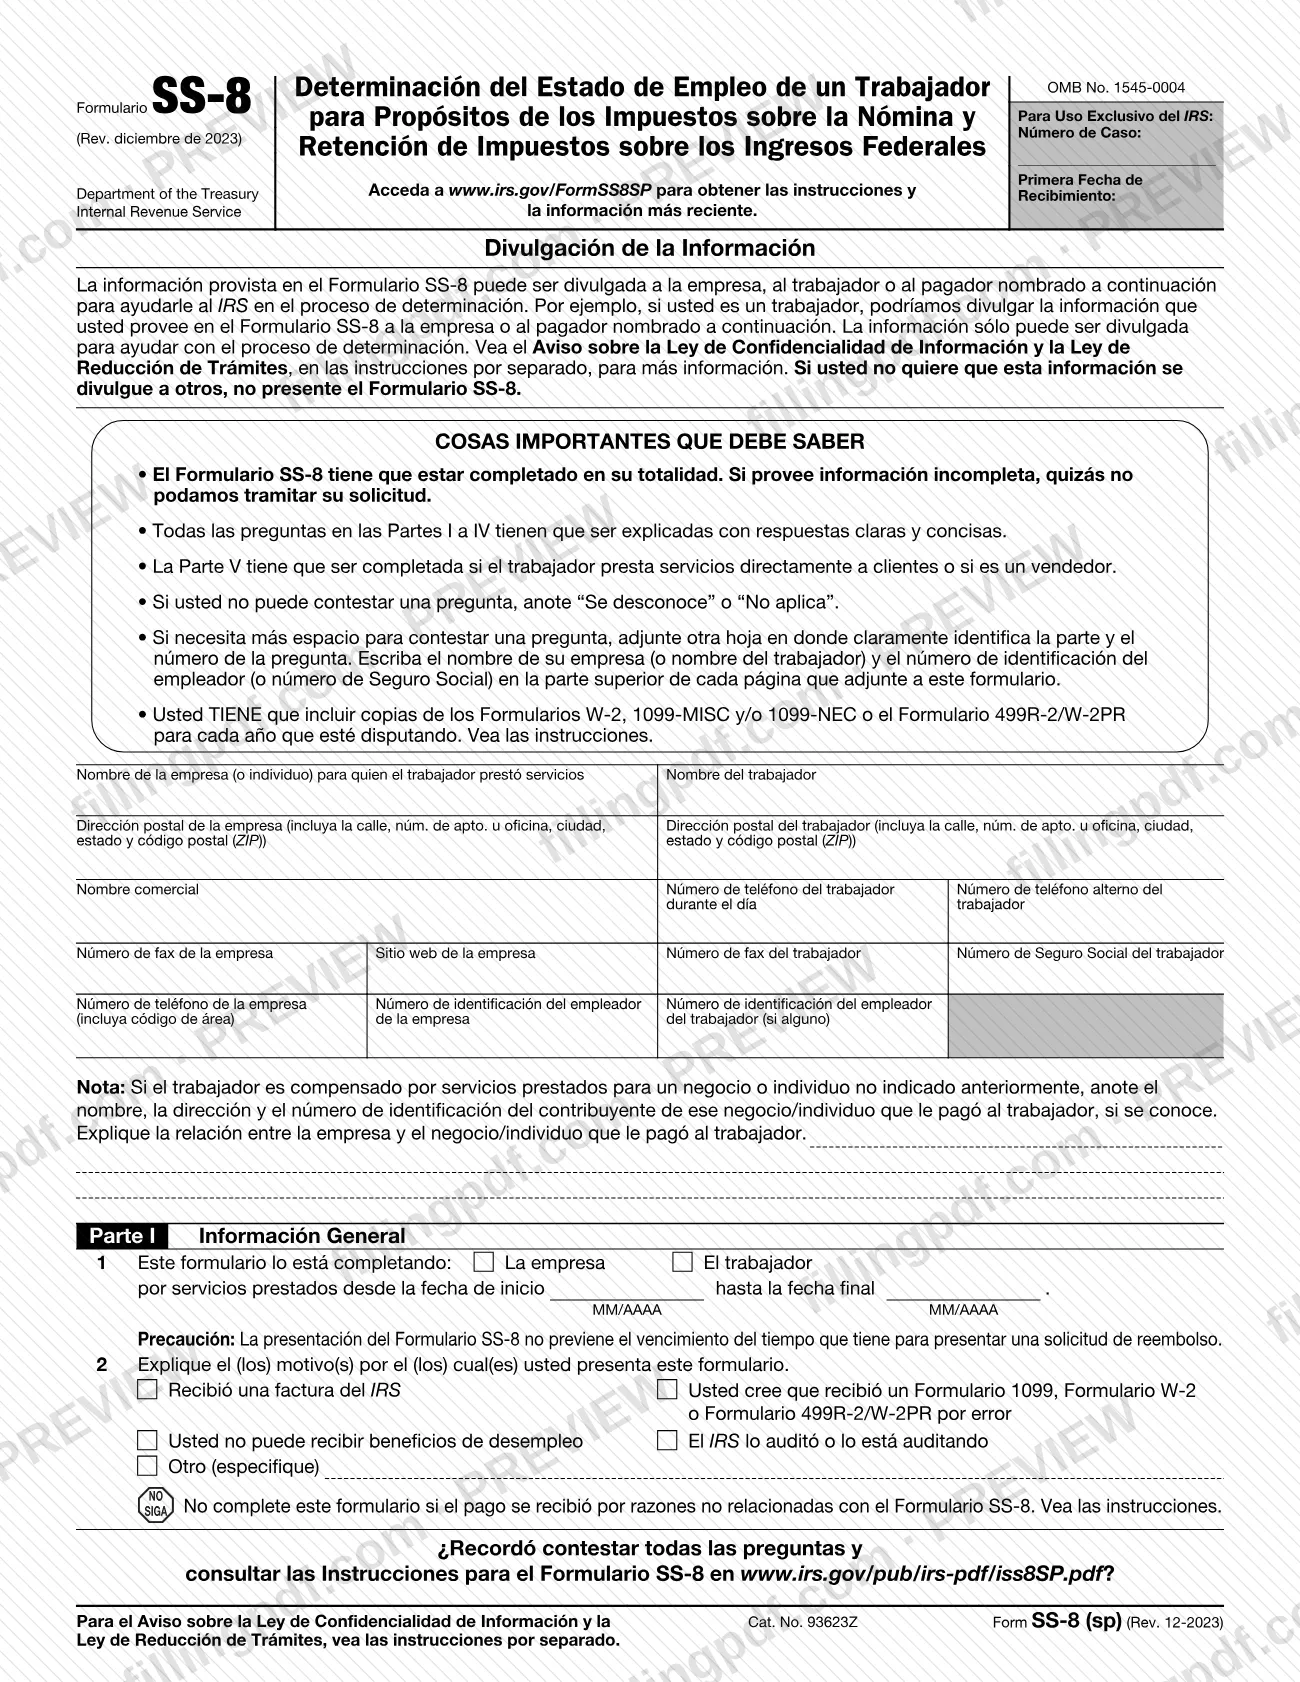
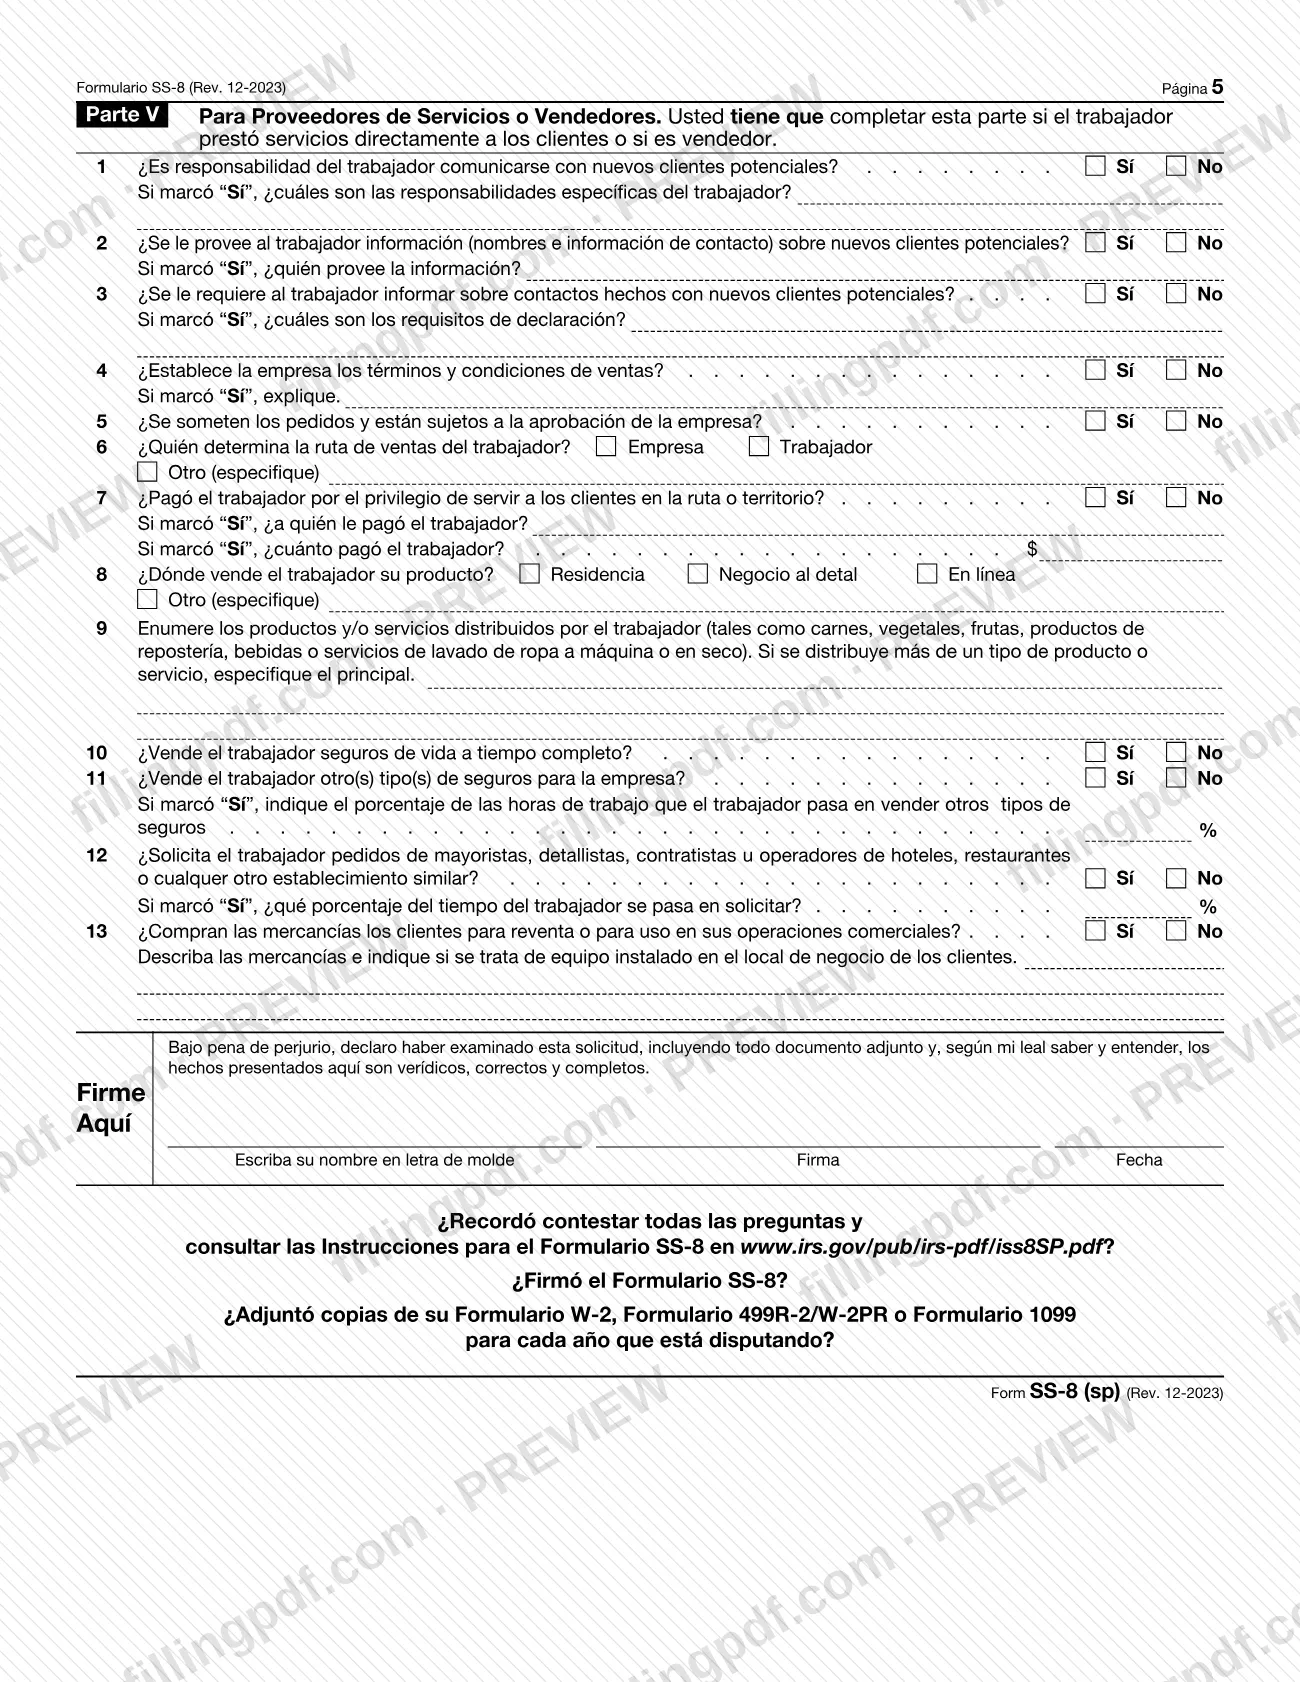
Form SS-8 (sp) is the Spanish-language version of the Internal Revenue Service (IRS) form that a firm or a worker files to ask whether the worker is an employee or an independent contractor for federal employment taxes and income tax withholding. It is the Spanish edition of Form SS-8, printed Rev. 12-2023. On FillingPDF you can fill out the form online and download or print the completed PDF; the IRS publishes the original PDF and the Spanish instructions, and the request itself goes to the IRS by mail or fax.
Last updated
What is SS-8 (sp)?
Form SS-8 (sp) is the Spanish version of the IRS form that firms and workers file to ask whether a worker is an employee under common-law rules for federal employment taxes and income tax withholding.
Its full title is Determination of Worker Status for Purposes of Federal Employment Taxes and Income Tax Withholding (Spanish Version), printed in Spanish as Formulario SS-8, Determinación del Estado de Empleo de un Trabajador. It carries OMB No. 1545-0004. The IRS says that, under common-law rules, a worker is generally an employee if the firm has the right to control and direct what work is done and how it is done. The IRS agency page describes the request as asking the IRS to establish whether the services a person provides to a firm are those of an employee or an independent contractor.
The form has five parts: Parte I (general information), Parte II (behavioral control), Parte III (financial control), Parte IV (relationship of the parties) and Parte V (for service providers or salespersons). The IRS assigns the case to a technical specialist, who reviews the facts, applies the law and reaches a decision. The IRS usually issues a formal determination letter to the firm or payer, with a copy to the worker; in some cases it issues an informational letter instead.
The form is not a refund claim, it is not an audit of a tax return, and the SS-8 unit does not handle supplemental wage issues.
Who needs to file SS-8 (sp)?
Firms and workers use Form SS-8 (sp) to get a determination of a worker's status for federal employment tax and income tax withholding purposes.
- A firm may request a determination for a specific worker, or for a class of workers by completing the form for one worker in that class and attaching a list with the names, addresses and Social Security numbers (if available) of everyone potentially affected. A separate form is needed for each class.
- A worker may request one. If the worker asks for a determination for more than one firm, a separate form is needed for each firm.
- A firm that receives an IRS request to complete a blank Form SS-8 because a worker asked for a determination. Not responding does not stop the IRS from issuing an informational letter to the worker.
Do not use the form if you do not want the information disclosed: the IRS may share what you provide with the other parties named on page 1. The IRS does not issue determination letters on proposed transactions, hypothetical situations, current worker classification litigation, certain local government workers who may be covered by a Section 218 agreement (only the Social Security Administration decides that), business-to-business transactions, or other reasons that do not serve federal tax administration.
You may represent yourself or authorize an attorney, CPA or enrolled agent with Form 2848 or 8821. A representative cannot sign the SS-8 in your place.
When to file SS-8 (sp)
File Form SS-8 (sp) when you need the IRS to decide a worker's status, or when the IRS asks you, as the firm, to complete one after a worker requested a determination. The form has no due date of its own, but timing still matters. The IRS makes a determination only for years whose statute of limitations has not expired; if you file for a year where it has expired, no determination letter is issued. Filing the form does not stop the clock on a refund claim. As a general rule, a claim for credit or refund must be filed within 3 years of filing the original return or 2 years of paying the tax, whichever is later. The instructions explain how to protect that period with a Form 1040-X marked "Protective Claim", one for each year in question. Filing Form SS-8 does not excuse you from filing tax returns or paying taxes on time, or from answering a payment request, while you wait for a determination.
Documents you need
- Copies of Forms W-2, 1099-MISC, 1099-NEC or Form 499R-2/W-2PR for each year you are disputing; the form says you must include them.
- If you cannot provide those forms: a detailed letter of what was earned each year, with copies of checks, pay stubs, bank statements and similar records.
- Copies of supporting documents listed on Part I, line 5, such as contracts, invoices, notes, forms issued or received, IRS closing agreements or IRS decisions.
- Any advertisement used to obtain the work, if the worker was hired that way (Part I, line 4).
- A copy of the written agreement between the firm and the worker, preferably signed by both, if the work is done under one (Part I, line 11a).
- Examples of reports, if the worker must complete reports (Part II, line 5).
- A copy or explanation of the lease terms, if the worker leases equipment, space or a facility (Part III, line 2).
- Copies of the worker's advertising, if available and the worker advertises (Part IV, line 6).
- Documentation of any non-compete agreement, if one exists (Part IV, line 4).
- Extra sheets for any answer needing more space, each identifying the part and question and headed with the firm's or worker's name and EIN or SSN.
- For a class of workers: a list with the names, addresses and SSNs (if available) of all potentially affected workers.
- If you believe litigation is not about worker classification or is resolved: documentation such as the complaint, first pleading or court record.
How to fill out SS-8 (sp)
Identify the firm and the worker
At the top of page 1, enter the firm's name, address, phone, fax, website and EIN, and the worker's name, address, phones, Social Security number and EIN (if any). If someone other than the firm paid the worker, give that payer's name, address and taxpayer ID and explain how it relates to the firm.
Complete Part I, lines 1 and 2
Line 1: mark whether the firm or the worker is completing the form and enter the service period in MM/AAAA format. Line 2: check the reason or reasons you are filing, such as an IRS bill, a Form 1099 or W-2 received in error, or an audit, or describe another reason.
Answer Part I, lines 3 to 7
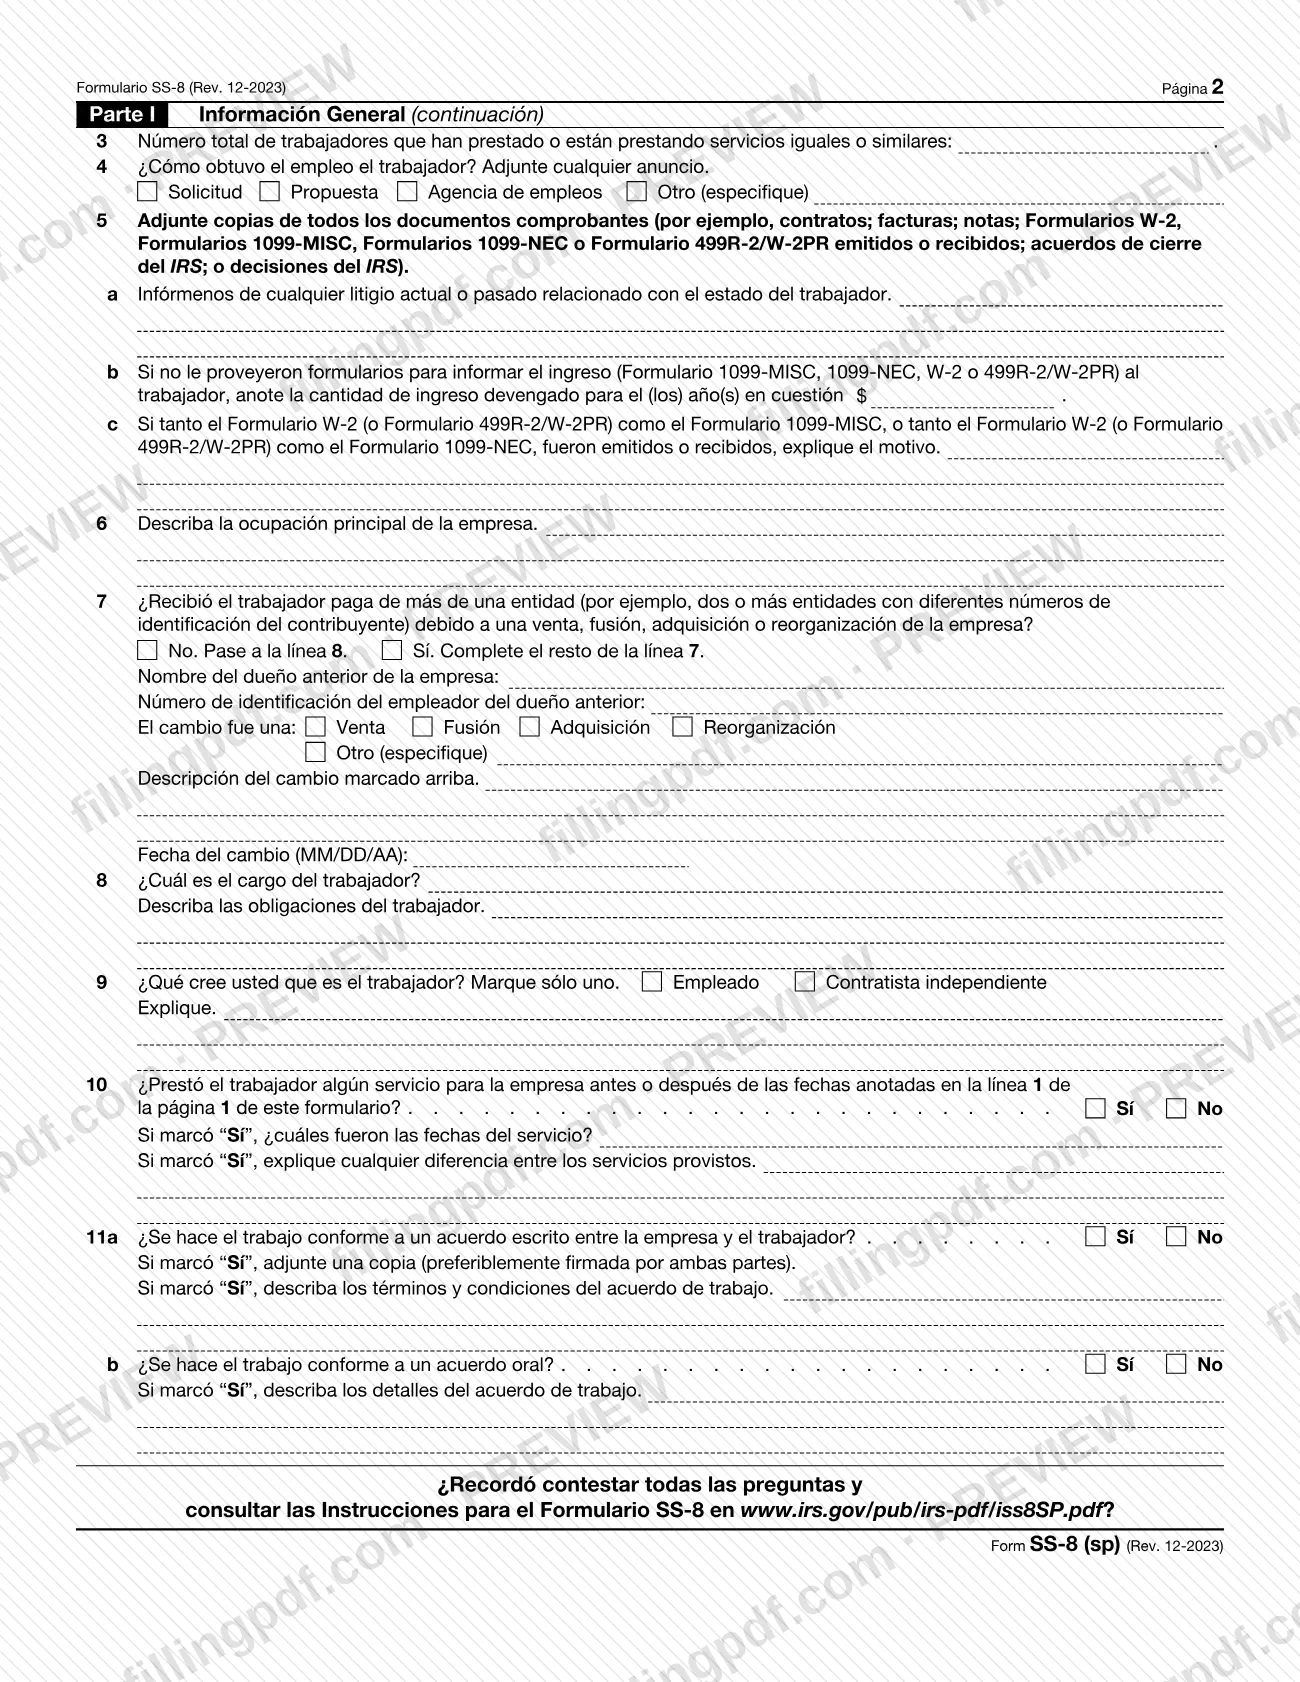
Enter the number of workers doing similar services (line 3), how the worker got the job and attach any ad (line 4), and attach supporting documents (line 5, with 5a to 5c on litigation, income and duplicate forms). Describe the firm's main occupation (line 6) and, on line 7, any sale, merger or reorganization, with the change date as MM/DD/AA.
Answer Part I, lines 8 to 11
Give the worker's title and duties (line 8) and check Empleado or Contratista independiente with an explanation (line 9). Answer line 10 on services outside the dates in line 1, and lines 11a and 11b on written or oral agreements, attaching a copy of any written one.
Complete Part II, behavioral control
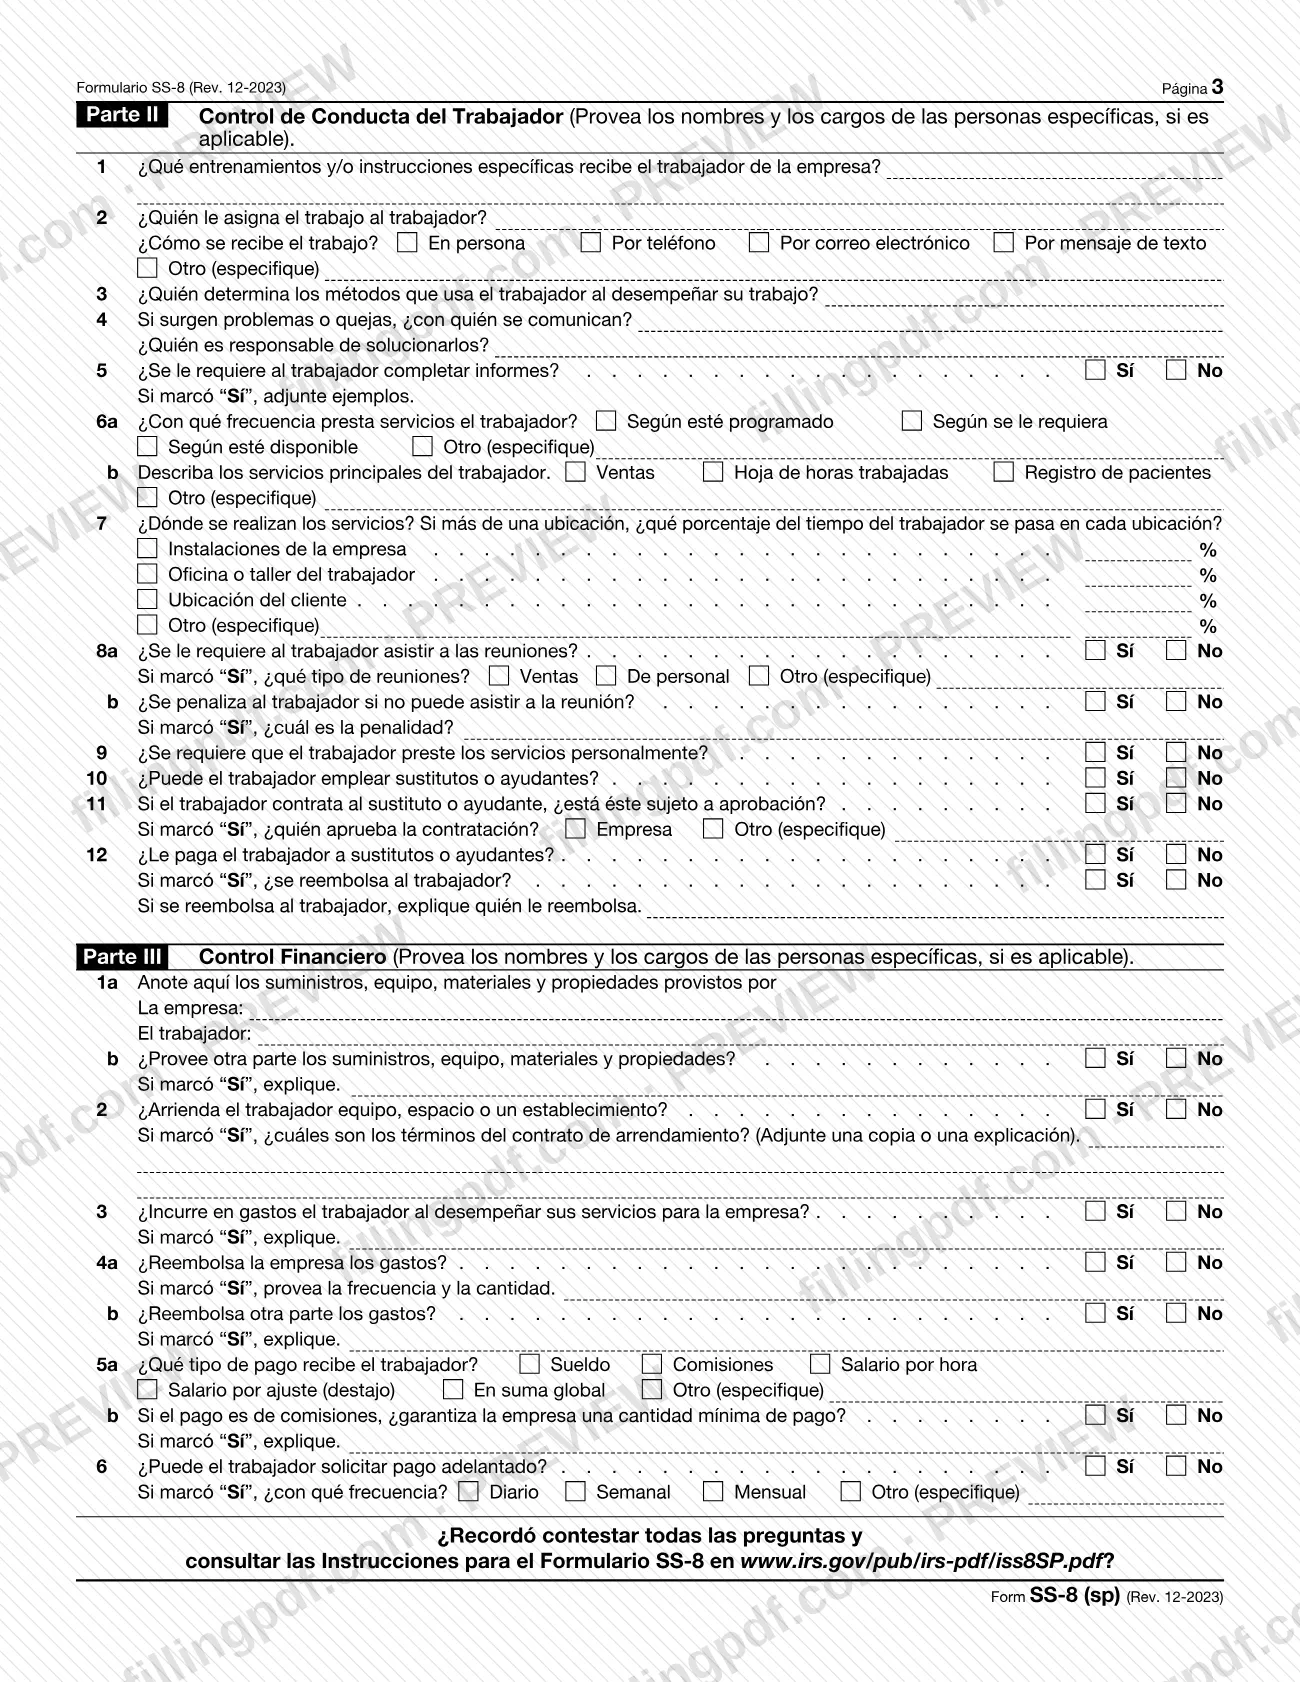
Describe training and instructions, who assigns work and how, who decides the methods, and who handles problems (lines 1 to 4). Then answer lines 5 to 12 on reports, schedule, location percentages, meetings, and personal service, substitutes and helpers. Give names and titles of specific people where applicable.
Complete Part III, financial control
List supplies and equipment provided by the firm and by the worker (line 1), then answer lines 2 to 10 on leases, expenses, reimbursements, type of pay, advances, who the customer pays, workers' compensation insurance, financial risk or loss, and who sets pay and prices.
Complete Part IV, relationship of the parties
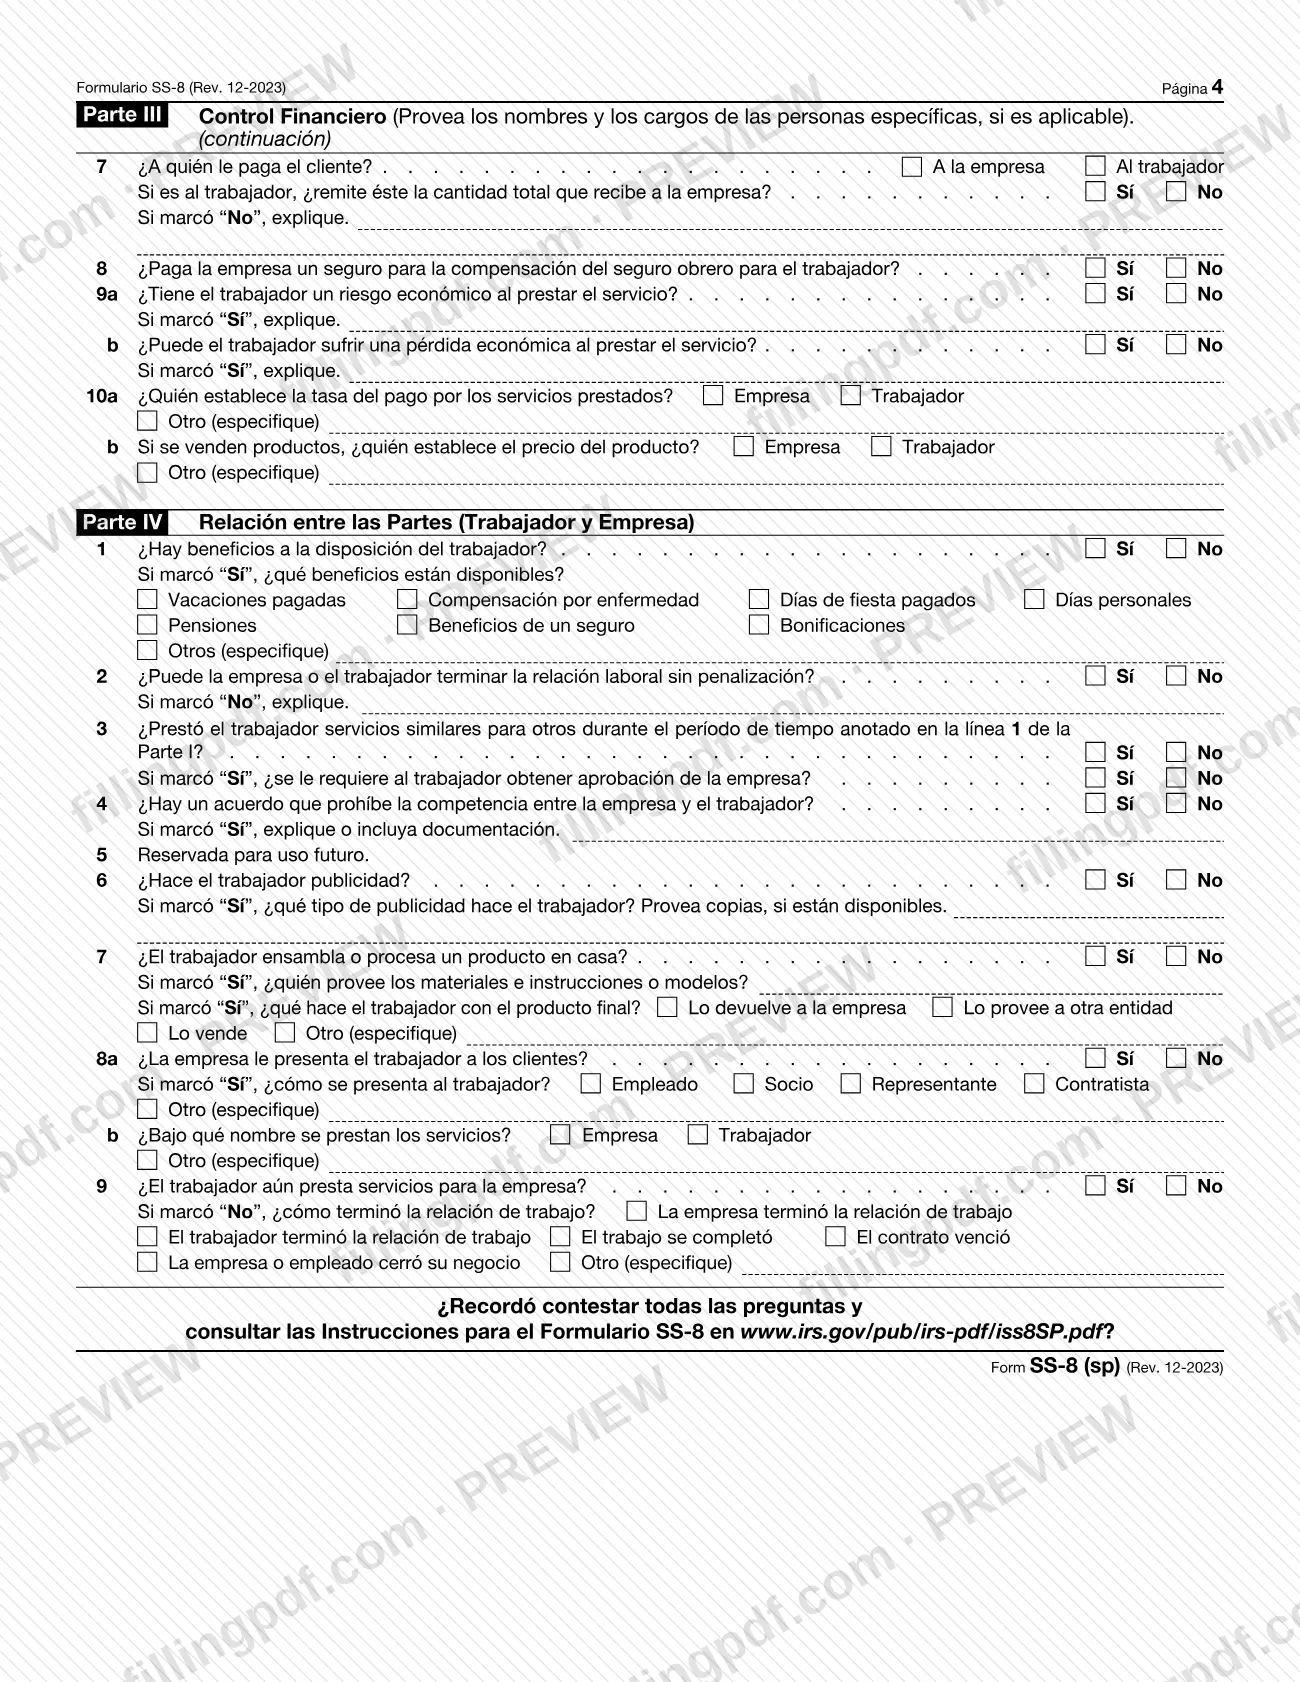
Answer lines 1 to 9 on benefits, ending the relationship without penalty, work for others, non-compete agreements, advertising, home assembly, how the worker is introduced to customers, and whether and how the relationship ended. Line 5 is reserved for future use. Note any significant change in the relationship.
Complete Part V if it applies
Complete Part V, lines 1 to 13, if the worker serves customers directly or is a salesperson. Cover prospecting, sales terms, order approval, route, territory payments, where the product is sold, the products or services distributed and insurance sales.
Attach documents and extra sheets
Attach copies of W-2, 1099-MISC, 1099-NEC or 499R-2/W-2PR forms for each year in question, plus the agreements and other items the lines request. Put the part and question number and the firm's or worker's name and EIN or SSN on each added sheet.
Sign, date and download the PDF
Print your name, then sign and date under the penalties-of-perjury statement; a stamped signature or a power-of-attorney signature is not accepted. Use the checklist at the end of the form, then download or print the completed PDF from FillingPDF and send it as described under How to submit.
How to submit SS-8 (sp)
You can send the completed and signed Form SS-8 (sp), with its attachments, to the IRS by mail or by fax.
- By mail: Internal Revenue Service, Form SS-8 Determinations, P.O. Box 630, Stop 631, Holtsville, NY 11742-0630.
- By fax: 855-242-4481.
Do not send Form SS-8 with your tax return; the IRS says this causes a delay in processing. The IRS acknowledges receipt of the form and often asks the other parties named on it to complete blank forms. An incomplete form is returned to the sender, as is a form that is not properly signed and dated. The instructions say there is no charge to request a determination letter. An original request should generally carry a handwritten signature or an electronic one, such as a faxed document or a digitally signed PDF. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Leaving questions unanswered in Parts I to IV; the IRS cannot make a determination unless all are completed, and an incomplete form is returned.
- Skipping Part V when the worker serves customers directly or is a salesperson; the form requires it in those cases.
- Omitting copies of Forms W-2, 1099-MISC, 1099-NEC or 499R-2/W-2PR for each year in dispute.
- Leaving a question blank when you do not know the answer instead of writing "Se desconoce" (unknown) or "No aplica" (not applicable).
- Adding extra pages without the part and question number, or without the firm's or worker's name and EIN or SSN at the top of each page.
- Having a stamped signature or a power-of-attorney representative sign instead of the taxpayer, or leaving the form unsigned or undated.
- Mailing the form with a tax return instead of to the SS-8 Determinations address in Holtsville.
- Assuming Form SS-8 protects a refund claim; it does not stop the refund claim period from expiring.
- Requesting a determination for several firms or classes on one form instead of a separate form for each firm or class.
Frequently asked questions
What is Form SS-8 (sp) used for?
Form SS-8 (sp) is the Spanish version of the IRS request for a determination of whether a worker is an employee or an independent contractor for federal employment taxes and income tax withholding. A firm or a worker can file it, and the IRS decides based on the facts.
Who can file Form SS-8 (sp)?
Either a firm or a worker. A firm can ask about one worker or a class of workers, and a worker who wants a determination for more than one firm files a separate form for each. A firm may also be asked by the IRS to complete one after a worker's request.
Is there a fee to file Form SS-8 (sp)?
No. The IRS instructions say you do not have to pay to request a determination letter on Form SS-8. Nothing in them sets a fee for the request.
Where do I mail or fax Form SS-8 (sp)?
Mail it to Internal Revenue Service, Form SS-8 Determinations, P.O. Box 630, Stop 631, Holtsville, NY 11742-0630, or fax it to 855-242-4481. Do not send it with your tax return, because that delays processing.
What do I attach to Form SS-8 (sp)?
Attach copies of Forms W-2, 1099-MISC, 1099-NEC or 499R-2/W-2PR for each year in dispute, plus the contracts, invoices and other supporting documents requested on Part I, line 5. Other lines ask for items such as a written agreement, sample reports or a lease.
Does filing Form SS-8 (sp) extend the deadline to claim a refund?
No. Filing the form does not stop the refund claim period from expiring. The instructions describe a protective claim on Form 1040-X, marked "Protective Claim" and filed for each year in question, to protect that period; you must still file returns and pay taxes on time.
Can someone sign Form SS-8 (sp) for me?
A representative holding a power of attorney cannot sign it, and a stamped signature is not accepted. For a corporation the signer must be an officer with personal knowledge of the facts; for a trust, partnership or LLC, a fiduciary, general partner or member-manager signs.
Is Form SS-8 (sp) the same as Form SS-8?
It is the Spanish-language edition of Form SS-8, printed Rev. 12-2023, with the same five parts. The IRS publishes matching Spanish instructions, Instrucciones para el Formulario SS-8, at the address printed on the form.
Can I fill out Form SS-8 (sp) online on FillingPDF?
Yes. You can fill out the fillable PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not send the form to the IRS; you mail or fax it yourself.
Ready to fill out SS-8 (sp)?
Fill out SS-8 (sp) now