
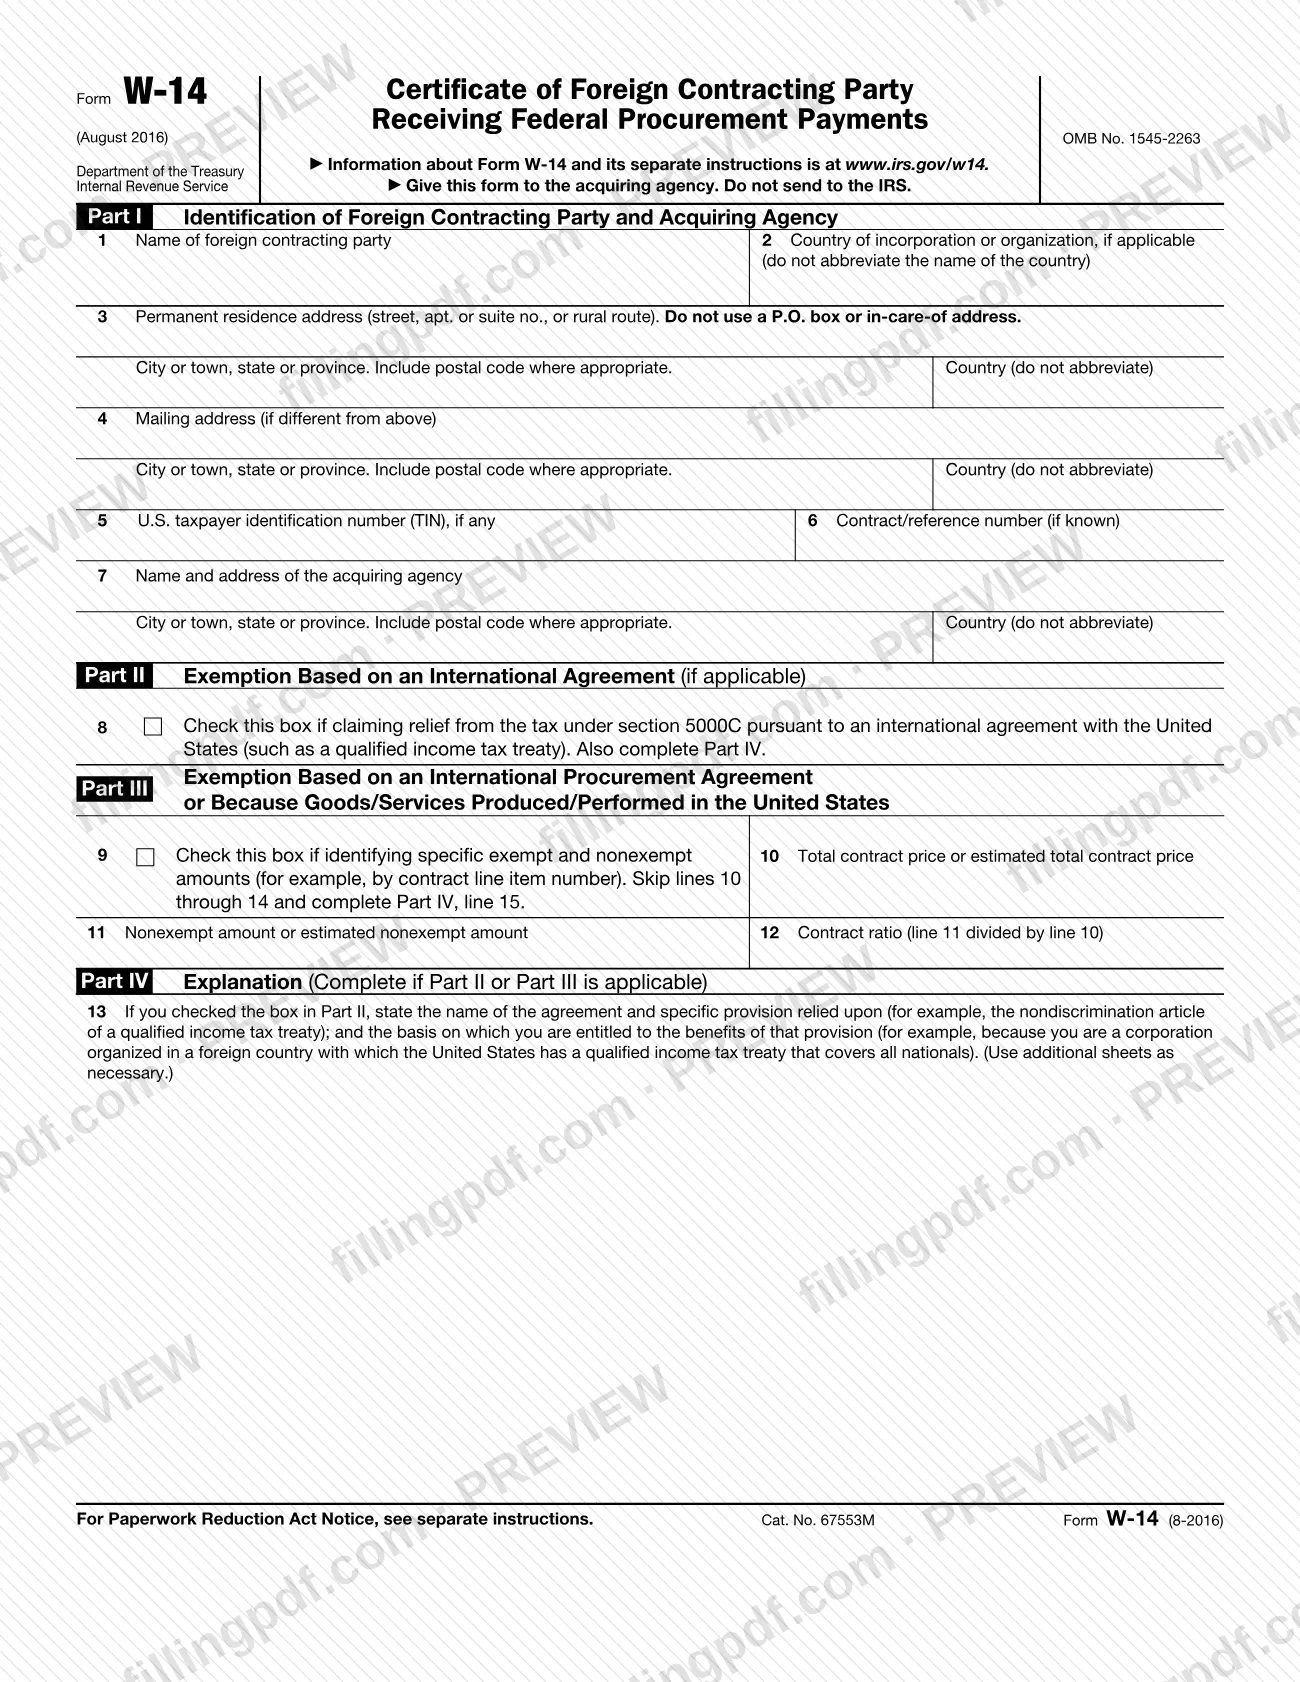
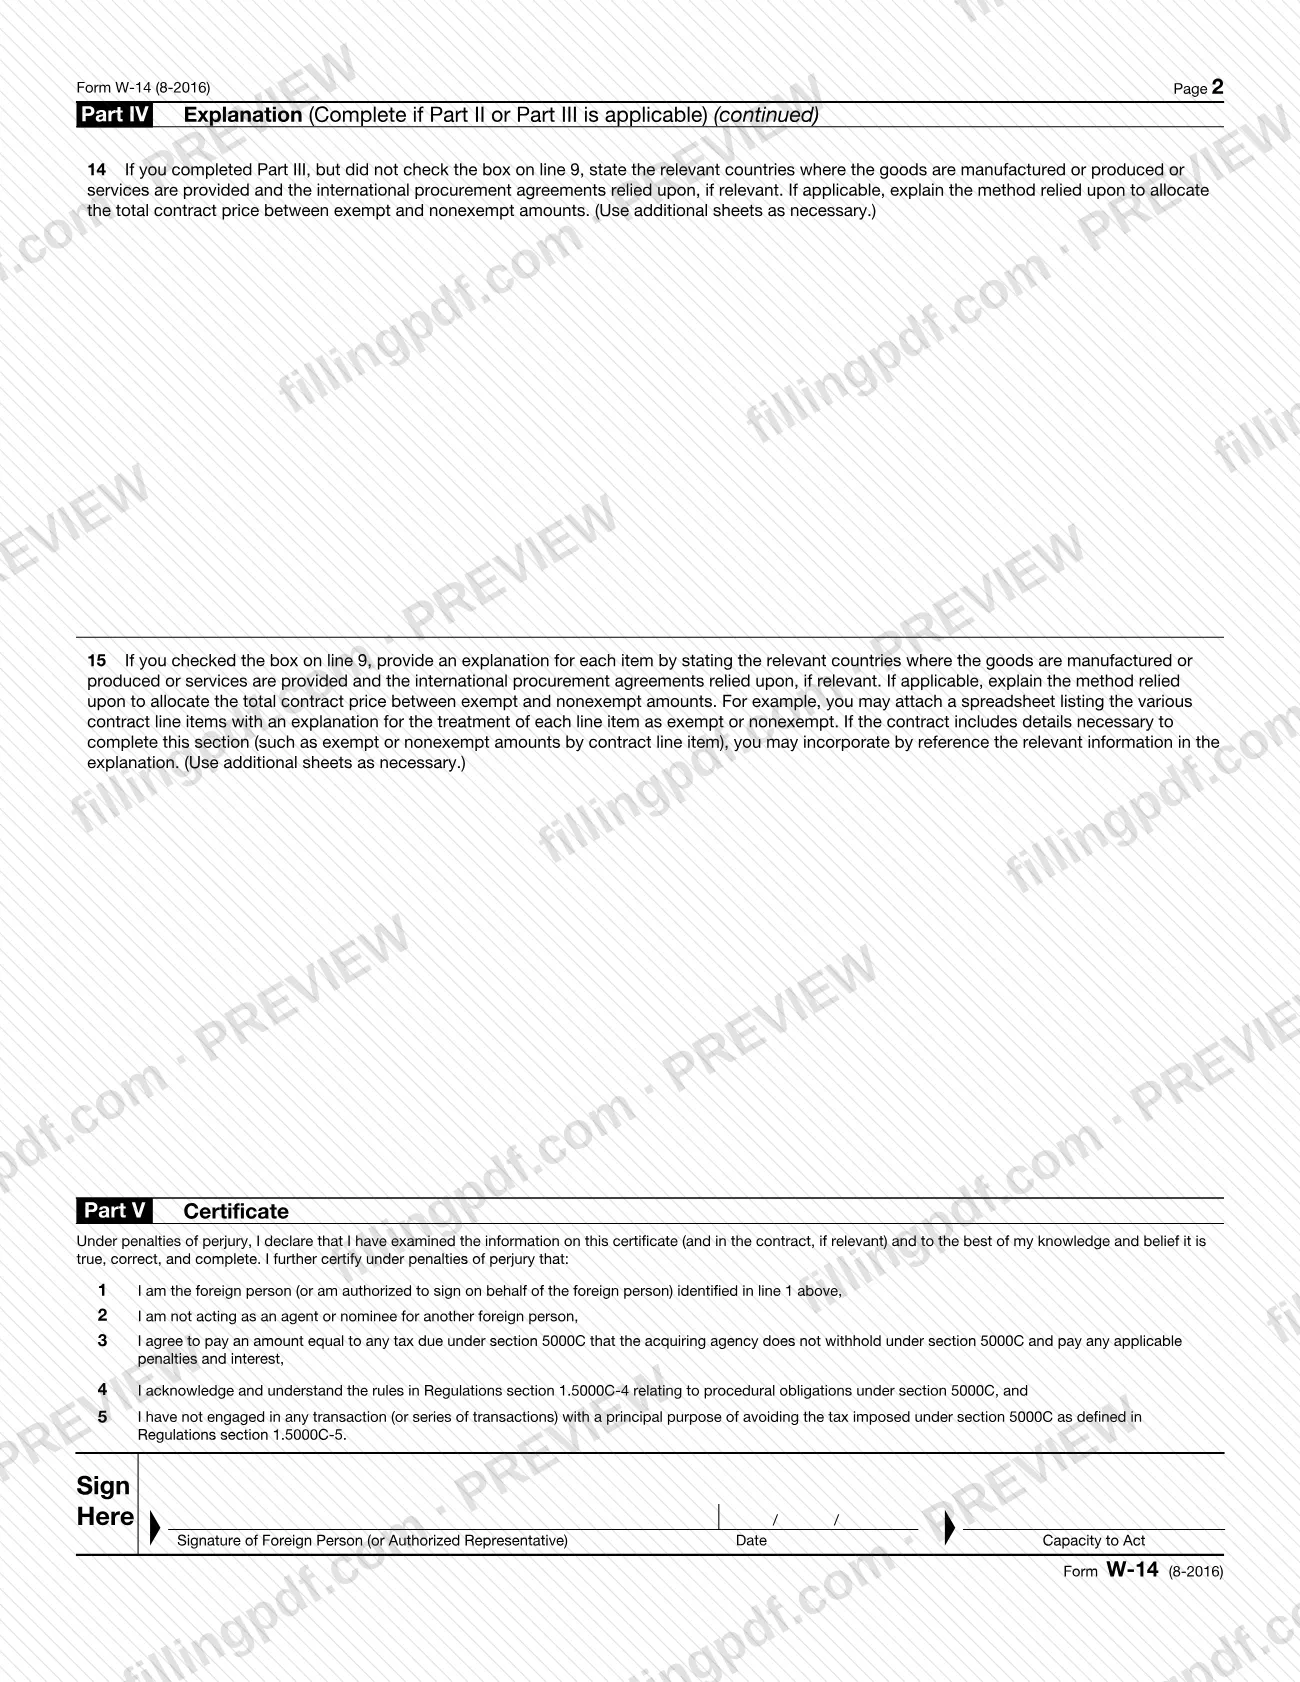
Form W-14 (w14), Certificate of Foreign Contracting Party Receiving Federal Procurement Payments, is an Internal Revenue Service (IRS) certificate completed by foreign persons who hold a contract with the U.S. government. It identifies the contracting party and lets it claim an exemption, in whole or in part, from the tax imposed by section 5000C. On this page you can fill out the form online on FillingPDF and download or print the completed PDF. The IRS publishes the form and its separate instructions at www.irs.gov/w14, and the completed certificate goes to the acquiring agency, not to the IRS.
Last updated
What is W-14?
Form W-14, Certificate of Foreign Contracting Party Receiving Federal Procurement Payments, is the IRS form a foreign contracting party gives to the U.S. government agency that is a party to its contract, to establish its foreign status and to claim any exemption from section 5000C withholding.
Section 5000C imposes a tax on foreign persons that receive specified federal procurement payments under certain contracts with the U.S. government entered into on or after January 2, 2011. The tax is imposed on the gross amount of those payments and is generally collected by withholding under chapter 3. The certificate is the Section 5000C Certificate that the acquiring agency holds.
The form supports two kinds of exemption claims:
- Part II, line 8: relief under an international agreement with the United States, such as a qualified income tax treaty. Part IV must then be completed.
- Part III, lines 9 to 12: exemption based on an international procurement agreement, or because the goods are produced or the services performed in the United States.
Part V is a certificate signed under penalties of perjury. The instructions list qualified income tax treaties in Appendix A (treaties covering all nationals) and Appendix B (treaties covering only individual nationals).
Form W-14 is not for U.S. persons. They use Form W-9, Request for Taxpayer Identification Number and Certification.
Who needs to file W-14?
You provide Form W-14 if you are a foreign contracting party that is due to receive a specified federal procurement payment under a contract and you want to claim an exemption, in whole or in part, from the section 5000C tax. You must also submit it whenever the acquiring agency requests it, whether or not you are claiming an exemption from withholding.
A foreign contracting party is any foreign person, meaning any person other than a U.S. person, that is a party to a contract with the U.S. government entered into on or after January 2, 2011. The person signing must be the foreign person named on line 1 or be authorized to sign for it, and must not be acting as an agent or nominee for another foreign person.
Do not use Form W-14 if:
- the payment is for any purpose other than goods or services;
- you are a U.S. person (use Form W-9);
- the payment is for purchases or personal services under simplified acquisition procedures that do not exceed the simplified acquisition threshold in 48 CFR 2.101;
- the payment is for emergency acquisitions under the "unusual and compelling urgency" authority of 48 CFR 6.302-2 or the emergency acquisition flexibilities in 48 CFR Part 18; or
- the payment is for purchases under a foreign humanitarian assistance contract described in Treasury Regulations section 1.5000C-1(d)(4).
In those cases, you may still choose to submit a certificate that includes all the information required by Treasury Regulations section 1.5000C-2(d).
When to file W-14
Give Form W-14 to the acquiring agency before you earn or receive payments under the contract. The instructions say to provide it as early as practicable, for example when the offer for the contract is submitted to the U.S. government, and in any event no later than the date the contract is executed.
If a change in circumstances makes any information on a Form W-14 you submitted incorrect, notify the acquiring agency within 30 days of the change and provide a new Form W-14 or other appropriate form. The same 30-day period applies to a revised Section 5000C Certificate when the one held by the acquiring agency becomes incorrect.
Generally, a Form W-14 stays valid for the term of the contract, unless a change in circumstances makes any of the information incorrect.
Documents you need
- Additional sheets for Part IV, when the explanations on lines 13, 14 or 15 do not fit in the space provided; the form allows additional sheets as necessary.
- A spreadsheet listing the contract line items with an explanation of whether each is exempt or nonexempt, only if you checked the box on line 9 and choose this way to support line 15.
How to fill out W-14
Enter the contracting party's name
Part I, line 1: enter the name of the foreign contracting party. If it is a branch, enter the legal name of the entity that maintains the branch, not the branch's business name.
Enter the country of organization
Line 2: if the party is a corporation, enter its country of incorporation. For another type of entity, enter the country under whose laws it is created, organized or governed, without abbreviating.
Enter the permanent residence address
Line 3: give the address in the country where the party claims to be a resident for income tax purposes, with the country written out in full. Do not use a P.O. box, an in-care-of address or a financial institution's address.
Add a mailing address if different
Line 4: complete it only if the mailing address differs from the line 3 address. Include the postal code where appropriate and do not abbreviate the country.
Enter the TIN and contract number
Line 5: enter the U.S. taxpayer identification number, or the employer identification number for an entity, if any. Line 6: enter the contract or reference number, if known.
Identify the acquiring agency
Line 7: enter the name and address of the acquiring agency, with city or town, state or province, postal code and the country spelled out.
Check line 8 for an international agreement
Part II, line 8: check the box only if you claim relief from the section 5000C tax under an international agreement with the United States, such as a qualified income tax treaty. Part IV must then be completed.
Complete Part III contract amounts
Line 9: check the box if you identify specific exempt and nonexempt amounts, then skip lines 10 to 14 and complete line 15. Otherwise enter the total contract price on line 10, the nonexempt amount on line 11 and the line 11 divided by line 10 ratio on line 12.
Explain the treaty claim on line 13
If you checked line 8, name the agreement and the specific provision relied upon, and the basis on which you are entitled to its benefits. Use additional sheets if needed.
Explain goods and services on lines 14 or 15
If you completed Part III without checking line 9, use line 14 for the countries where goods are produced or services provided, the agreements relied upon and any allocation method. If you checked line 9, give that explanation for each item on line 15.
Review, sign and download the PDF
In Part V, the foreign person or its authorized representative signs, dates and states the capacity to act. Check every line, then download or print the completed PDF from FillingPDF and give it to the acquiring agency.
How to submit W-14
Form W-14 is handed to the acquiring agency, which is the U.S. government department, agency, independent establishment or corporation that is a party to your contract. The form states: "Give this form to the acquiring agency. Do not send to the IRS." The IRS instructions repeat that the form is not to be sent to the IRS office that receives comments.
- Where it goes: the acquiring agency named on line 7 of the form. If a different U.S. government department or agency is making the payments under the contract, that department or agency is also considered the acquiring agency.
- How it is delivered: the form and instructions name no portal, address or delivery method. Ask the contracting officer or the acquiring agency how it wants to receive the certificate.
- What goes with it: any additional sheets you need for the explanations in Part IV, and a spreadsheet if you use one to list contract line items for line 15.
- Timing: before you earn or receive payments, and no later than contract execution.
FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Sending Form W-14 to the IRS; the form says to give it to the acquiring agency and not to send it to the IRS.
- Using a P.O. box or an in-care-of address on line 3, which asks for a permanent residence address.
- Abbreviating the name of the country on line 2, line 3 or line 4; the form says not to abbreviate.
- Entering the business name of a branch on line 1 instead of the legal name of the entity that maintains the branch.
- Checking the box on line 9 and then completing lines 10 through 14; the form says to skip them and complete line 15.
- Checking line 8 or completing Part III and leaving Part IV blank, although Part IV is required when Part II or Part III applies.
- Not telling the acquiring agency within 30 days of a change in circumstances that makes the certificate incorrect.
- Using Form W-14 as a U.S. person instead of Form W-9.
- Giving a financial institution's address on line 3 when the foreign contracting party is not itself a financial institution.
Frequently asked questions
What is Form W-14 used for?
Form W-14 is the certificate a foreign contracting party gives to the acquiring agency of a U.S. government contract. It establishes that you are a foreign contracting party and, if applicable, claims an exemption from section 5000C withholding under an international agreement or because goods or services are produced or performed in the United States.
Do I send Form W-14 to the IRS?
No. The form says to give it to the acquiring agency and not to send it to the IRS. The acquiring agency is the U.S. government department, agency, independent establishment or corporation that is a party to your contract.
When do I have to give the acquiring agency Form W-14?
Before you earn or receive payments under the contract. The instructions say to provide it as early as practicable, such as when the offer is submitted, and no later than the date the contract is executed.
How long is Form W-14 valid?
Generally it stays valid for the term of the contract. A change in circumstances that makes any information incorrect ends that: you must notify the acquiring agency within 30 days and provide a new Form W-14 or other appropriate form.
Do I need Form W-14 if I am a U.S. person?
No. U.S. persons do not use Form W-14; the instructions direct them to Form W-9, Request for Taxpayer Identification Number and Certification. Form W-14 is only for foreign persons who are parties to a contract with the U.S. government.
What is a qualified income tax treaty on Form W-14?
It is a U.S. income tax treaty in force with a non-discrimination article that applies to the section 5000C tax. Appendix A of the instructions lists treaties covering all nationals, and Appendix B lists those covering only individual nationals. Claim it on line 8 and explain it on line 13.
What is the difference between line 9 and lines 10 to 12?
Check line 9 if you identify specific exempt and nonexempt amounts, such as by contract line item; then skip lines 10 to 14 and complete line 15. If you do not check it, enter the total price, the nonexempt amount and their ratio on lines 10 to 12.
Can I fill out Form W-14 online?
Yes. You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not deliver the certificate; you give it to the acquiring agency yourself.
Ready to fill out W-14?
Fill out W-14 now