
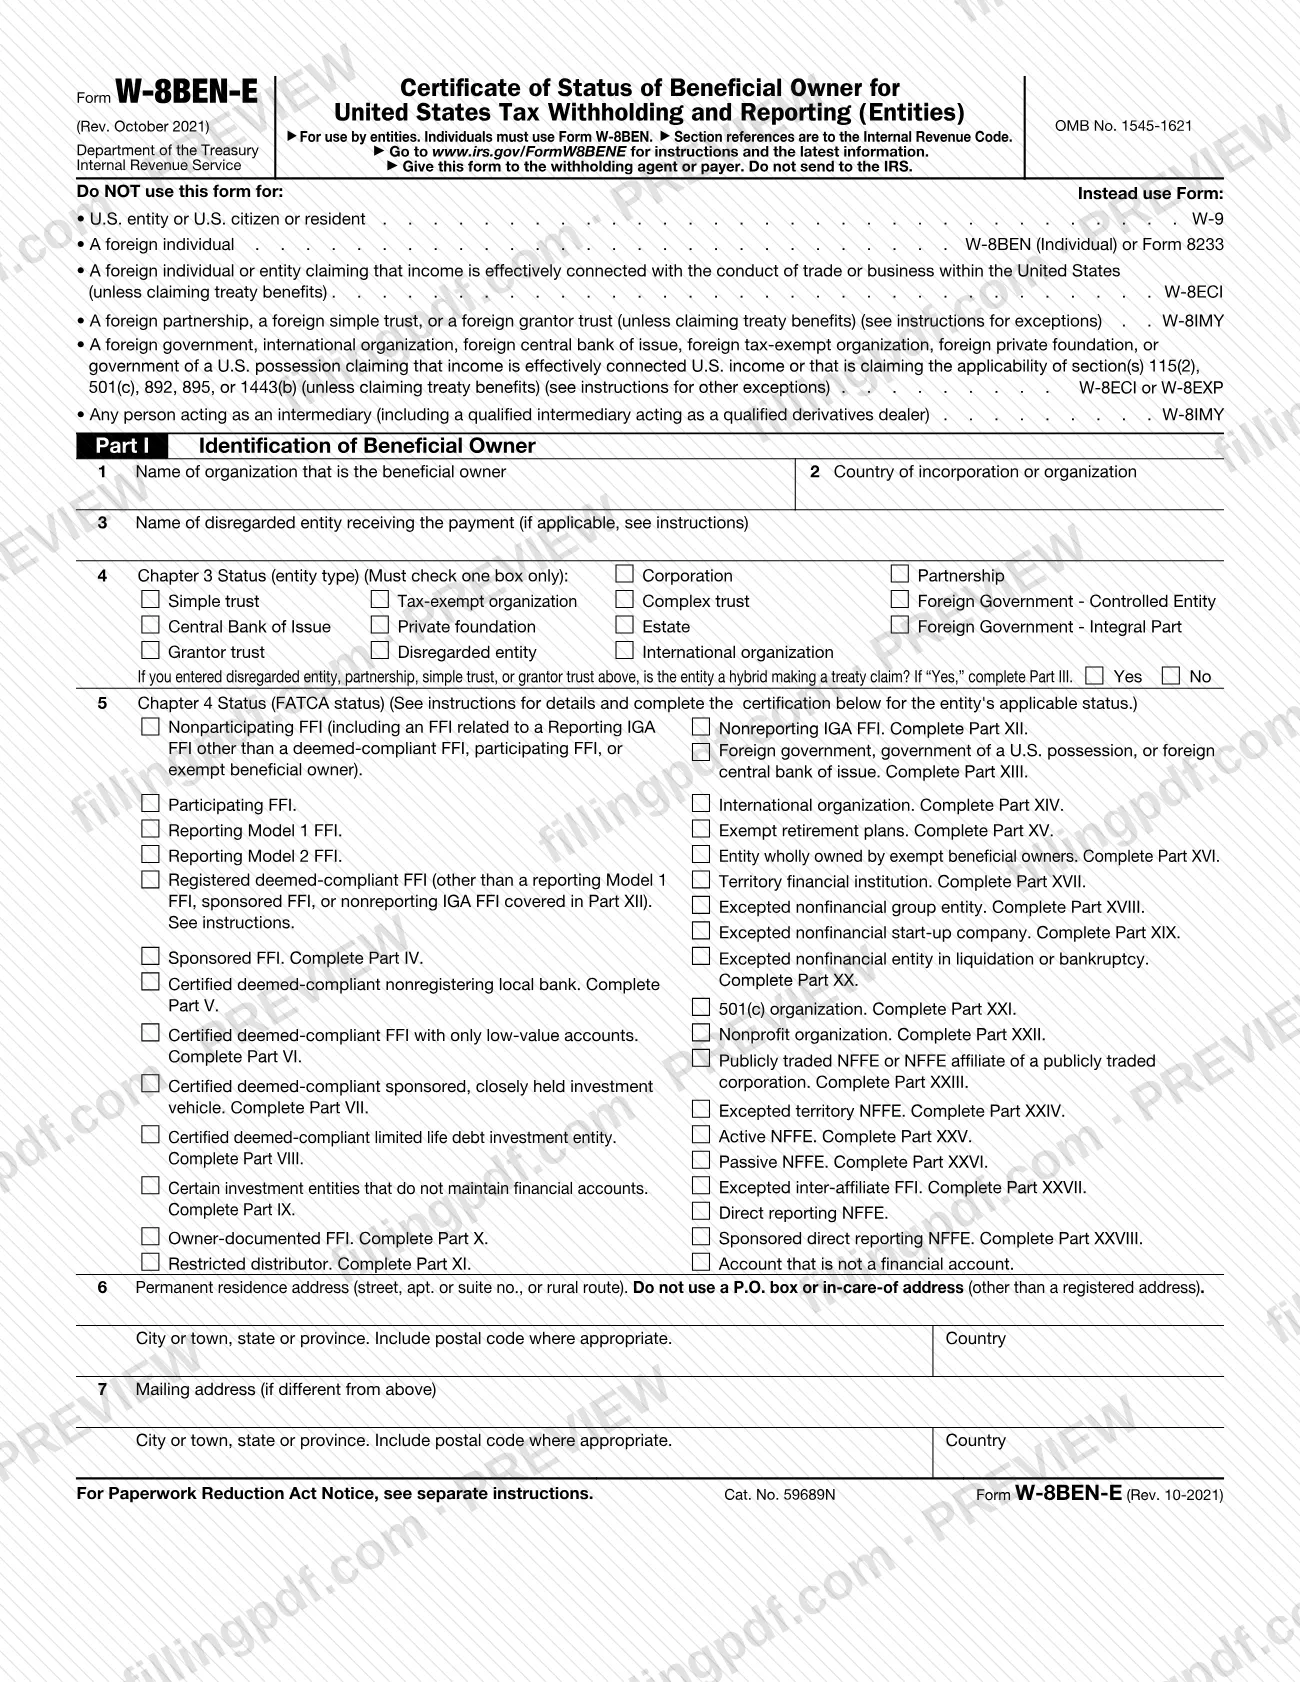
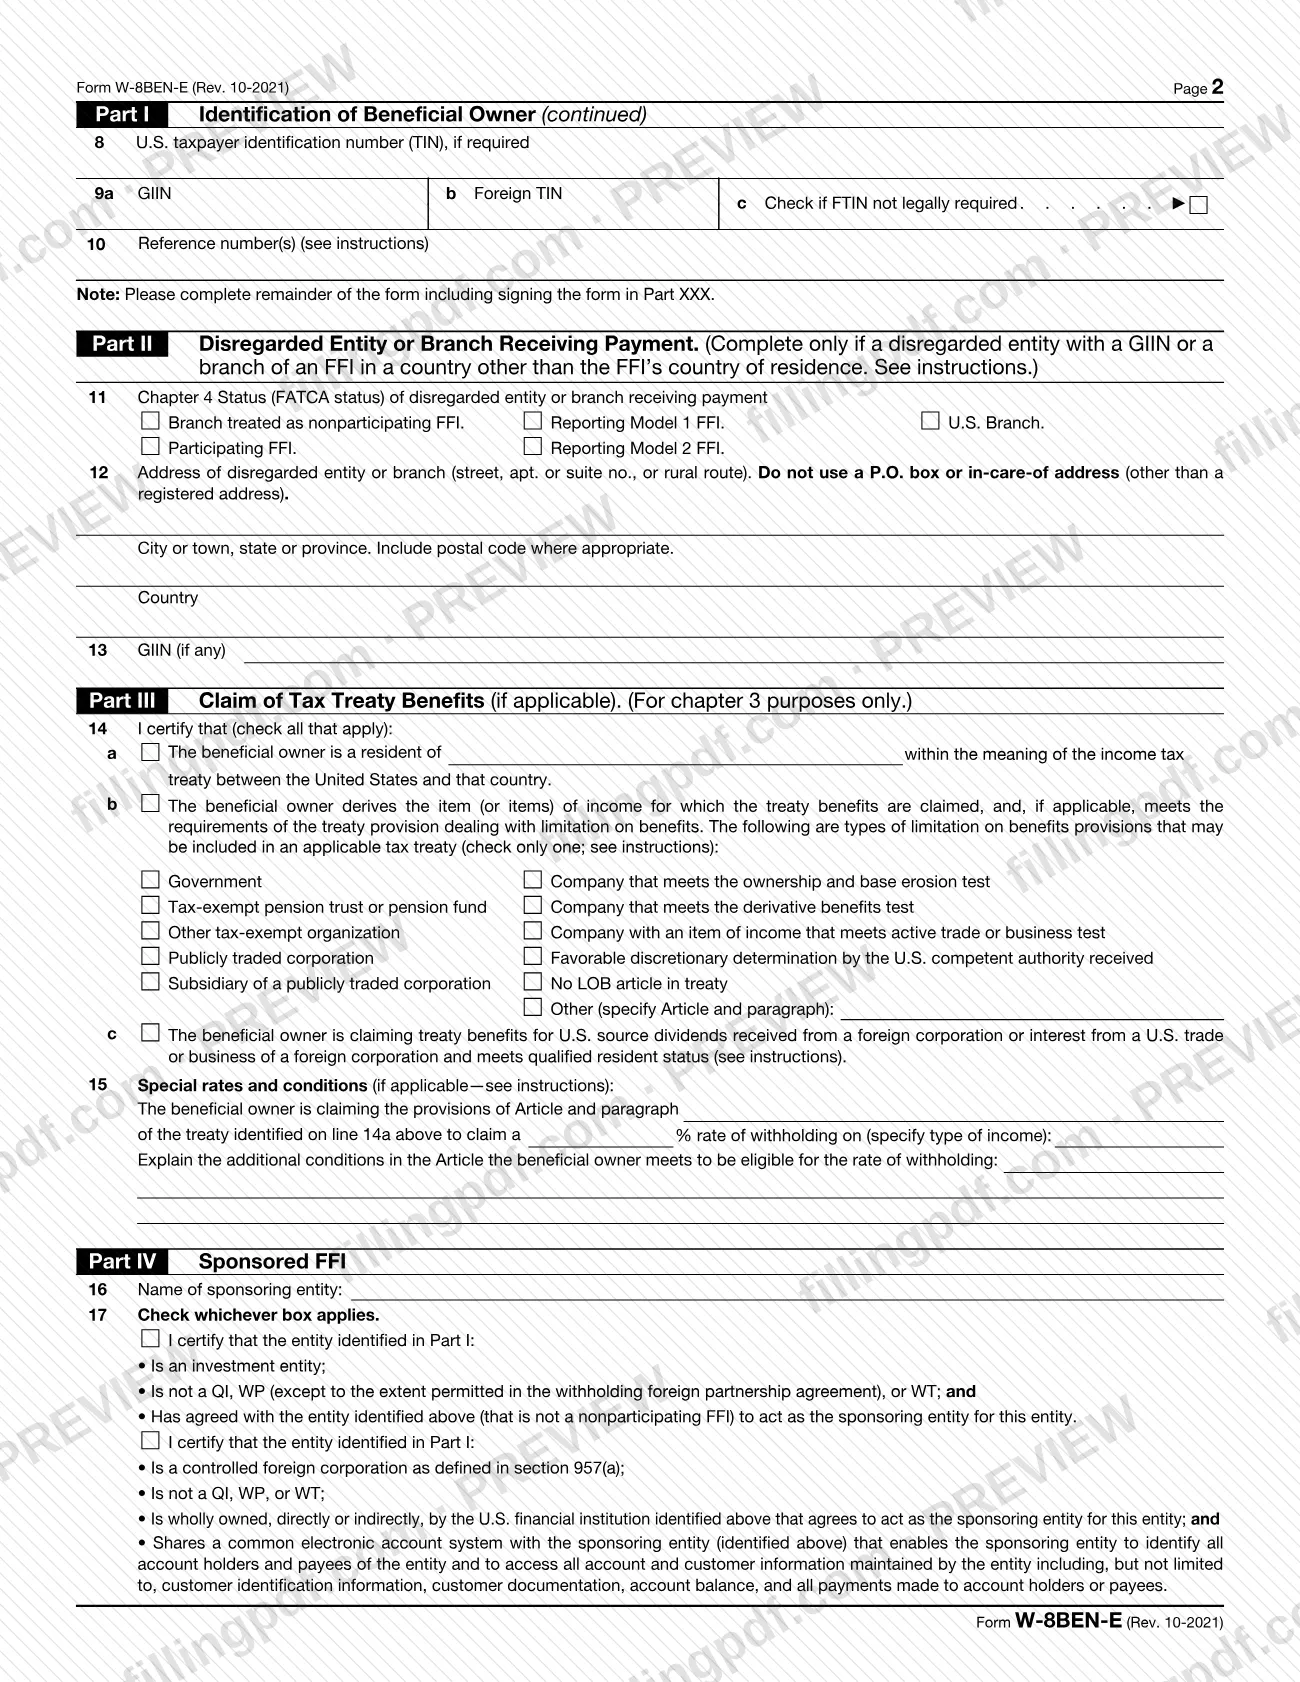
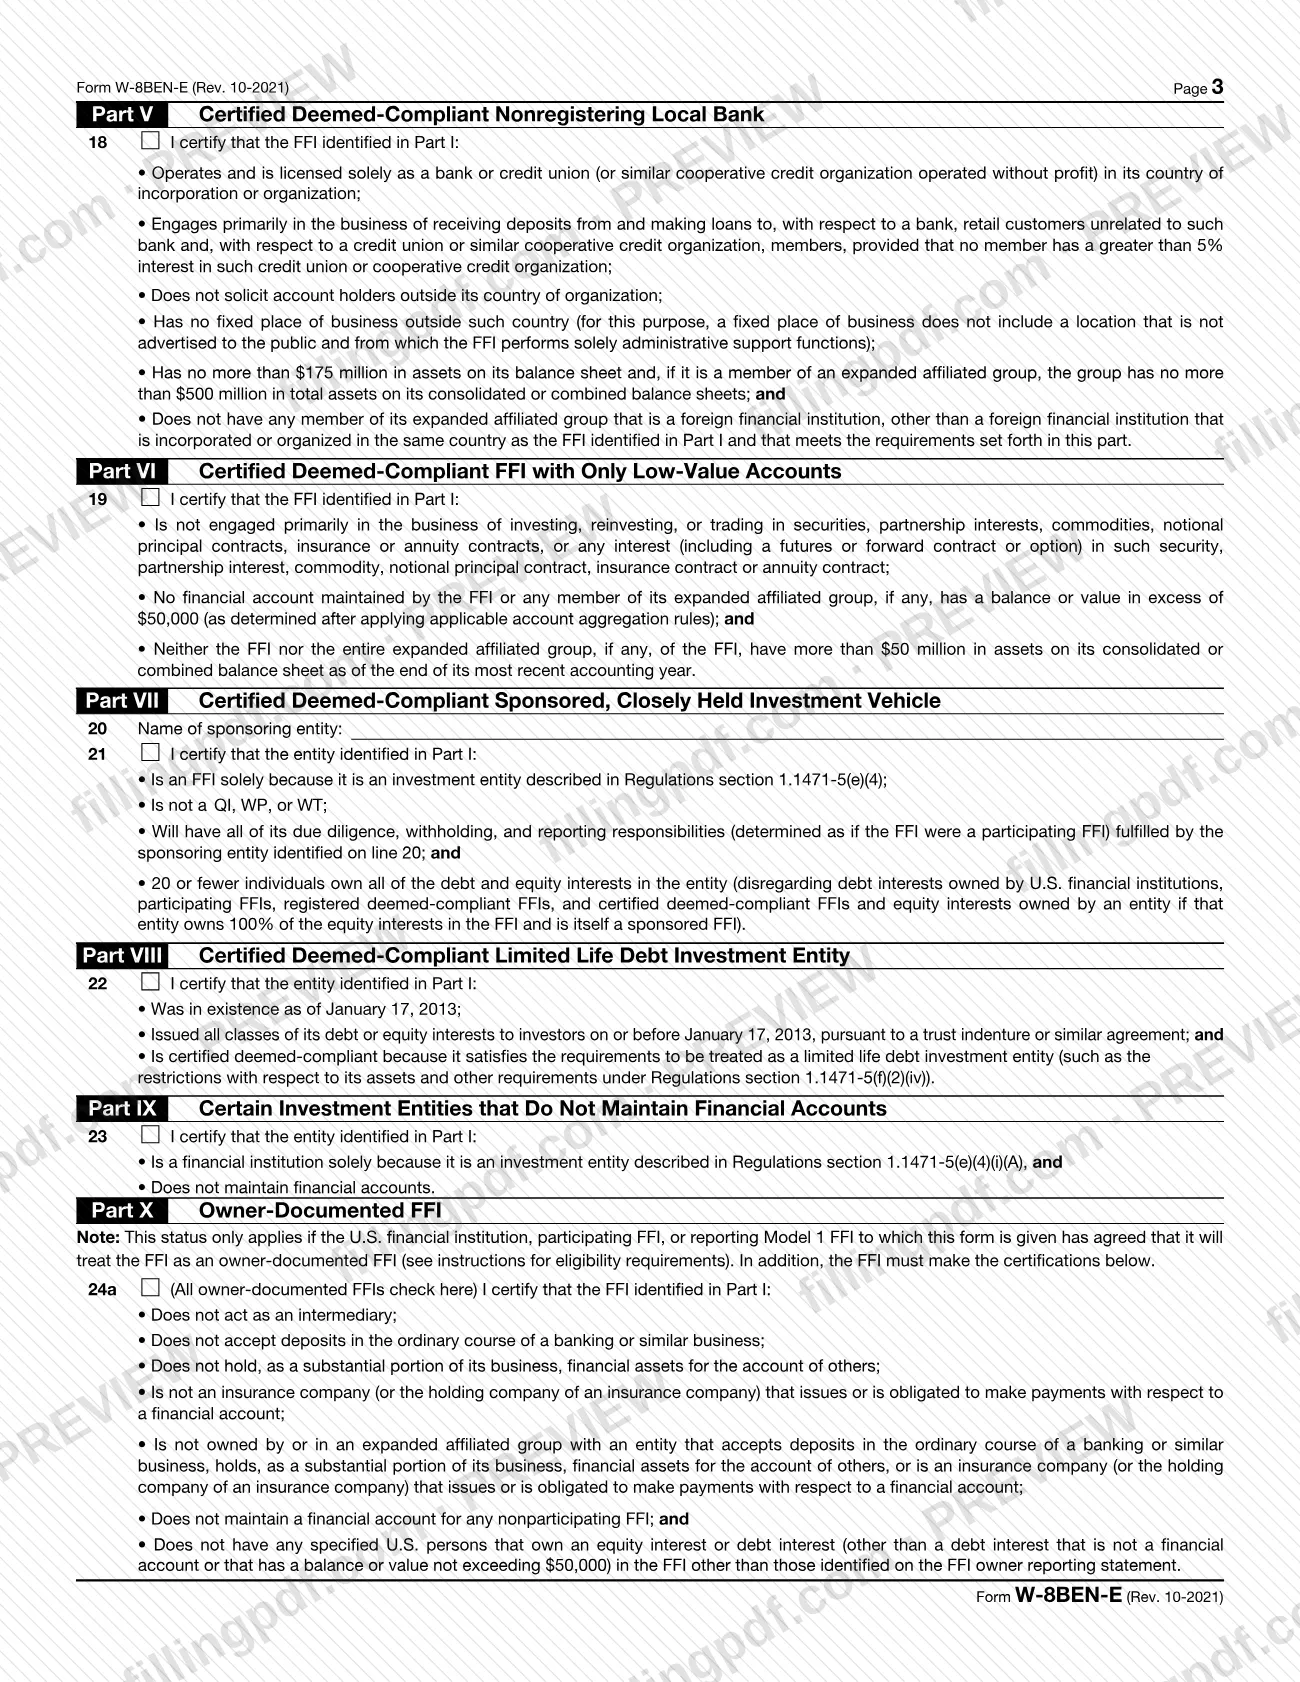
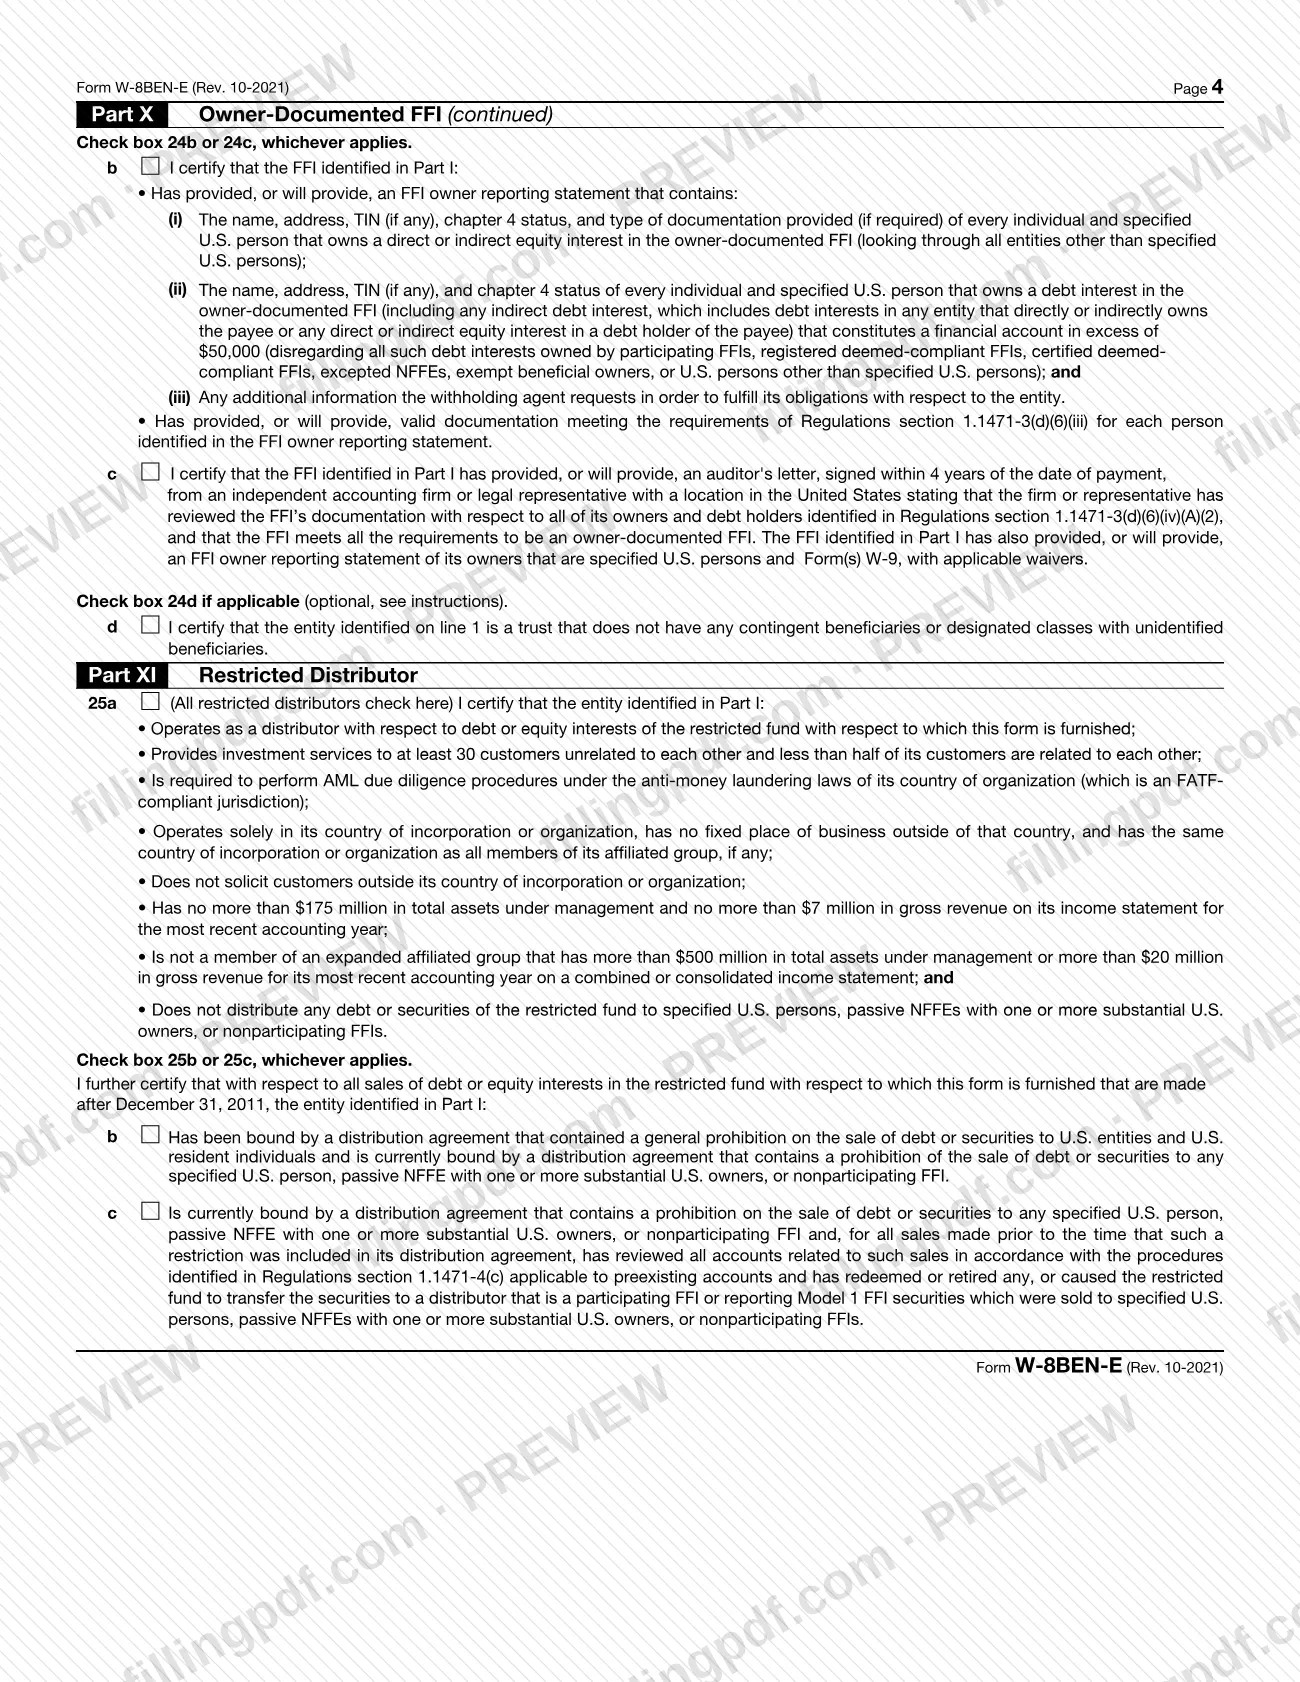
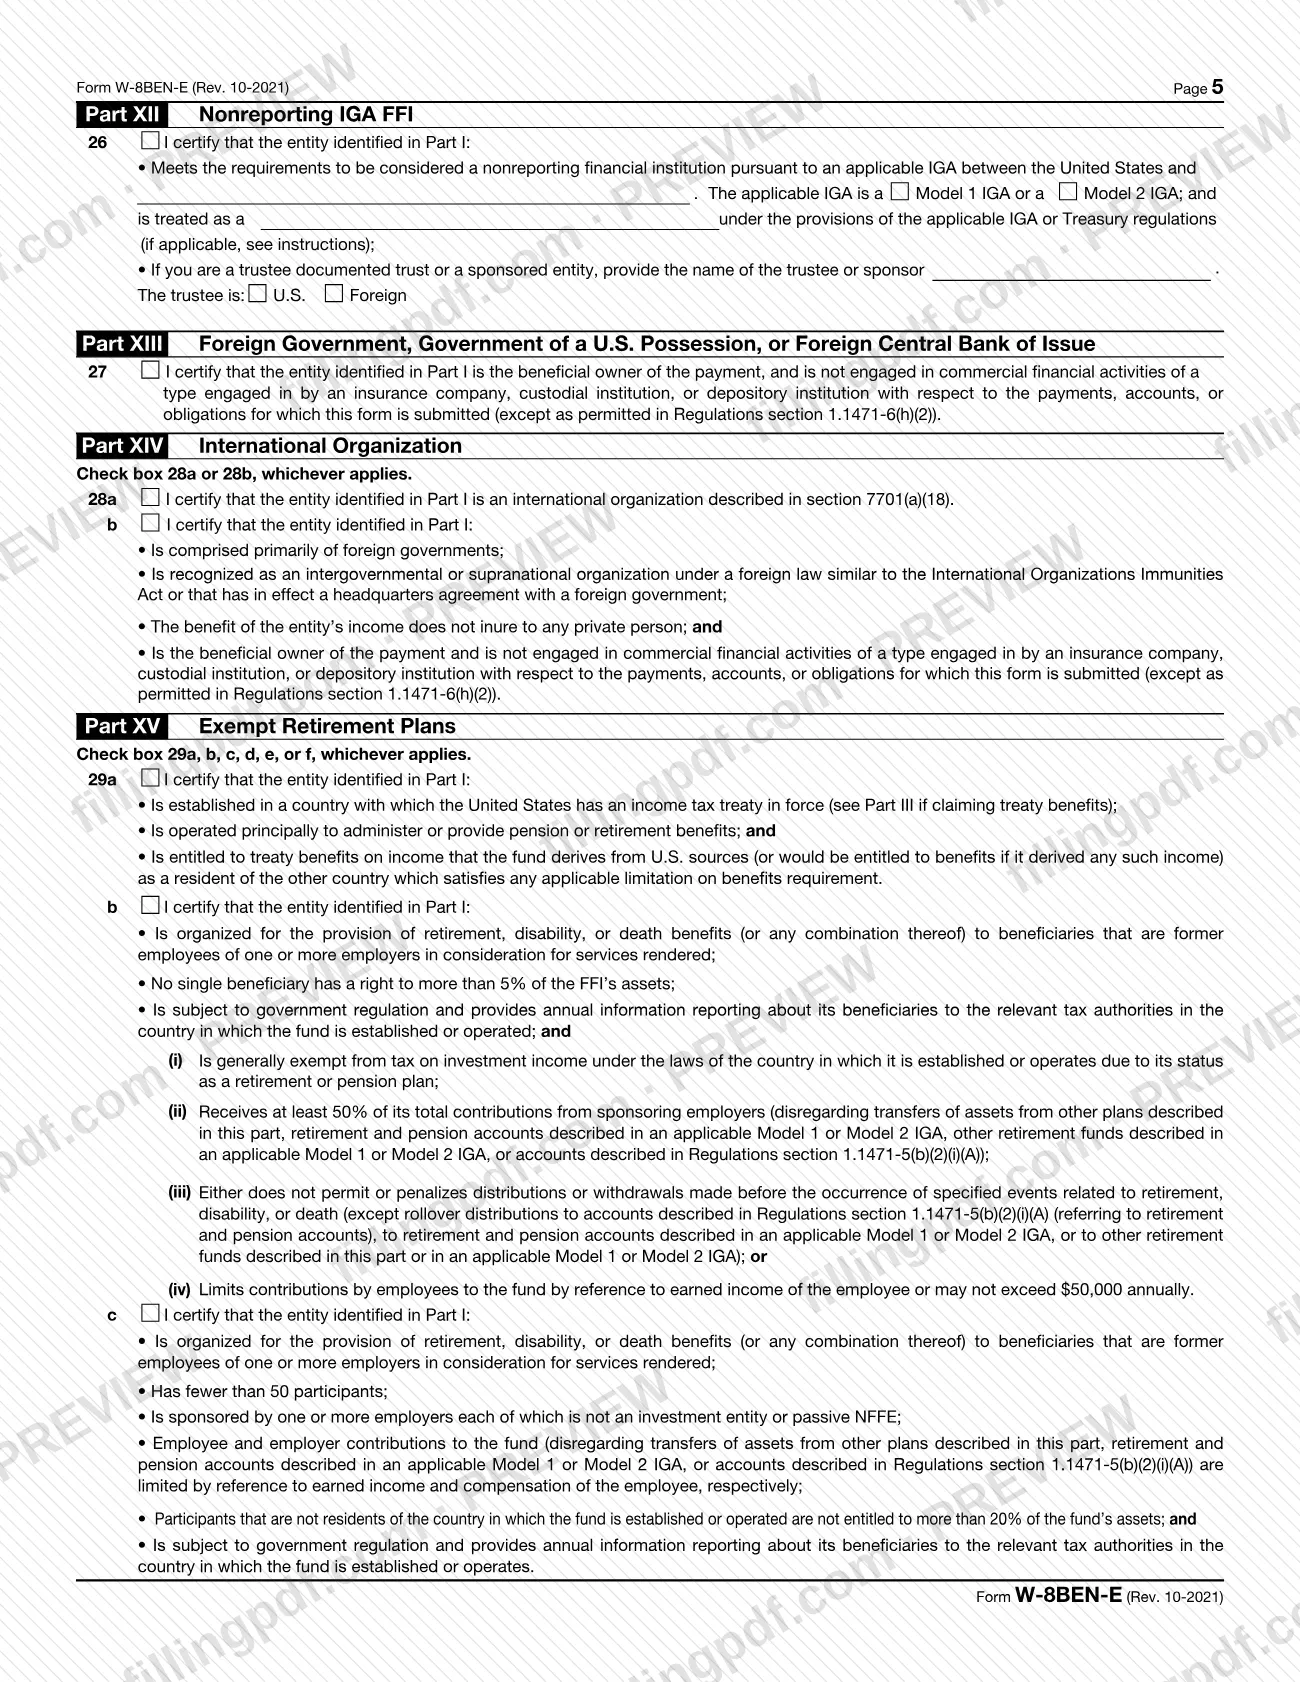
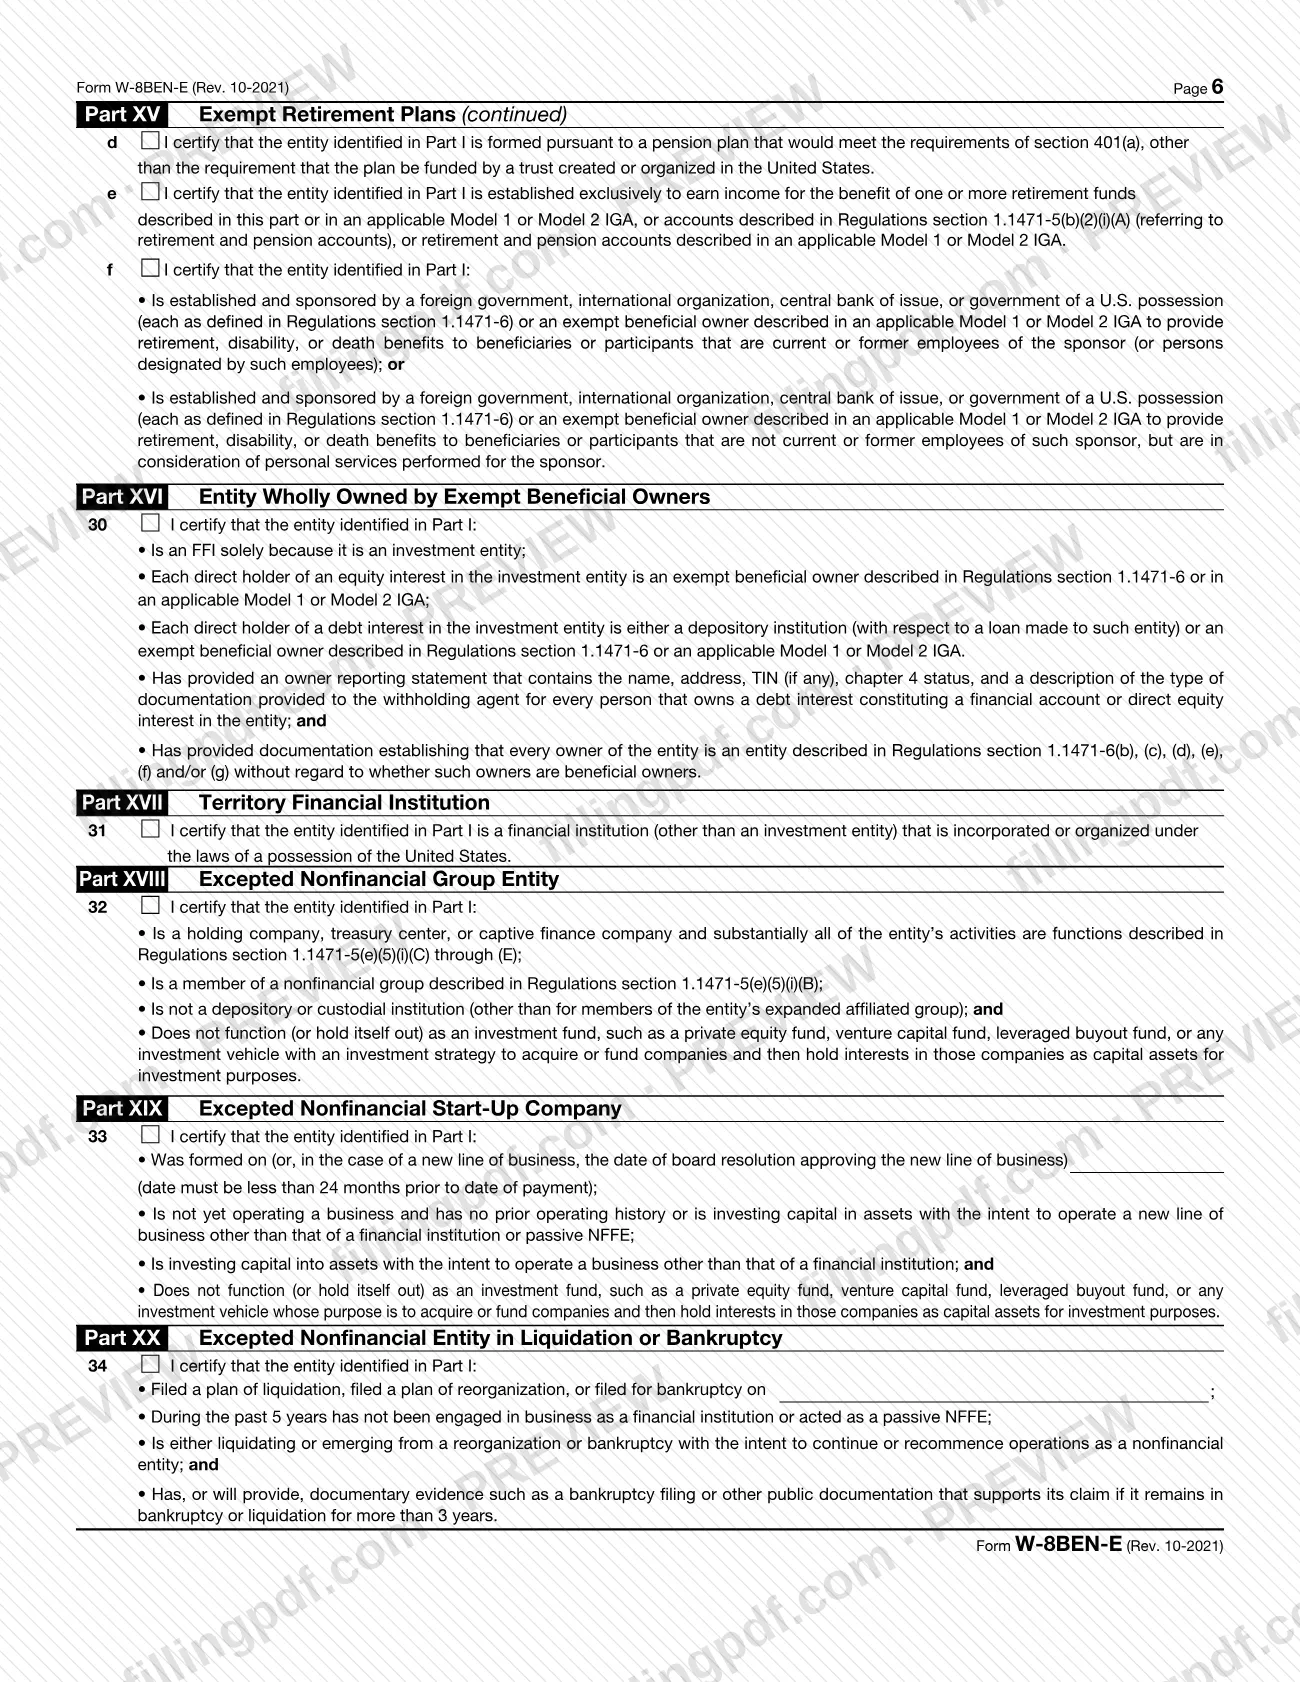
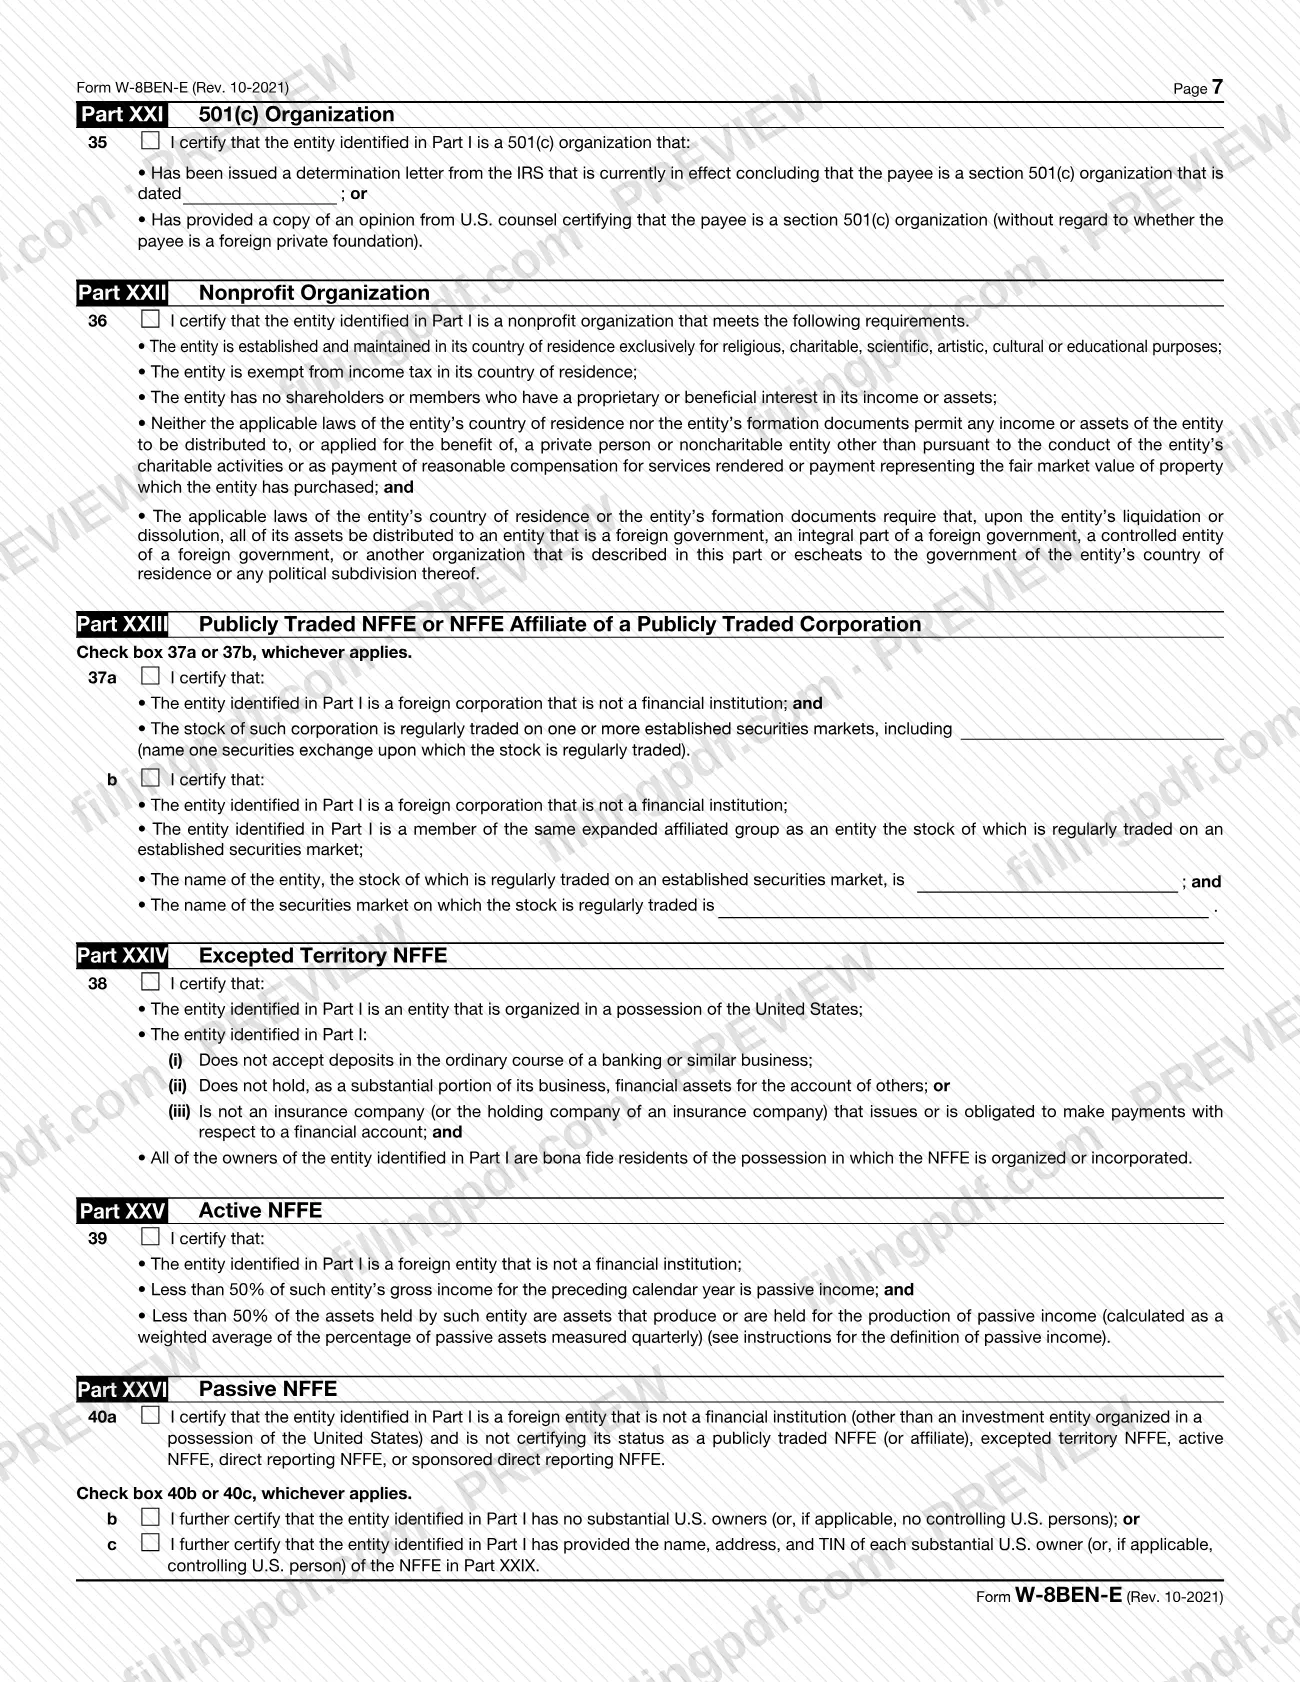
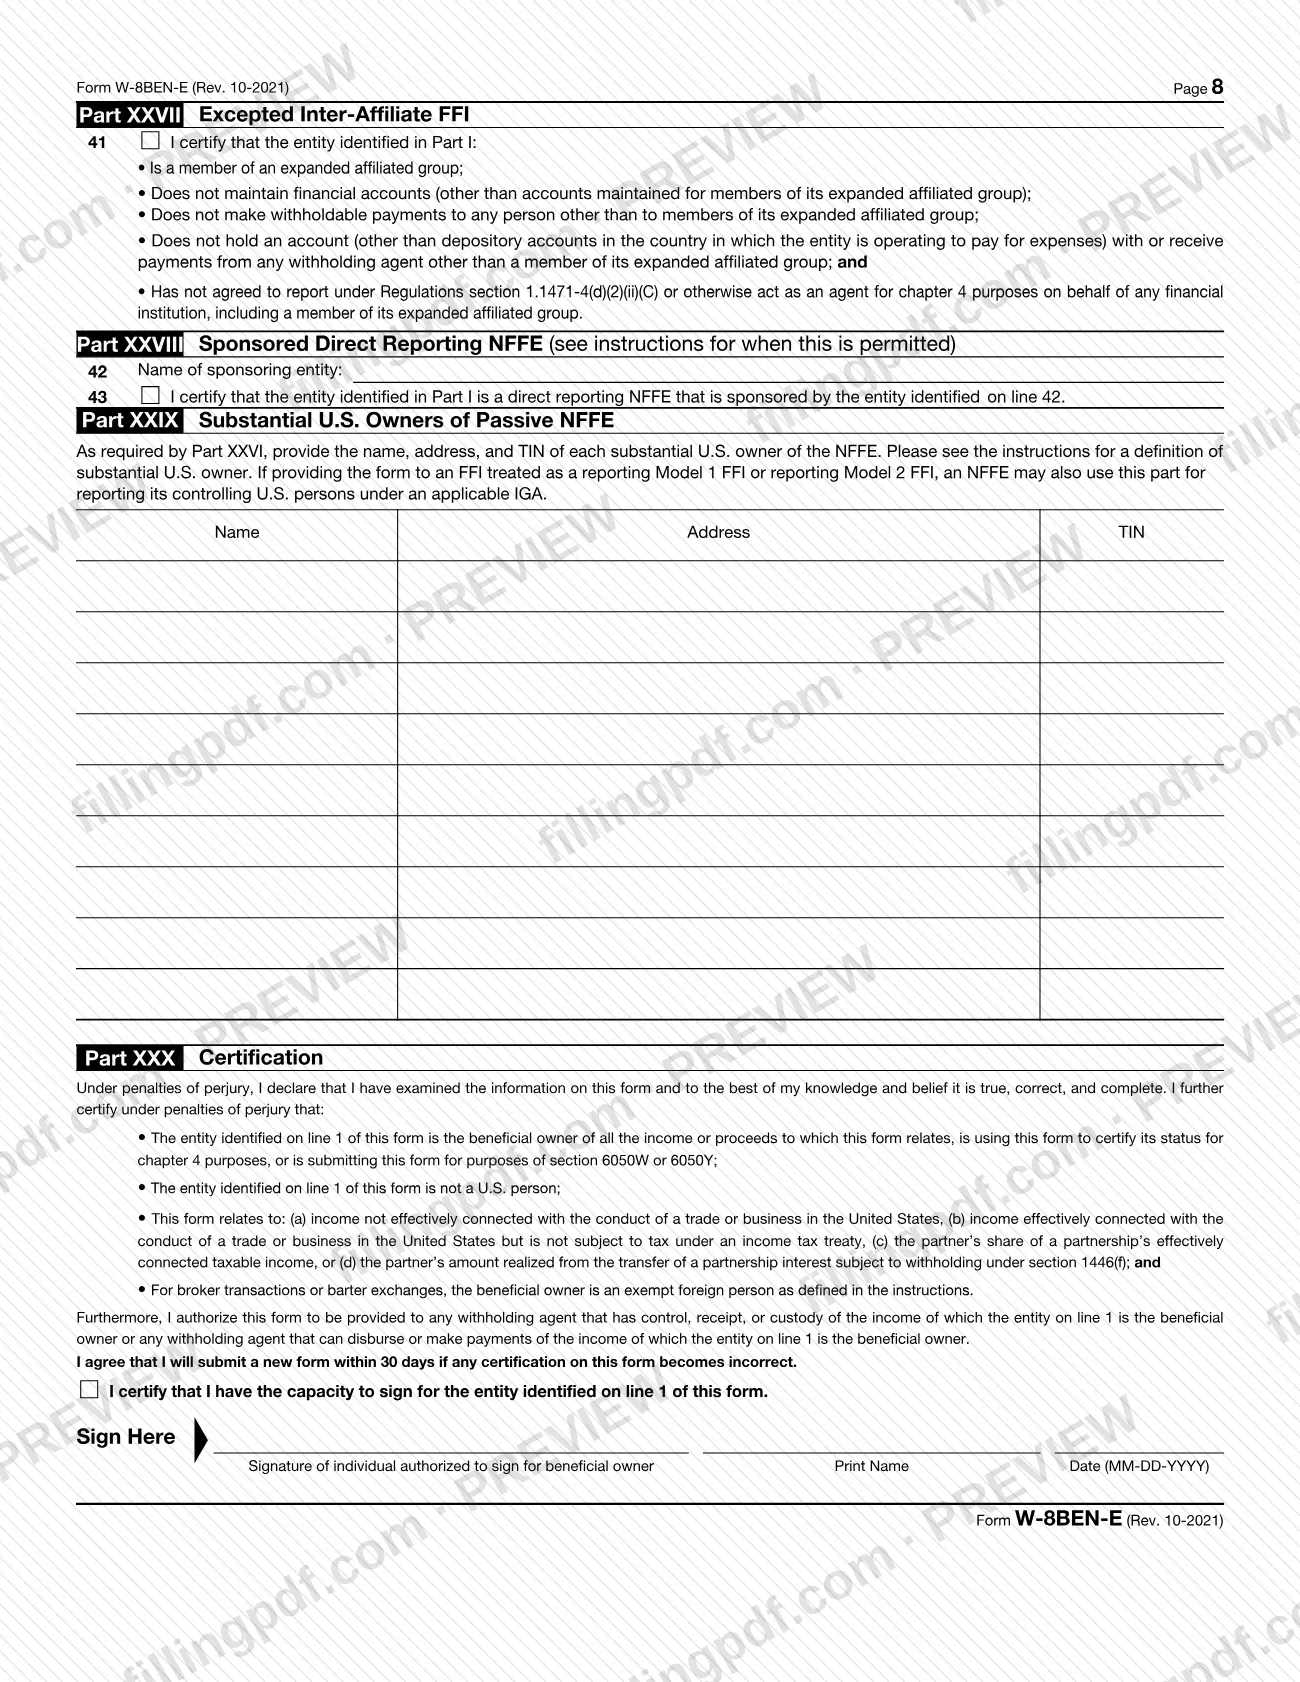
Form W-8BEN-E, Certificate of Status of Beneficial Owner for United States Tax Withholding and Reporting (Entities), is the Internal Revenue Service (IRS) certificate that a foreign entity gives to a withholding agent or payer to document its status for U.S. tax withholding and reporting. Entities use it to establish foreign status, claim a reduced rate or exemption under an income tax treaty, and state a chapter 4 (FATCA) status; individuals must use Form W-8BEN instead. On FillingPDF you can fill out the form online and download or print the completed PDF. The form goes to the person who requests it, not to the IRS, and the IRS publishes the original and its instructions at www.irs.gov/FormW8BENE.
Last updated
What is W-8BEN-E?
Form W-8BEN-E, Certificate of Status of Beneficial Owner for United States Tax Withholding and Reporting (Entities), is the IRS form that foreign entities use to document their status for chapter 3 and chapter 4 of the Internal Revenue Code and for certain other provisions, so that a withholding agent can treat a payment as made to a foreign beneficial owner.
The IRS instructions explain what the certificate supports. A withholding agent or payer may rely on a properly completed form to apply a reduced rate of, or an exemption from, withholding, including under an income tax treaty. The same form can document an exception from Form 1099 reporting and backup withholding on certain income, support the portfolio interest exemption, and establish an entity's chapter 4 status or its status as an account holder with a foreign financial institution (FFI).
The form (OMB No. 1545-1621, Rev. October 2021) runs to 30 parts. Part I identifies the beneficial owner and its chapter 3 and chapter 4 status. Part II covers a disregarded entity or branch receiving payment. Part III claims treaty benefits. Parts IV through XXVIII are the certifications tied to the chapter 4 status checked on line 5. Part XXIX lists substantial U.S. owners of a passive NFFE, and Part XXX is the signed certification.
It is not the only Form W-8. The printed form directs individuals to Form W-8BEN or Form 8233, U.S. entities and citizens to Form W-9, and intermediaries and most foreign partnerships and trusts to Form W-8IMY. Entities claiming effectively connected income use Form W-8ECI, and certain foreign governments and tax-exempt organizations use Form W-8EXP.
Who needs to file W-8BEN-E?
A foreign entity must give Form W-8BEN-E to the withholding agent or payer if it receives a withholdable payment, receives a payment subject to chapter 3 withholding, or maintains an account with an FFI that requests the form. A foreign entity that is the seller of a life insurance contract, or that receives a reportable death benefit, also provides it to the issuer or payor for section 6050Y purposes, unless it is a partnership, simple trust or grantor trust.
Do not use this form if you are:
- a U.S. person or entity, including a corporation organized under state law (use Form W-9);
- a nonresident alien individual (use Form W-8BEN or Form 8233);
- receiving income effectively connected with a U.S. trade or business (use Form W-8ECI), unless it is allocable to you through a partnership;
- acting as an intermediary, a qualified intermediary or a qualified securities lender (use Form W-8IMY);
- a foreign reverse hybrid entity, a withholding foreign partnership or trust, or a foreign partnership or grantor trust documenting for section 1446 (use Form W-8IMY);
- a foreign government, international organization, central bank of issue or similar body claiming section 115(2), 892, 895 or 501(c) treatment (use Form W-8EXP), although you should use this form if you claim treaty benefits.
A disregarded entity, branch or flow-through entity generally does not give this form, except in the cases the instructions describe, such as documenting chapter 4 status for an FFI account or claiming treaty benefits as a hybrid entity.
When to file W-8BEN-E
Give Form W-8BEN-E to the requester before the payment is made to you, credited to your account or allocated to you. If you do not provide it, the withholding agent may have to withhold at the full rate under chapter 3 or 4, at the backup withholding rate, or at the rate that applies under section 1446.
A form generally stays valid for chapters 3 and 4 from the date you sign it through the last day of the third succeeding calendar year, unless a change in circumstances makes any information on it incorrect. Under certain conditions it can stay in effect indefinitely, as the cited Treasury regulations explain. If a change in circumstances makes the information incorrect, notify the withholding agent or financial institution within 30 days, and the certification on the form says you will submit a new form within 30 days. A withholding agent may require a separate form for each type of income when you claim different benefits, and generally each withholding agent needs its own form.
Documents you need
- A statement attached to the form, if your GIIN or foreign TIN does not fit on line 9a or 9b, clearly identified as furnished for that line.
- A schedule with the Part II information for each branch or disregarded entity, if several receive payments from the same withholding agent and the Part I information is the same.
- For an owner-documented FFI that checks line 24b: an FFI owner reporting statement and valid documentation for each person it identifies.
- For an owner-documented FFI that checks line 24c: an auditor's letter, signed within 4 years of the date of payment, plus an FFI owner reporting statement of specified U.S. owners and Form(s) W-9 with applicable waivers.
- For a 501(c) organization on Part XXI: the IRS determination letter currently in effect, or a copy of an opinion from U.S. counsel certifying 501(c) status.
- For an excepted nonfinancial entity in liquidation or bankruptcy that stays in that status for more than 3 years: documentary evidence, such as a bankruptcy filing or other public documentation.
- For an entity wholly owned by exempt beneficial owners (Part XVI): an owner reporting statement and documentation establishing that every owner is an entity described in the cited regulation.
How to fill out W-8BEN-E
Identify the beneficial owner
Line 1: enter the name of the organization that is the beneficial owner. A disregarded entity or branch enters its owner's legal name instead. Line 2: enter the country of incorporation or organization, and on line 3 the name of a disregarded entity receiving the payment, if applicable.
Check your chapter 3 status
Line 4: check the one box for your entity type, such as Corporation, Partnership, Simple trust, Complex trust, Grantor trust, Estate or Disregarded entity. If you checked Disregarded entity, Partnership, Simple trust or Grantor trust, answer the hybrid entity treaty-claim question Yes or No.
Check your chapter 4 status
Line 5: check the one FATCA status that applies, which also tells you which of Parts IV through XXVIII to complete. By checking a box you represent that you qualify for it in your country of residence.
Enter your addresses
Line 6: enter the permanent residence address, the address in the country where you claim residence for income tax, with no P.O. box or in-care-of address (other than a registered address). Line 7: enter a mailing address only if it differs.
Enter tax identification numbers
Line 8: enter your U.S. TIN (EIN) if required. Line 9a: enter your GIIN if your status requires it, or write "applied for". Line 9b: enter your foreign TIN, and check line 9c if you are not legally required to have one.
Add a reference number
Line 10: enter any reference number or account number that helps the withholding agent associate the form with you, if useful.
Complete Part II if it applies
Complete lines 11 through 13 only for a disregarded entity with a GIIN or a branch of an FFI outside the FFI's country of residence: check the branch's chapter 4 status, enter its address and enter its GIIN on line 13.
Claim treaty benefits in Part III
Line 14a: enter the treaty country and check the box to certify residence. Line 14b: check one limitation on benefits box. Line 14c applies only to the older treaties the instructions describe. Line 15: complete only for special rates and conditions, naming the treaty article, paragraph, rate and income type.
Complete your chapter 4 certification part
Go to the part named beside the box you checked on line 5, such as Part XXV for Active NFFE or Part XXVI for Passive NFFE. Check the certification boxes and fill in any names, dates or GIINs the part requests.
List substantial U.S. owners if required
If you checked line 40c as a Passive NFFE, enter the name, address and TIN of each substantial U.S. owner in Part XXIX. A passive NFFE giving the form to a reporting Model 1 or Model 2 FFI may also list controlling U.S. persons there.
Sign and date Part XXX
The individual authorized to sign for the entity signs, prints their name and enters the date in MM-DD-YYYY format. By signing, that person certifies under penalties of perjury that they have the capacity to sign for the entity on line 1.
Review and download the completed PDF
Check that every line matches your line 5 status and that each required part is complete. Download or print the completed PDF from FillingPDF and give it to the requesting withholding agent, payer or FFI as described under How to submit.
How to submit W-8BEN-E
Form W-8BEN-E is given directly to the person who requests it; the IRS does not receive it.
- To the withholding agent or payer: Hand or deliver the signed form to the person from whom you receive the payment, who credits your account, or the partnership that allocates income to you.
- To an FFI: If you hold an account with a foreign financial institution, give the form to the FFI that requests it to document your chapter 4 status.
- Do not send it to the IRS. The printed form and the IRS instructions both say to give it to the requester instead.
The requester may set its own delivery method, so follow the instructions it gives you. Complete every part that applies to your line 5 status before signing, and include any attachments such as a statement for a GIIN or foreign TIN that does not fit in the space, or the schedule for multiple branches. For the requester's side of the process, the IRS points to the Instructions for the Requester of Forms W-8BEN, W-8BEN-E, W-8ECI, W-8EXP, and W-8IMY. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Mailing Form W-8BEN-E to the IRS. The form says to give it to the withholding agent or payer and not to send it to the IRS.
- Using the entity form for an individual. Individuals must use Form W-8BEN, or Form 8233 where the instructions point to it.
- Entering a disregarded entity's own business name on line 1. The instructions say to enter the legal name of its owner, or of the entity a branch forms part of.
- Checking more than one box on line 4 or line 5. Each line takes one box only.
- Skipping the part that matches your line 5 status. Most chapter 4 statuses require the certification in Parts IV through XXVIII before you sign.
- Giving a P.O. box or in-care-of address on line 6. The permanent residence address cannot be one, except a registered address.
- Checking both line 24b and line 24c as an owner-documented FFI. Check one or the other, not both.
- Checking the line 14c box for a treaty that entered into force after December 31, 1986. In that case check the line 14b boxes instead.
- Checking Tax-exempt organization on line 4 when you are not a section 501(c) organization, or when you are a private foundation.
- Not providing a new form within 30 days after a change in circumstances makes the information on it incorrect.
Frequently asked questions
What is Form W-8BEN-E used for?
Form W-8BEN-E is the IRS certificate a foreign entity gives a withholding agent, payer or FFI to document its status for chapter 3 and chapter 4. It supports a foreign-status claim, a reduced rate or exemption under an income tax treaty, and the entity's FATCA classification.
What is the difference between Form W-8BEN and W-8BEN-E?
Form W-8BEN-E is for entities, while Form W-8BEN is for individuals. The printed form says it is for use by entities and that individuals must use Form W-8BEN; foreign individuals claiming certain personal-services exemptions may use Form 8233.
Do I send Form W-8BEN-E to the IRS?
No. The form says to give it to the withholding agent or payer and not to send it to the IRS. Usually this is the person you receive the payment from, who credits your account, or the partnership that allocates income to you.
How long is Form W-8BEN-E valid?
It generally stays valid from the date you sign it through the last day of the third succeeding calendar year, unless a change in circumstances makes information on it incorrect. Under certain conditions it can remain in effect indefinitely, as the cited regulations explain.
What happens if my circumstances change after I submit it?
You must notify the withholding agent or financial institution within 30 days of the change and provide the documentation the instructions require. The Part XXX certification also says you will submit a new form within 30 days if any certification becomes incorrect.
Which part of the form do I complete for my FATCA status?
The box you check on line 5 names the part to complete, for example Part XXV for Active NFFE or Part XXVI for Passive NFFE. Complete only one of Parts IV through XXVIII, and none if you are not a payee of a withholdable payment or an FFI account holder.
Can I claim tax treaty benefits on Form W-8BEN-E?
Yes. Complete Part III: line 14a for treaty residence, line 14b for the limitation on benefits box that applies, and line 15 only for special rates and conditions. A treaty claim also means you may need a U.S. TIN or foreign TIN on the form.
Can I fill out Form W-8BEN-E online?
Yes. You can complete the fillable PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file or send the form; you give it to the withholding agent, payer or FFI that requested it.
Ready to fill out W-8BEN-E?
Fill out W-8BEN-E now