
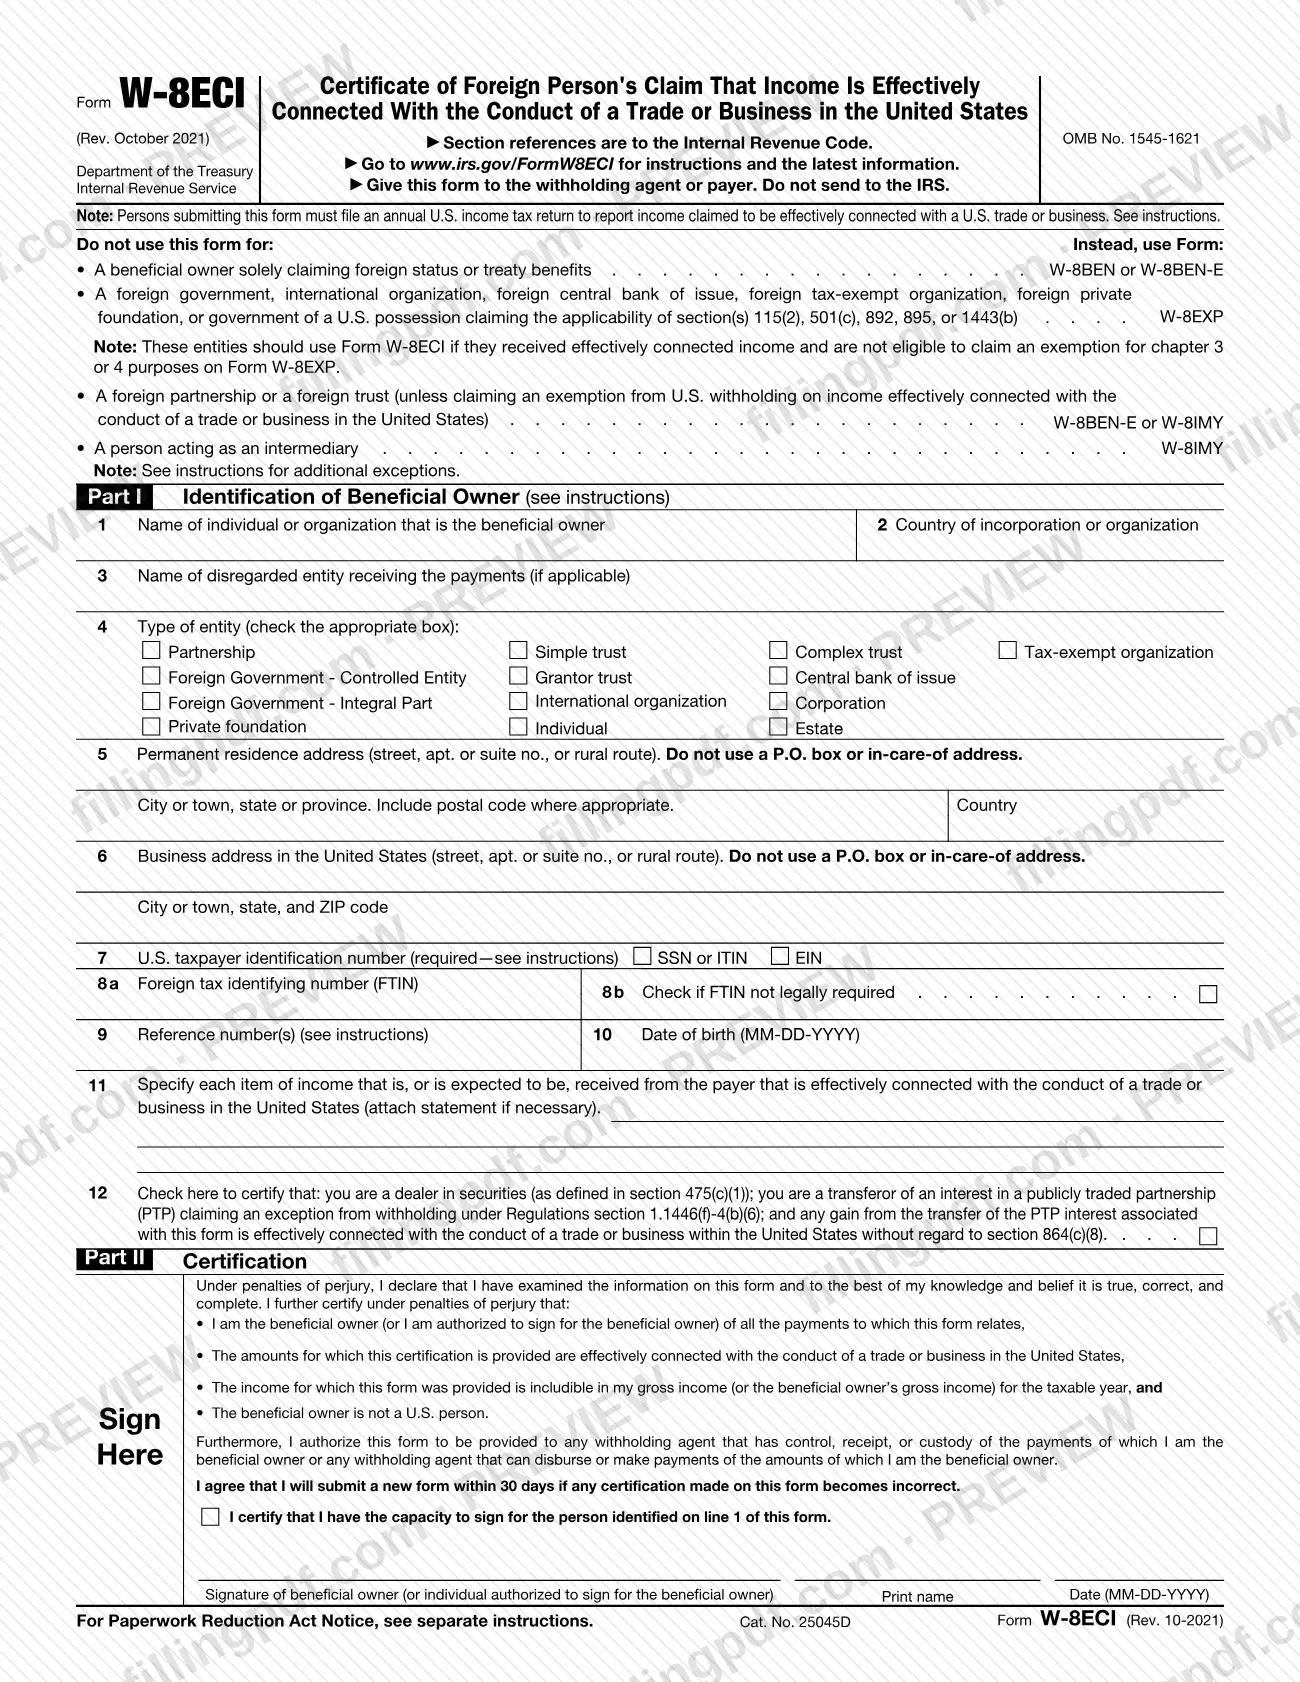
W-8ECI is the Internal Revenue Service (IRS) certificate that a foreign person gives to a withholding agent or payer to claim that U.S. source income is effectively connected with the conduct of a trade or business in the United States. Foreign persons who are the beneficial owners of that income, and entities engaged in a U.S. trade or business that submit the form for their owners, partners or beneficiaries, use it. On FillingPDF you can fill out Form W-8ECI online and download or print the completed PDF. The form is not sent to the IRS; you give it to the person who requests it, and the IRS publishes the PDF and its instructions at irs.gov/FormW8ECI.
Last updated
What is W-8ECI?
Form W-8ECI is the IRS certificate a foreign person gives a withholding agent or payer to claim that U.S. source income is effectively connected with the conduct of a trade or business in the United States.
The full title is Certificate of Foreign Person's Claim That Income Is Effectively Connected With the Conduct of a Trade or Business in the United States. By signing it under penalties of perjury, the beneficial owner (or a person authorized to sign for the owner) certifies that the amounts are effectively connected with a U.S. trade or business, that the income is includible in gross income for the taxable year, and that the beneficial owner is not a U.S. person.
The IRS instructions explain why it matters: foreign persons are generally subject to U.S. tax on income from U.S. sources, but no withholding under section 1441 or 1442 is required on income that is, or is deemed to be, effectively connected and is includible in the beneficial owner's gross income. The withholding agent can rely on a properly completed form. Effectively connected income is reported on your annual U.S. income tax return.
Form W-8ECI is one of the Forms W-8. The form itself points to W-8BEN or W-8BEN-E for a beneficial owner solely claiming foreign status or treaty benefits, W-8EXP for certain governments and organizations, and W-8IMY for intermediaries and certain foreign partnerships and trusts. Since the October 2021 revision the form also has line 12, used by foreign dealers in securities that transfer an interest in a publicly traded partnership.
Who needs to file W-8ECI?
You must give Form W-8ECI to the withholding agent or payer if you are a foreign person and the beneficial owner of U.S. source income that is (or is deemed to be) effectively connected with a trade or business in the United States. An entity, including a foreign partnership or foreign trust, that is engaged in a U.S. trade or business can submit it on behalf of its owners, partners or beneficiaries. You must also provide it if you are a foreign dealer in securities claiming the section 1446(f) exception on line 12, or if you sell a life insurance contract and the income is effectively connected, when giving it to the section 6050Y(b) issuer.
Do not use this form if you are:
- a nonresident alien individual claiming exemption on personal services compensation (use Form 8233 or Form W-4);
- claiming a reduced treaty rate on income that is not effectively connected (use Form W-8BEN or W-8BEN-E);
- a foreign government, international organization, foreign central bank of issue, foreign tax-exempt organization or foreign private foundation claiming section 115(2), 501(c), 892, 895 or 1443(b) (use Form W-8EXP), unless you received effectively connected income;
- an intermediary, or a withholding foreign partnership or trust (use Form W-8IMY);
- a foreign person receiving proceeds from a U.S. real property interest disposition (see Form 8288-B).
An agent or representative may sign for the beneficial owner and must certify the legal capacity to sign.
When to file W-8ECI
Give Form W-8ECI to the withholding agent or payer before income is paid, credited or allocated to you. If you do not provide it when requested, the withholding agent may have to withhold at the 30% statutory rate or at the backup withholding rate.
A Form W-8ECI generally stays valid from the date you sign it until the last day of the third succeeding calendar year. For example, a form signed on September 30, 2020 generally remains valid through December 31, 2023, unless a change in circumstances makes information on it incorrect.
If a change in circumstances makes any information incorrect, notify the withholding agent or payer within 30 days and submit a new Form W-8ECI or other appropriate form. For example, if any part of the income is no longer effectively connected, the form is no longer valid. The 30-day rule does not apply if you will not receive a future payment from the withholding agent that would require an updated Form W-8.
Documents you need
- A statement attached to the form, if the space on line 11 is not enough to specify each item of income that is effectively connected with a U.S. trade or business.
- A copy of your election under section 871(d) or 882(d), if you give the form to a partnership as a partner who made that election.
- A statement indicating your intent to make the election effective for the current tax year, if you are a partner who has not yet made the section 871(d) or 882(d) election but intend to.
- A power of attorney or a copy, such as Form 2848, if an agent completes the form under a duly authorized power of attorney; this does not apply to a partnership or flow-through entity submitting for its partners or owners.
- A statement explaining why you are not required to provide an FTIN, if you want to give an explanation beyond checking the box on line 8b; it may also be written in the margins.
How to fill out W-8ECI
Identify the beneficial owner
On line 1 enter the name of the individual or organization that is the beneficial owner. For a disregarded entity with a single foreign owner, the owner completes and signs the form. Line 2: enter the country of incorporation or organization; an individual gives the country of residence for tax purposes.
Name any disregarded entity
On line 3, enter the name of the disregarded entity receiving the payments, if applicable. The line is not required, but it can help the withholding agent.
Check the type of entity
On line 4, check the box that fits, such as Partnership, Corporation, Individual, Estate, Grantor trust or Tax-exempt organization. Foreign governments check either Foreign Government - Integral Part or Foreign Government - Controlled Entity.
Enter your permanent residence address
On line 5, give the street address, city or town, state or province, postal code and country where you claim to be a resident for income tax. Do not use a P.O. box or in-care-of address.
Enter your U.S. business address
On line 6, enter your business address in the United States with city, state and ZIP code. Do not use a P.O. box or in-care-of address.
Provide your U.S. taxpayer identification number
On line 7, enter your SSN, ITIN or EIN and check the box for the type; the form is not valid without a TIN. A disregarded entity enters the TIN of its foreign single owner.
Give your foreign tax identifying number
On line 8a, enter the FTIN issued by your country of tax residence if you are an account holder with a financial account at a U.S. office of a financial institution. Check line 8b if you are not legally required to obtain an FTIN.
Add reference number and birth date
On line 9, enter any referencing information the withholding agent finds useful, such as an account name or number. On line 10, account holders who are individuals enter the date of birth as MM-DD-YYYY.
Specify the effectively connected income
On line 11, list each item of income that is, or is expected to be, received from the payer and is effectively connected with a U.S. trade or business. Attach a statement if you need more room; partners with a section 871(d) or 882(d) election attach a copy.
Complete line 12 if you are a dealer
Check line 12 only if you are a foreign dealer in securities (section 475(c)(1)) transferring a publicly traded partnership interest and claiming the exception under Regulations section 1.1446(f)-4(b)(6), with the gain effectively connected without regard to section 864(c)(8).
Sign, print name and date
In Part II, the beneficial owner or an authorized individual signs, prints the name and enters the date as MM-DD-YYYY. An agent or representative must check the box certifying the capacity to sign for the person on line 1.
Review and download the completed PDF
Check every line against your records, then download or print the completed PDF from FillingPDF and give it to the withholding agent or payer as described under How to submit.
How to submit W-8ECI
Form W-8ECI is given to the withholding agent or payer that requests it; it is not filed with the IRS. The form states "Do not send to the IRS."
- To the requester: give the signed form to the person who asks for it, generally the person from whom you receive the payment, who credits your account, or a partnership that allocates income to you. A separate Form W-8ECI must generally be given to each withholding agent.
- To a partnership: if you submit it to a partnership, the effectively connected income is subject to withholding under section 1446(a). If a nominee holds your partnership interest, you, not the nominee, must submit the form to the partnership or nominee that is the withholding agent, except as otherwise provided.
- Electronic signature: a withholding agent can allow you to provide the form with an electronic signature. Typing your name into the signature line is not an electronic signature.
- Attachments: attach a statement to line 11 if you need more space, and attach a power of attorney when an agent signs under one.
The IRS asks you to send comments about the form to its Tax Forms and Publications office, not the form itself. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Sending Form W-8ECI to the IRS; the form says to give it to the withholding agent or payer, and the instructions repeat this.
- Leaving line 7 without a U.S. taxpayer identification number; the instructions say a TIN is required for the form to be valid.
- Entering a P.O. box or in-care-of address on line 5 or line 6; both lines prohibit them.
- Using this form to claim a reduced treaty rate on income that is not effectively connected, when the instructions direct you to Form W-8BEN or W-8BEN-E.
- Filling in details about a disregarded entity anywhere other than line 3 or line 9, instead of using the foreign single owner's information.
- Not submitting a new form within 30 days after a change in circumstances, such as income that stops being effectively connected.
- Signing without the capacity to sign: an agent must check the certification box and attach a power of attorney when signing under one.
- Typing a name on the signature line and treating it as an electronic signature, which the instructions say it is not.
Frequently asked questions
What is Form W-8ECI used for?
Form W-8ECI is the IRS certificate a foreign person gives to a withholding agent or payer to claim that U.S. source income is effectively connected with a U.S. trade or business, so that no withholding under section 1441 or 1442 is required on it. You report that income on your annual U.S. income tax return.
Do I send Form W-8ECI to the IRS?
No. The form says "Give this form to the withholding agent or payer. Do not send to the IRS." Give it to whoever requests it, generally the person paying you or the partnership allocating income to you, before the payment is made, credited or allocated.
How long is a W-8ECI valid?
It generally remains valid from the date you sign it until the last day of the third succeeding calendar year. A form signed on September 30, 2020 generally stays valid through December 31, 2023, unless a change in circumstances makes information on it incorrect.
What is the difference between W-8ECI and W-8BEN?
Use W-8ECI when the income is effectively connected with a U.S. trade or business. Use W-8BEN (individuals) or W-8BEN-E (entities) when you only claim foreign status or treaty benefits. If you receive both kinds of income from one withholding agent, provide each form for its own income.
Do I need a U.S. taxpayer identification number to complete W-8ECI?
Yes. Line 7 requires an SSN, ITIN or EIN, and the instructions say you must provide a TIN for the form to be valid. A disregarded entity enters the TIN of its foreign single owner.
What is line 12 on Form W-8ECI?
Line 12 is for a foreign transferor that is a dealer in securities claiming an exception from section 1446(f) withholding on the transfer of a publicly traded partnership interest. Checking it certifies that any gain is effectively connected without regard to section 864(c)(8).
Can someone sign Form W-8ECI for me?
Yes, an individual authorized to sign for the beneficial owner can sign, and an agent must check the box certifying the legal capacity to sign for the person on line 1. An agent acting under a power of attorney must attach it; Form 2848 can be used.
Can I fill out Form W-8ECI online?
Yes. You can fill out the fillable PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not send the form to anyone; you give it to the withholding agent or payer yourself.
Ready to fill out W-8ECI?
Fill out W-8ECI now