
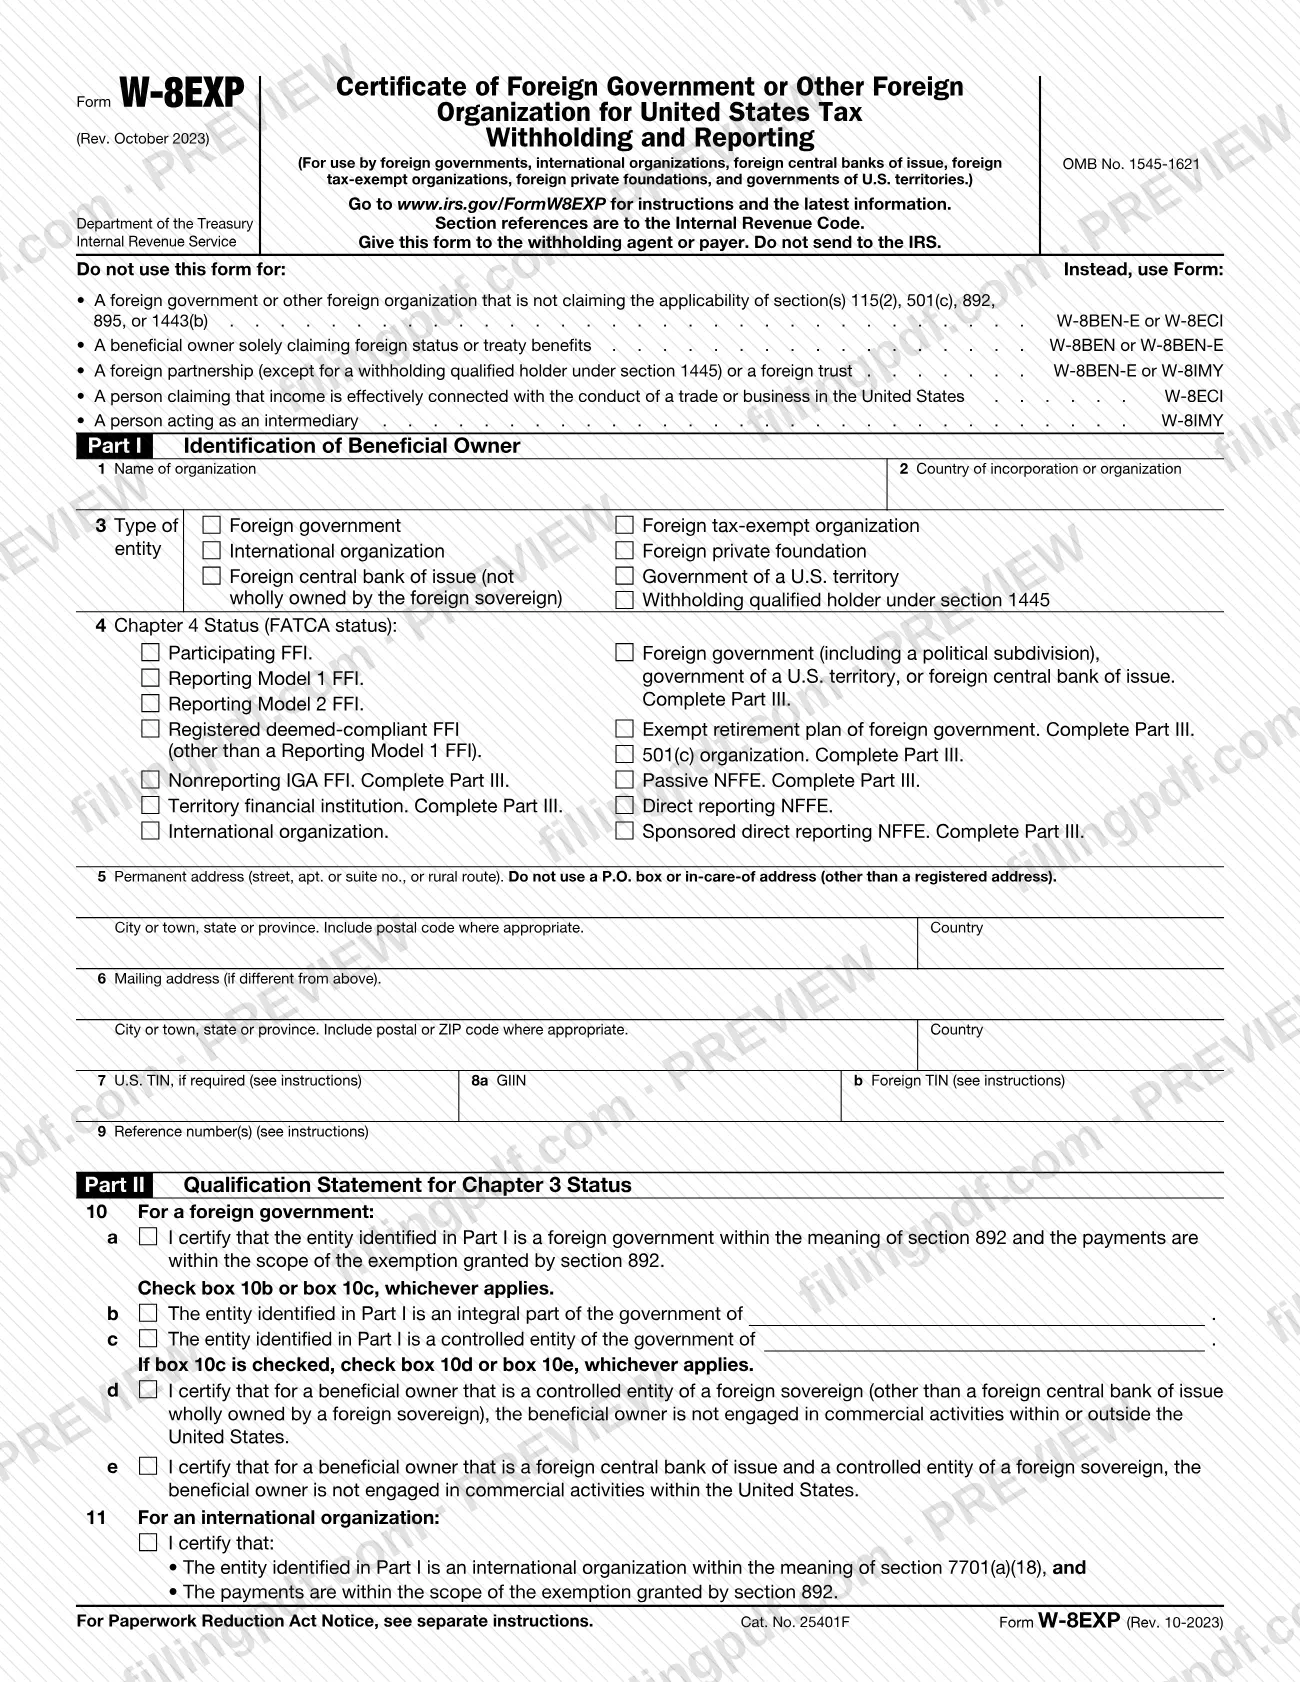
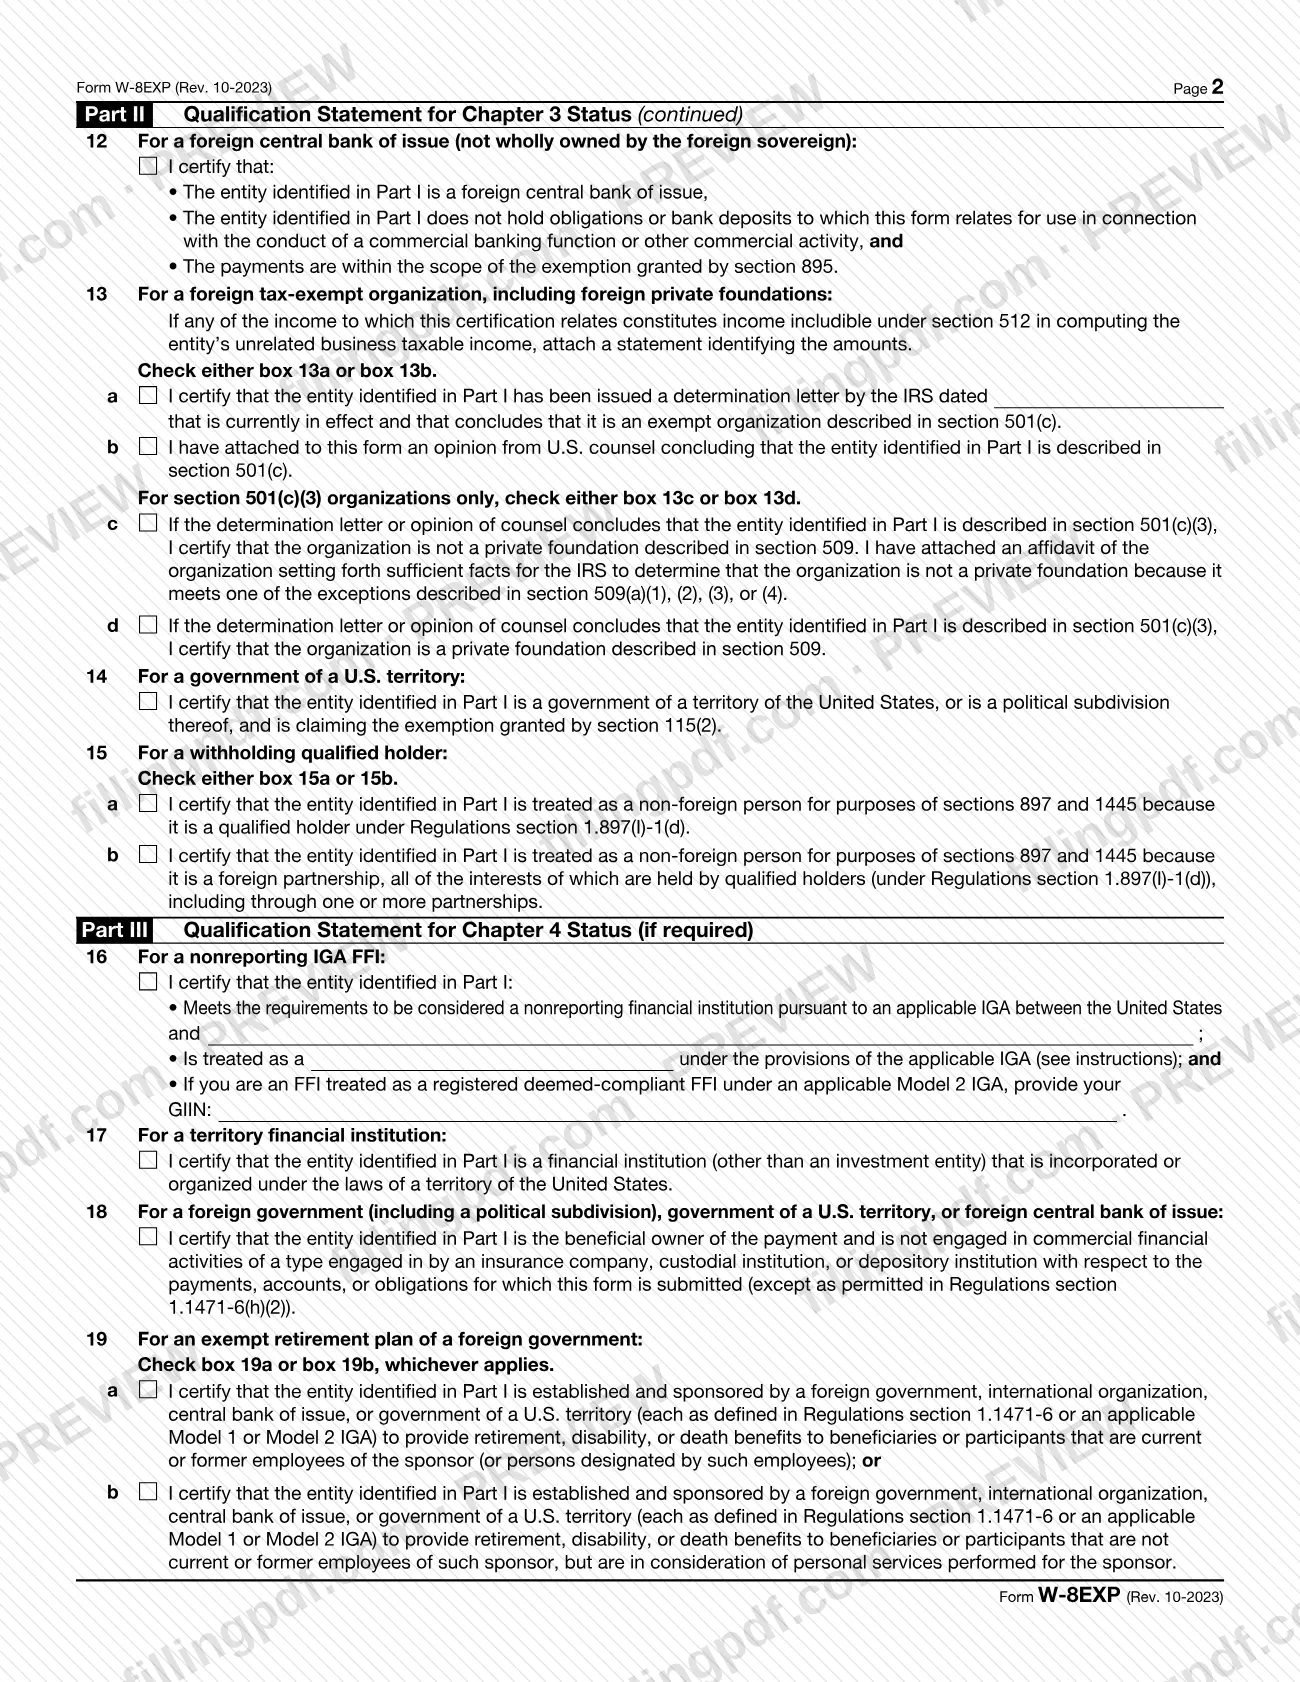
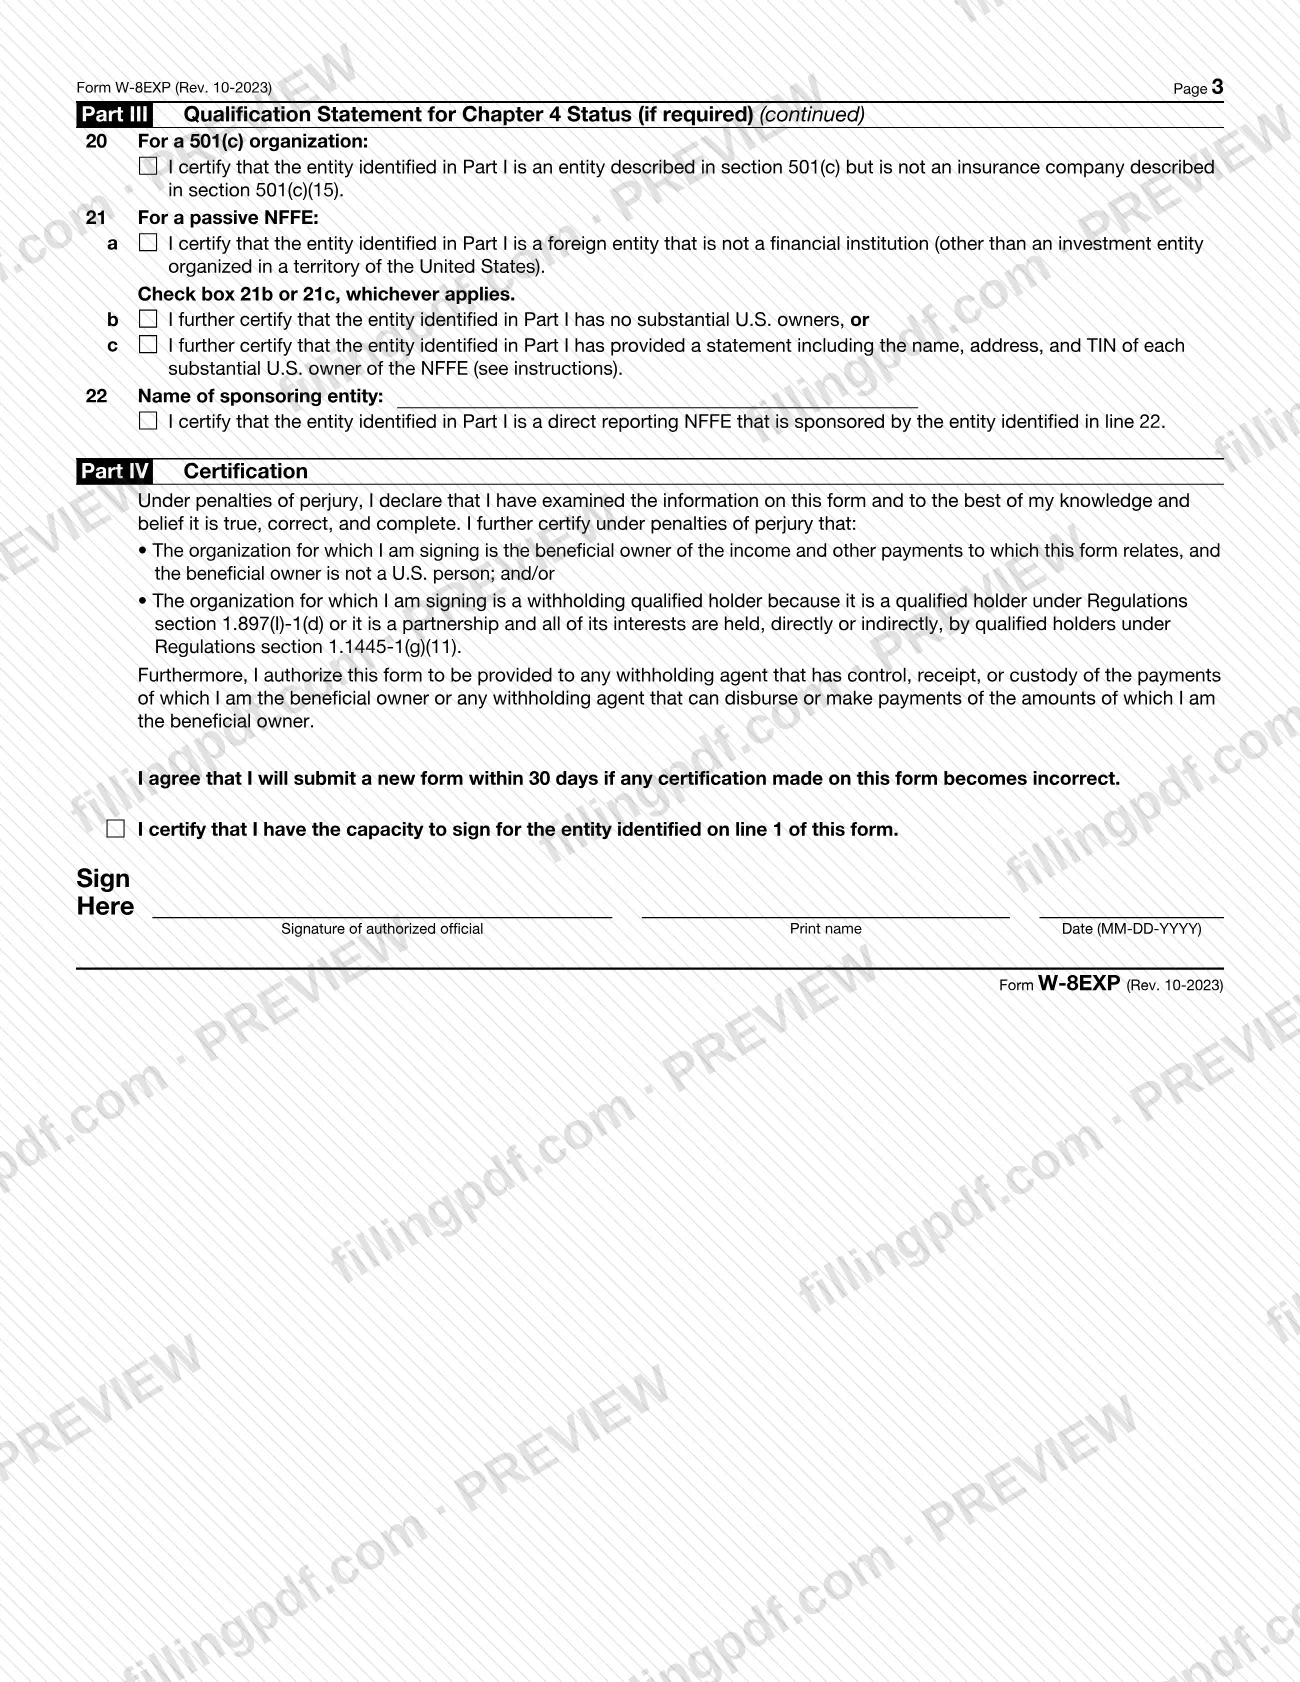
Form W-8EXP is the Internal Revenue Service (IRS) certificate that a foreign government, international organization, foreign central bank of issue, foreign tax-exempt organization, foreign private foundation or government of a U.S. territory gives to a withholding agent or payer. It establishes that you are not a U.S. person and supports a claim to exemption from, or a reduced rate of, U.S. withholding. On this page you can fill out the form online on FillingPDF and download or print the completed PDF; the form and its instructions are published by the IRS at www.irs.gov/FormW8EXP.
Last updated
What is W-8EXP?
Form W-8EXP is the IRS certificate that a foreign government or other foreign organization gives a withholding agent to establish that it is not a U.S. person and to claim exemption from, or a reduced rate of, U.S. tax withholding.
The full title is Certificate of Foreign Government or Other Foreign Organization for United States Tax Withholding and Reporting, and it is issued by the Internal Revenue Service (IRS) under OMB No. 1545-1621. The form has four parts: Part I identifies the beneficial owner, including its entity type and chapter 4 (FATCA) status; Part II is the qualification statement for chapter 3 status; Part III is the qualification statement for chapter 4 status, completed only if required; and Part IV is the certification signed by an authorized official.
Chapter 3 covers withholding on U.S.-source income of foreign persons, and chapter 4 covers withholding to enforce reporting on certain foreign accounts. The form can be used to claim exemption under section 892 (foreign governments and international organizations), section 895 (foreign central banks of issue), section 501(c) (foreign tax-exempt organizations) and section 115(2) (governments of U.S. territories), and to claim the 4% rate that applies to foreign private foundations under section 1443(b). A withholding qualified holder under section 1445 can also use it.
The form is not filed with the IRS. The printed form says to give it to the withholding agent or payer. For other situations the form points to different forms: W-8BEN-E or W-8ECI, W-8BEN, W-8IMY.
Who needs to file W-8EXP?
You give Form W-8EXP to a withholding agent or payer if you are one of these:
- A foreign government, international organization, foreign central bank of issue, foreign tax-exempt organization, foreign private foundation or government of a U.S. territory that receives an amount subject to withholding under sections 1441 through 1443, or a withholdable payment subject to chapter 4, or that holds an account with a foreign financial institution (FFI) requesting the form.
- A withholding qualified holder claiming an exemption to withholding under section 1445.
- A foreign tax-exempt organization or a qualified holder claiming a reduction of effectively connected taxable income subject to withholding under section 1446(a), in the cases the instructions describe.
Do not use Form W-8EXP in these situations; the form and instructions name the replacement:
- A foreign government or organization not claiming section 115(2), 501(c), 892, 895 or 1443(b): use Form W-8BEN-E or W-8ECI.
- A beneficial owner solely claiming foreign status or treaty benefits: use Form W-8BEN or W-8BEN-E.
- A foreign partnership (other than a withholding qualified holder under section 1445) or a foreign trust: use Form W-8BEN-E, W-8ECI or W-8IMY.
- A person receiving income effectively connected with a U.S. trade or business: use Form W-8ECI.
- An intermediary: use Form W-8IMY.
An authorized official, officer or agent signs for the organization and certifies the capacity to do so.
When to file W-8EXP
Give Form W-8EXP to the person requesting it before the payment is made, credited or allocated to you or your account. If you qualify for an exemption but do not provide the form, the withholding agent may have to withhold tax at the highest applicable rate.
Generally the form stays in effect indefinitely until a change of circumstances makes information on it incorrect. In some cases it is valid only from the date it is signed to the last day of the third succeeding calendar year; the instructions give the example of a form provided on February 15, 2022 by a controlled entity of a foreign government, which would expire on December 31, 2025 for sections 1441 through 1443 purposes. Section 1445 purposes have a 2-year period.
If a change in circumstances makes any information incorrect, notify the withholding agent within 30 days and provide a new Form W-8EXP or other appropriate form. A withholding agent may require a separate form for each type of income you receive from it.
Documents you need
- A statement identifying the amounts, if any of the income covered by the form is includible under section 512 in computing the entity's unrelated business taxable income (line 13, foreign tax-exempt organizations).
- The date of the IRS determination letter (box 13a), or an attached opinion from U.S. counsel concluding the entity is described in section 501(c) (box 13b), if you are a foreign tax-exempt organization.
- For box 13c, an attached affidavit with enough facts for the IRS to determine the section 501(c)(3) organization is not a private foundation under section 509(a)(1), (2), (3) or (4).
- A statement with the name, address and TIN of each substantial U.S. owner, if you are a passive NFFE with substantial U.S. owners (line 21c).
- An explanation of why you have no foreign TIN, if you document a financial account and leave line 8b blank, unless an exception applies; it may be written on line 8b, in the margins or on an attached statement.
- The class of entity described in Annex II of the IGA, given to the withholding agent, if you are a nonreporting IGA FFI (line 16).
How to fill out W-8EXP
Complete the worksheet first
Before Part I, answer the Worksheet for Foreign Governments, International Organizations, and Foreign Central Banks of Issue in the instructions to see whether your income is exempt under section 892 or 895. Use the results for line 3 and Part II, and keep the worksheet; do not give it to the withholding agent.
Enter name and country
Line 1: the full name of the organization. Line 2: the country under whose laws it was created, incorporated, organized or governed.
Check your entity type
Line 3: check the one box that applies, for example foreign government, international organization, foreign central bank of issue, foreign tax-exempt organization or foreign private foundation. A wholly owned central bank checks Foreign government.
Check your chapter 4 status
Line 4: check the one box that matches your FATCA status. Some statuses direct you to complete Part III.
Enter permanent and mailing addresses
Line 5: the permanent address, with no P.O. box or in-care-of address (other than a registered address). Line 6: a mailing address only if it differs from line 5.
Enter taxpayer identification numbers
Line 7: your U.S. TIN (an EIN) if required. Line 8a: your GIIN if registered with the IRS. Line 8b: your foreign TIN if required. Line 9: any reference number, such as an account number.
Complete the Part II statement
Check the boxes for your status: line 10 (foreign government), 11 (international organization), 12 (foreign central bank of issue), 13 (foreign tax-exempt organization), 14 (U.S. territory government) or 15 (withholding qualified holder). On 10b or 10c, enter the foreign sovereign's country.
Complete Part III if required
Use lines 16 to 22 to certify the chapter 4 status you checked on line 4. A passive NFFE checks box 21b or 21c; a sponsored direct reporting NFFE enters the sponsoring entity's name on line 22.
Prepare any attached statements
Prepare the section 512 statement, affidavit, opinion of counsel or substantial U.S. owner statement if your boxes require them, and keep them with the form.
Sign and date Part IV
An authorized official signs, prints the name and enters the date in MM-DD-YYYY format, certifying the capacity to sign for the entity named on line 1.
Review and download the PDF
Check that each line matches your worksheet and status, then download or print the completed PDF from FillingPDF and give it to the withholding agent as described under How to submit.
How to submit W-8EXP
Form W-8EXP is not sent to the IRS. You give it directly to the withholding agent or payer that requests it from you.
- To the withholding agent or payer: this is generally the person from whom you receive the payment (including the transferee of a U.S. real property interest), who credits your account, or a partnership that allocates income to you. Generally a separate Form W-8EXP must be given to each withholding agent.
- To an FFI: if you hold an account with a foreign financial institution that requests the form, give it to the FFI to document your chapter 4 status.
- Electronic signature: a withholding agent may allow an electronic signature. It must show the form was electronically signed by an authorized person, for example with a time and date stamp and a statement to that effect; typing your name on the signature line is not an electronic signature.
- Keep your records: keep the worksheet from the instructions; do not give it to the withholding agent.
The IRS instructions say not to send the form to the IRS comment address in Washington, DC. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Sending Form W-8EXP to the IRS; the form says to give it to the withholding agent or payer and not to send it to the IRS.
- Using this form when you are not claiming section 115(2), 501(c), 892, 895 or 1443(b), instead of Form W-8BEN-E or W-8ECI.
- Checking more than one box on line 3; only one box applies, apart from the withholding qualified holder box used together with the box for your status.
- Giving the completed worksheet to the withholding agent; the worksheet is kept for your own records.
- Entering a P.O. box, an in-care-of address or a financial institution's address on line 5 as the permanent address.
- Skipping the chapter 4 status on line 4 or its Part III statement; the form is then not valid for chapter 4 if you receive a withholdable payment later.
- Writing "not applicable" on line 8b to explain a missing foreign TIN; the instructions allow "not legally required" instead.
- Omitting the statement of section 512 amounts when income counts toward unrelated business taxable income.
- Typing your name on the signature line and treating it as an electronic signature, or not checking the capacity-to-sign certification.
- Not providing a new form within 30 days after a change in circumstances makes a certification incorrect.
Frequently asked questions
What is Form W-8EXP used for?
Form W-8EXP is the IRS certificate a foreign government, international organization, foreign central bank of issue, foreign tax-exempt organization, foreign private foundation or U.S. territory government gives a withholding agent to show it is not a U.S. person and to claim exemption from or a reduced rate of withholding.
Do I send Form W-8EXP to the IRS?
No. The form says to give it to the withholding agent or payer and not to send it to the IRS. Generally you give a separate form to each withholding agent, before the payment is made, credited or allocated to you or your account.
How long is a W-8EXP valid?
Generally it remains in effect indefinitely until a change of circumstances makes information on it incorrect. In some cases it is valid only until the last day of the third succeeding calendar year after signing, and the instructions list other regulation-based exceptions.
What happens if my circumstances change after I give the form?
Notify the withholding agent within 30 days and provide a new Form W-8EXP or other appropriate form. By signing, the official agrees to provide a new form within 30 days, unless no future payments will be made to the organization by that agent.
What is the difference between Form W-8EXP and Form W-8BEN-E?
Form W-8EXP is for foreign governments and exempt organizations claiming section 115(2), 501(c), 892, 895 or 1443(b). Form W-8BEN-E is used instead by a foreign organization not claiming those, such as one claiming income tax treaty benefits.
Do I need a U.S. taxpayer identification number on line 7?
A U.S. TIN, meaning an EIN, is generally required if you claim an exemption or reduced withholding rate based solely on tax-exempt status under section 501(c) or private foundation status. The instructions say to use Form SS-4 to obtain an EIN.
Must I complete Part III on chapter 4 status?
Only if you are the payee of a withholdable payment or hold an account with an FFI requesting the form, and only for the chapter 4 statuses on line 4 that direct you to Part III. If you do not certify your chapter 4 status, the form is not valid for chapter 4 purposes.
Can I fill out Form W-8EXP online?
Yes. You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is independent of the IRS and does not deliver the form; you give it to your withholding agent yourself.
Ready to fill out W-8EXP?
Fill out W-8EXP now