
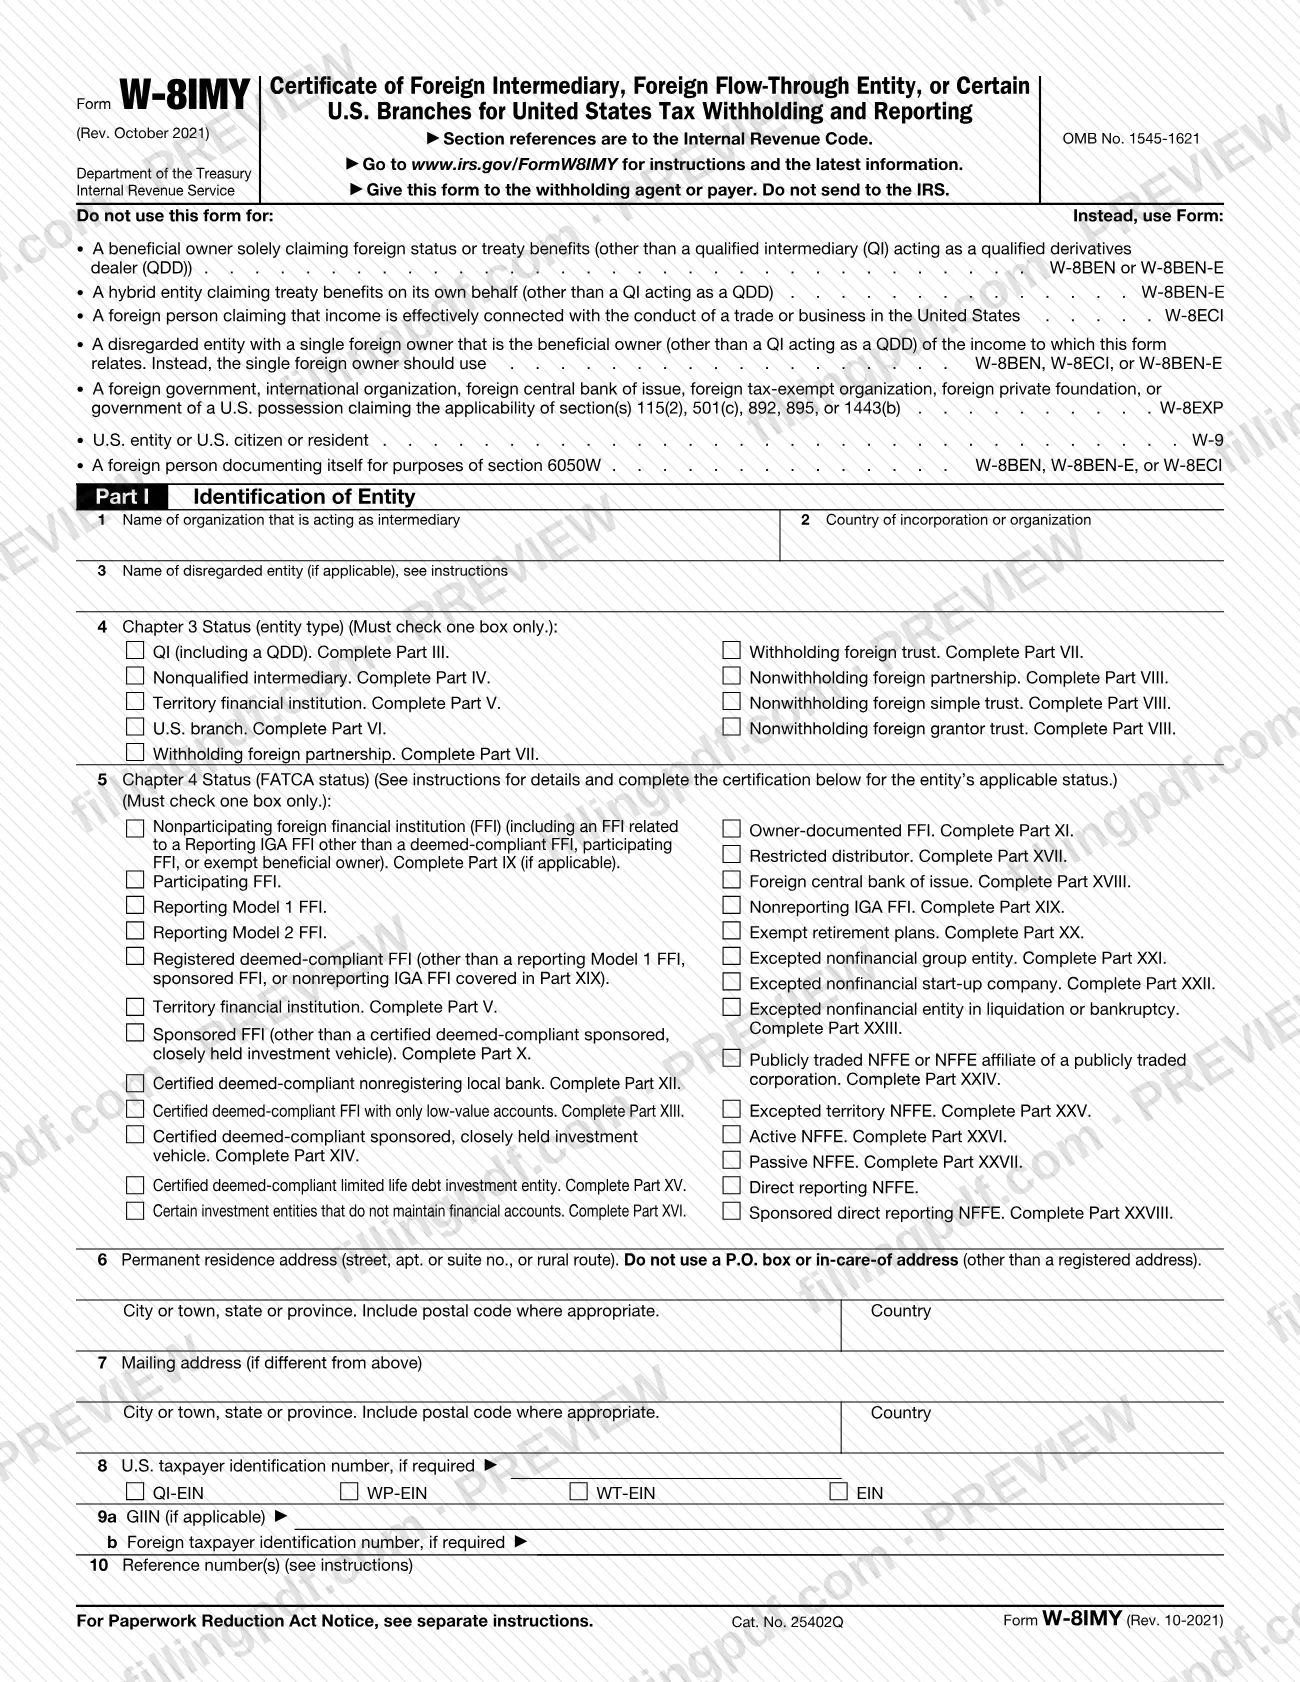
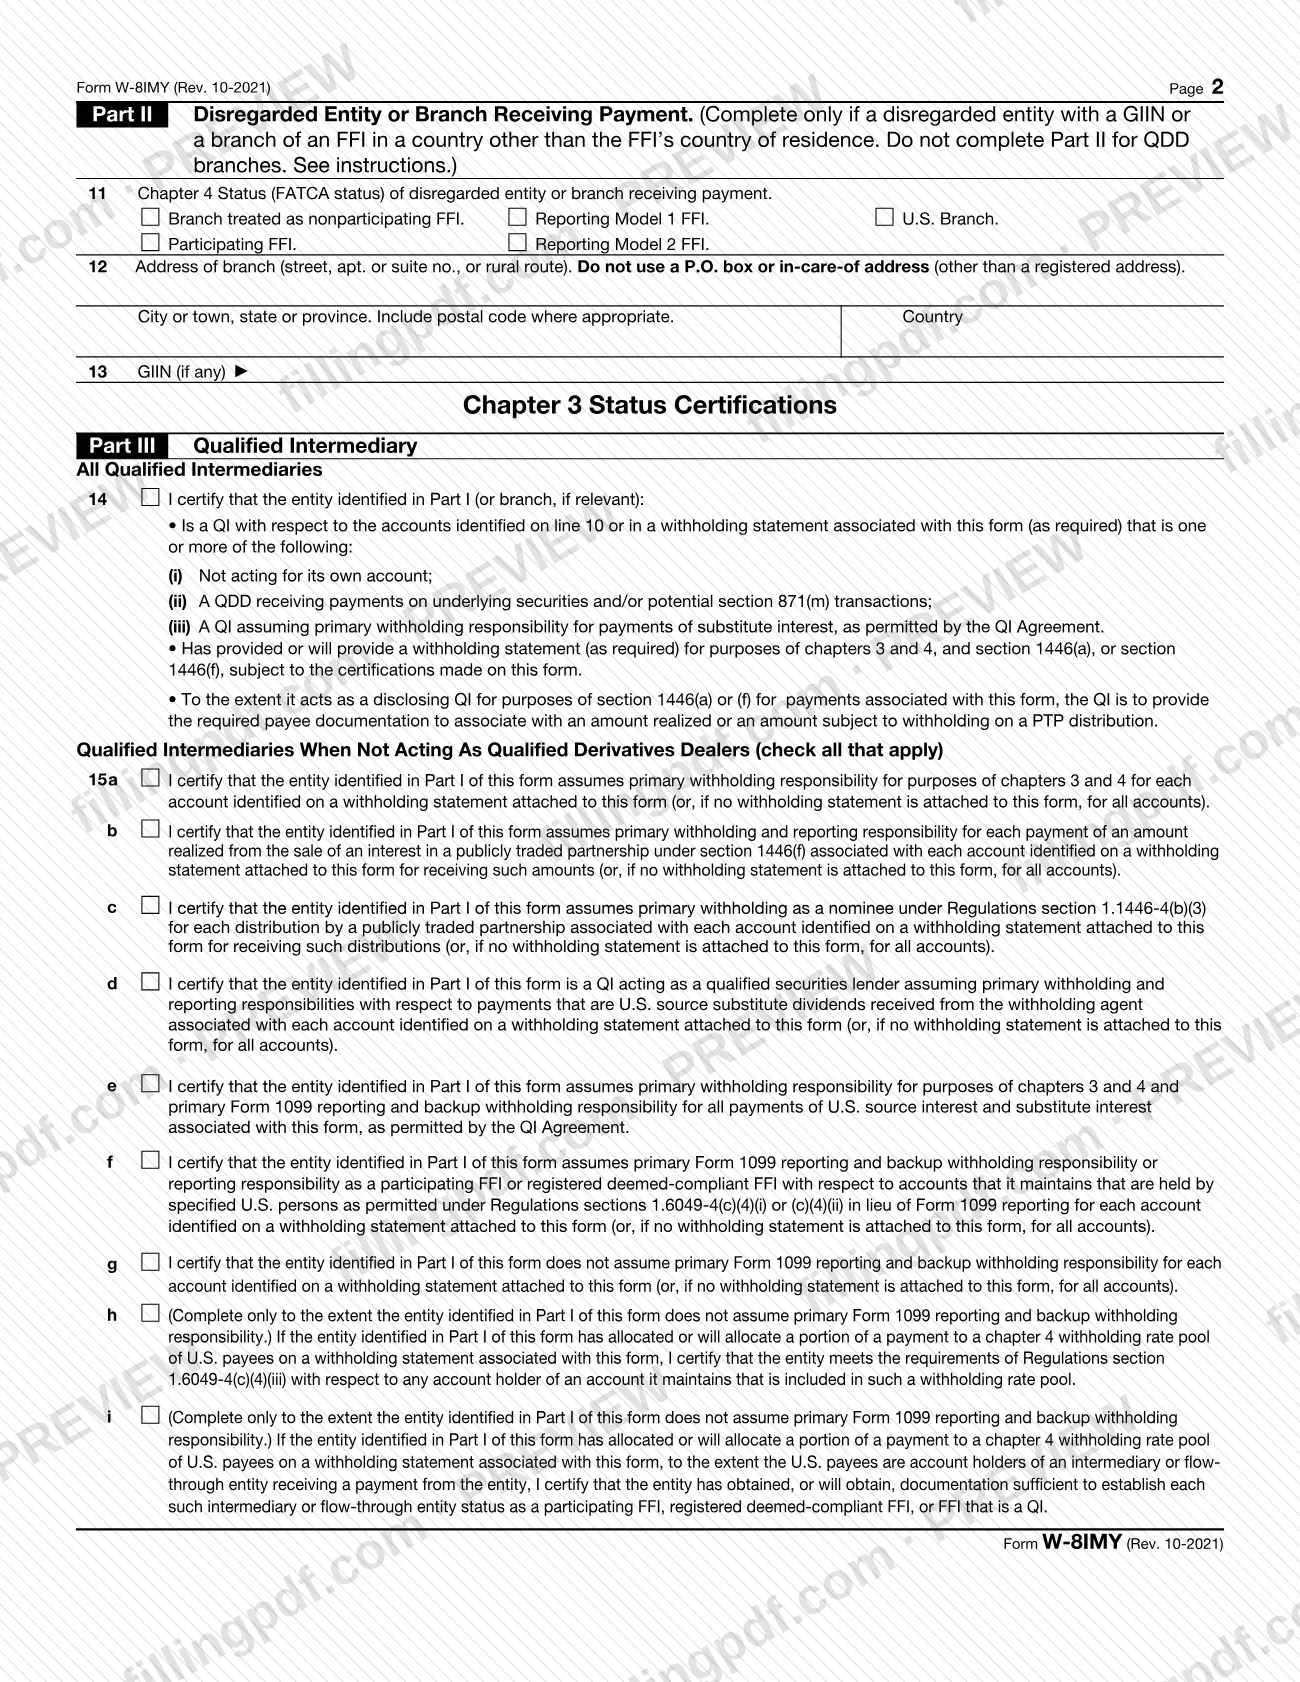
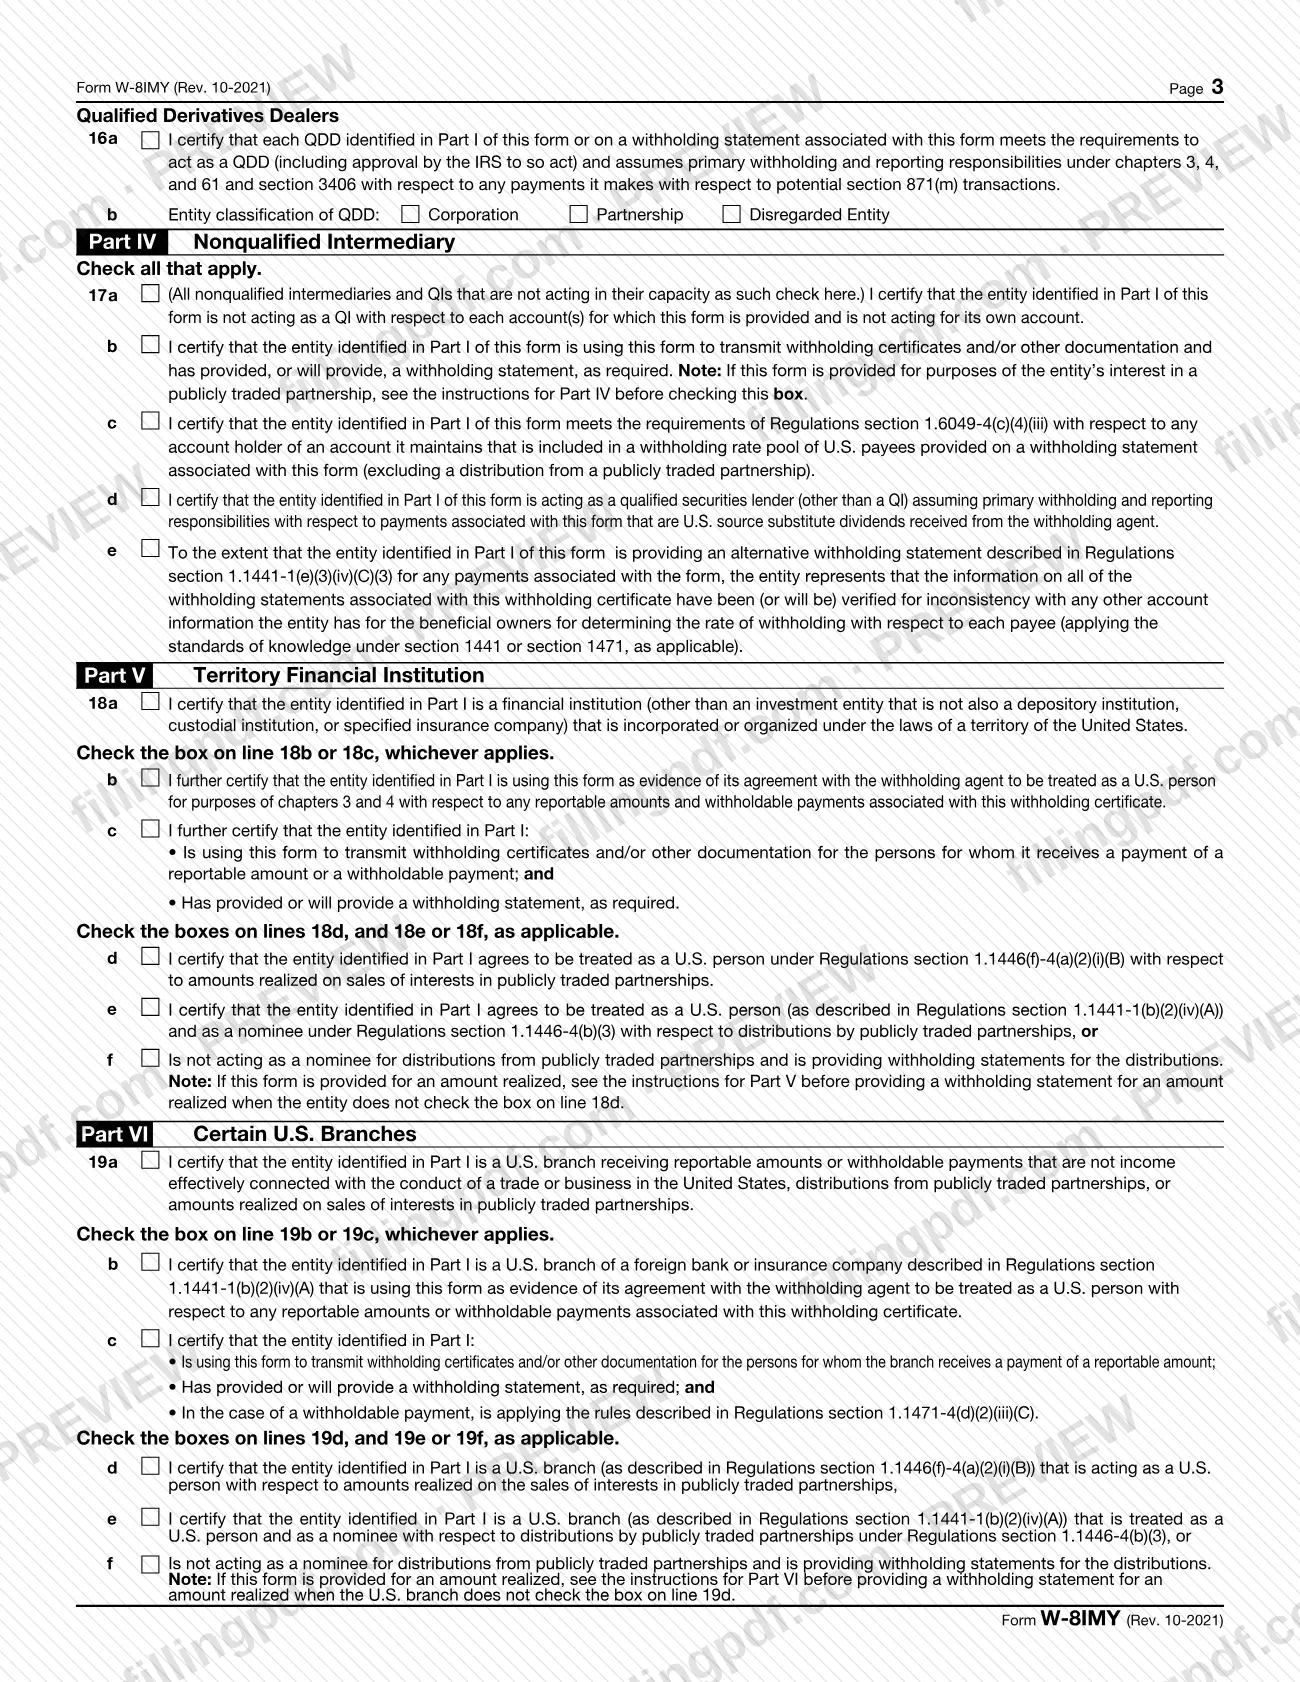
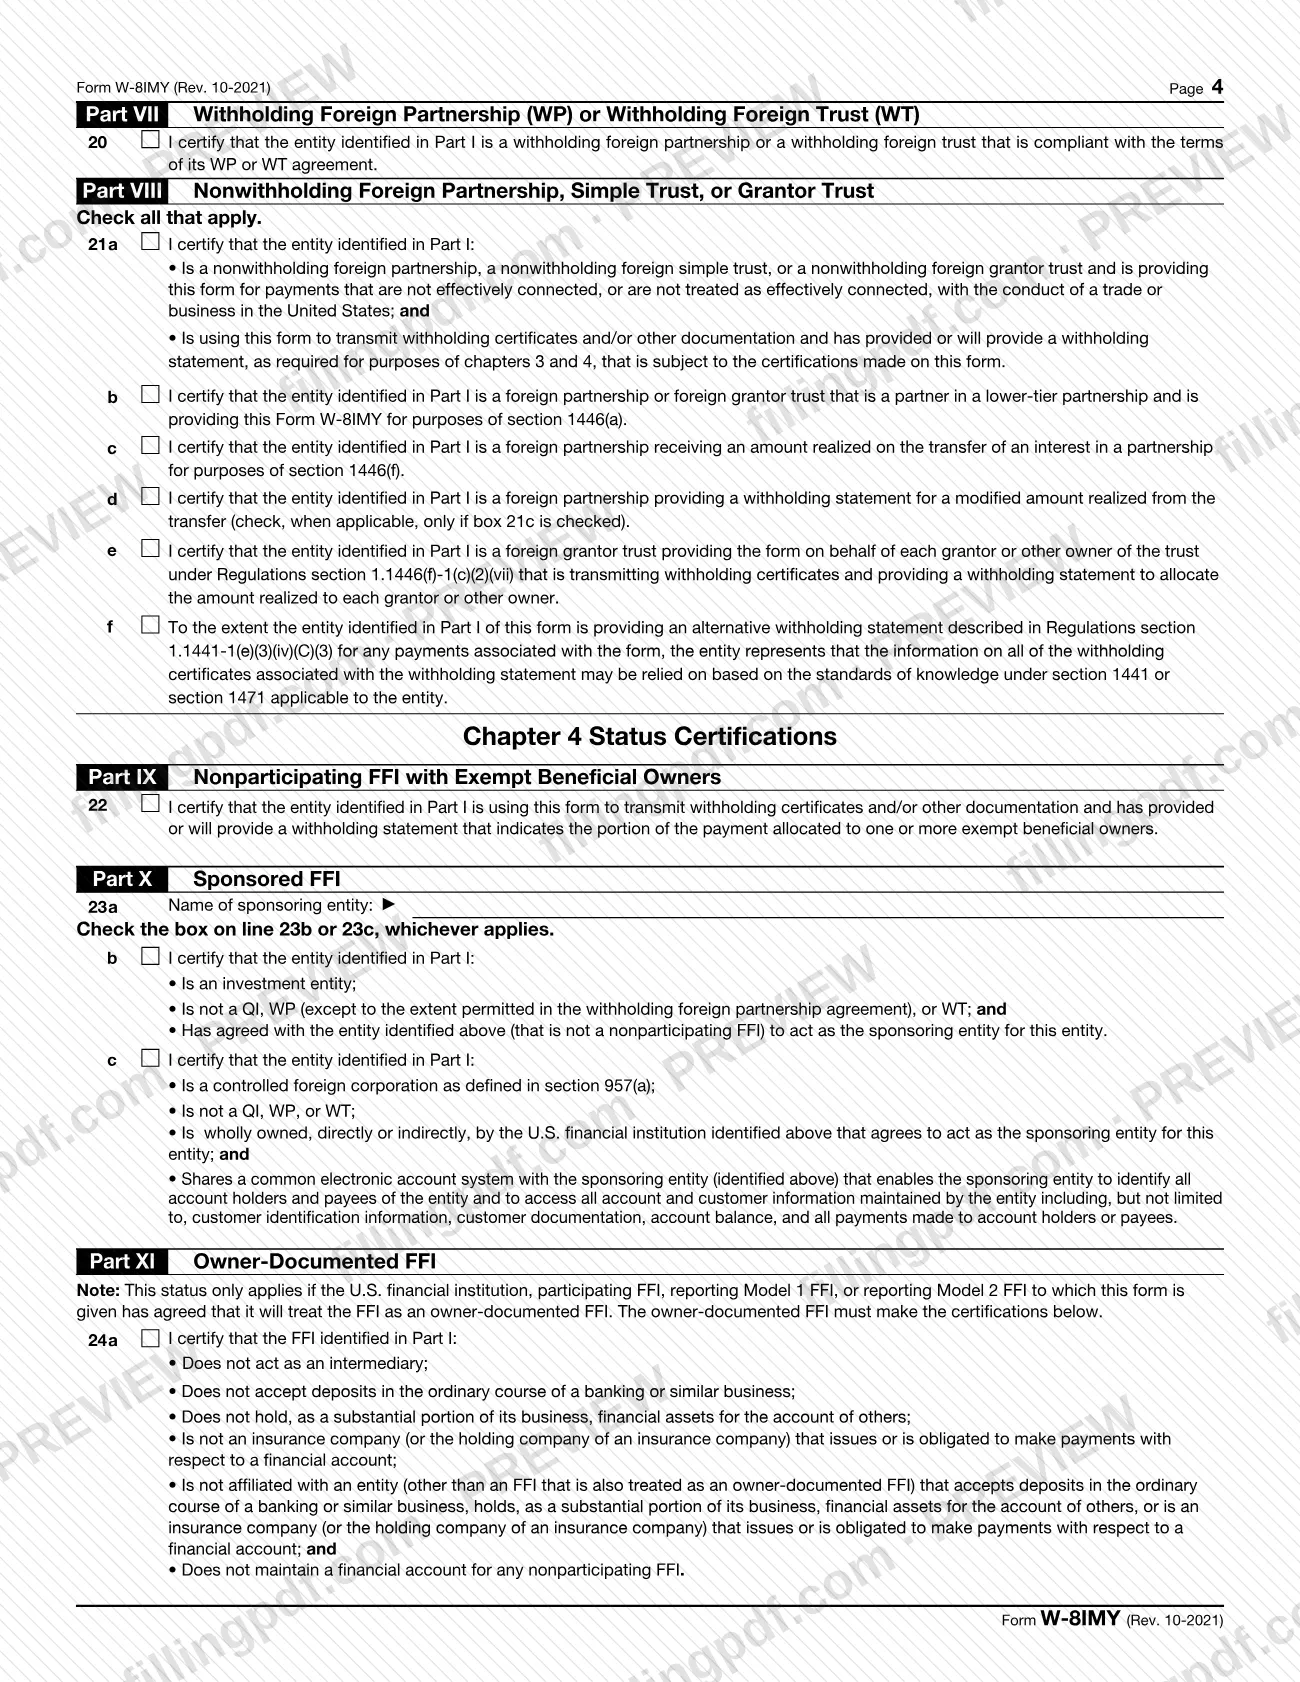
Form W-8IMY is the Internal Revenue Service (IRS) certificate that a foreign intermediary, a foreign flow-through entity or certain U.S. branches give to a withholding agent to document their status for U.S. tax withholding and reporting. Qualified intermediaries, nonqualified intermediaries, foreign partnerships and trusts, territory financial institutions and U.S. branches use it when they receive a payment for someone else. On FillingPDF you can fill out the W-8IMY online and download or print the completed PDF. The form is not sent to the IRS: you give it to the person who asks for it.
Last updated
What is W-8IMY?
Form W-8IMY, Certificate of Foreign Intermediary, Foreign Flow-Through Entity, or Certain U.S. Branches for United States Tax Withholding and Reporting, is the IRS form on which an entity states its chapter 3 and chapter 4 status so that a withholding agent knows how to treat payments it passes through.
An entity that receives a reportable amount or withholdable payment on behalf of another person, or as a flow-through entity, or that acts as a qualified derivatives dealer (QDD) or qualified securities lender (QSL), provides it. By entering its name on line 1, the entity represents that it is not the beneficial owner of the amounts paid to it, with limited exceptions described in the IRS instructions, such as a QDD or QSL acting in that capacity.
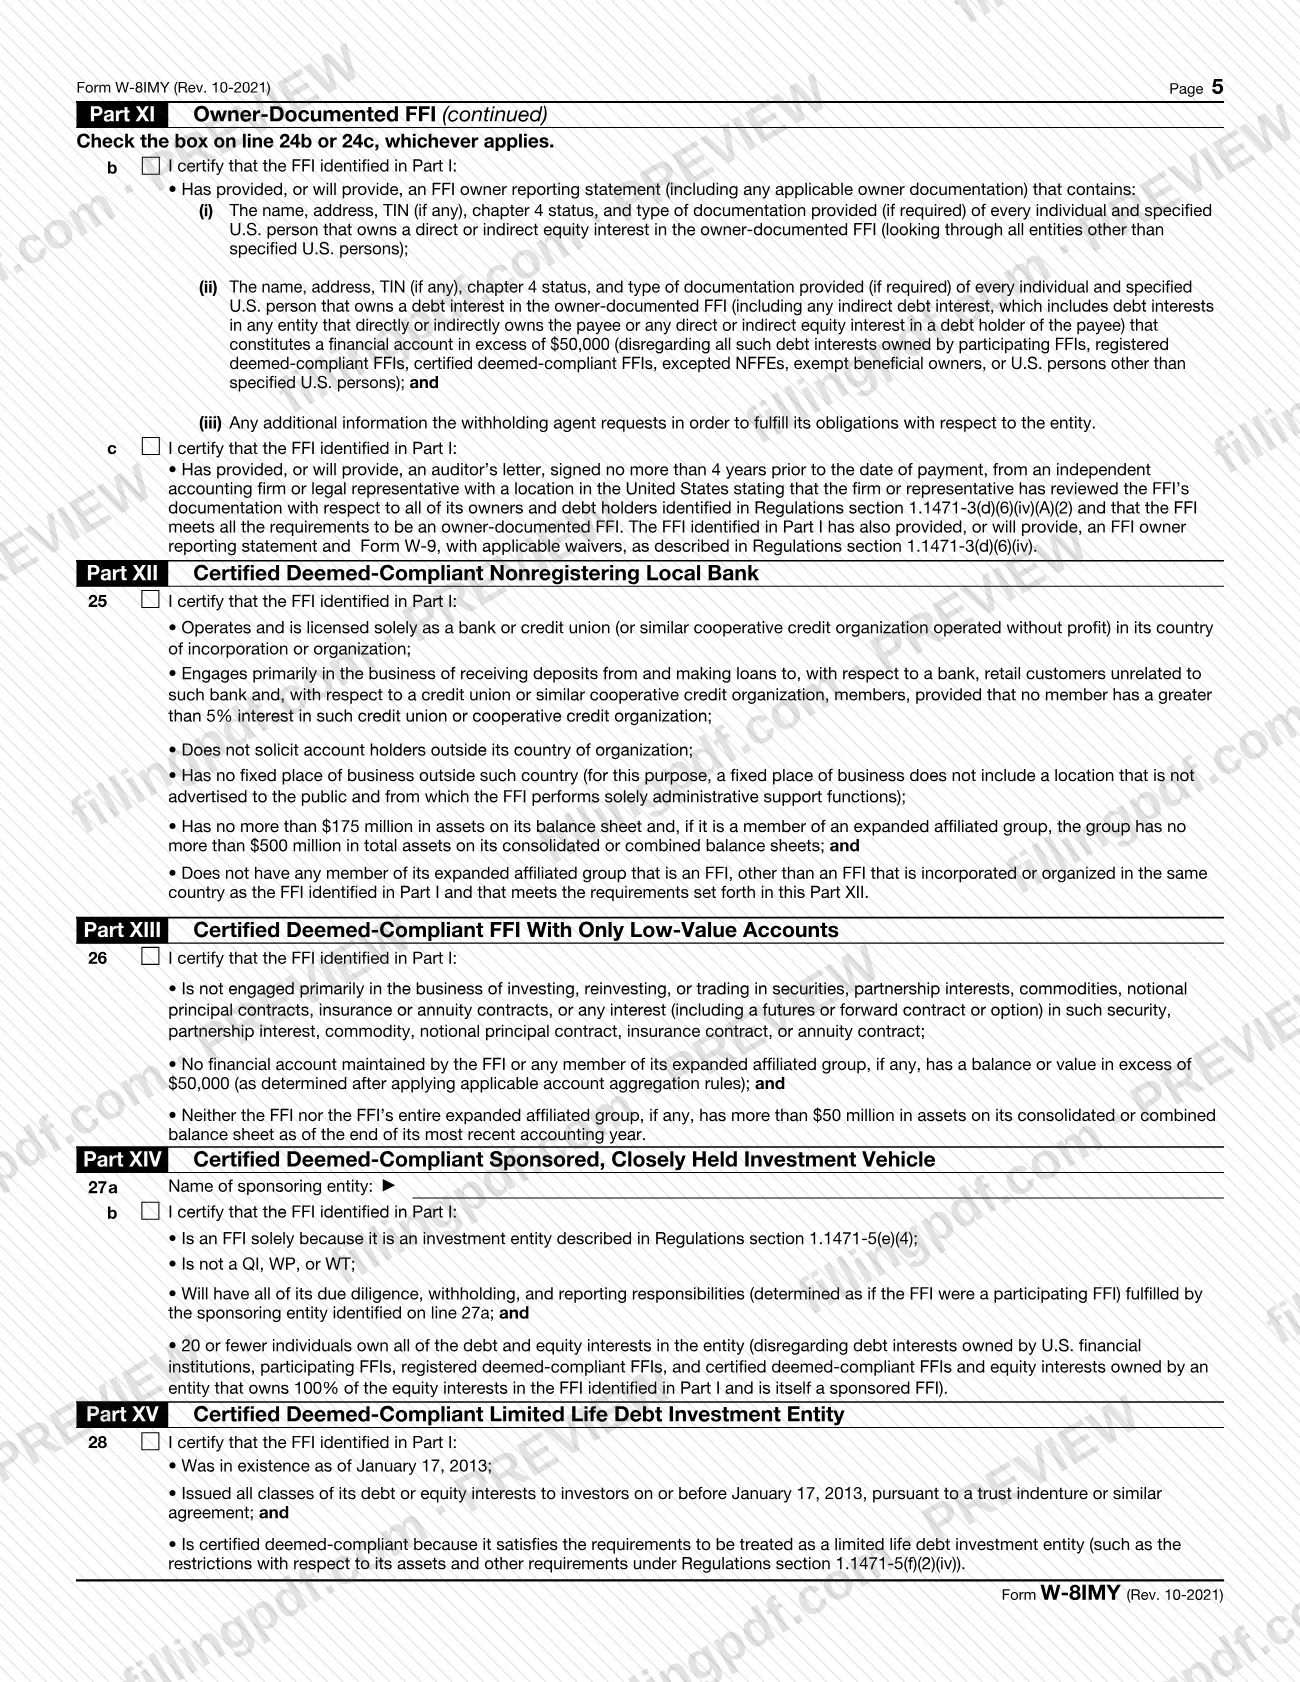
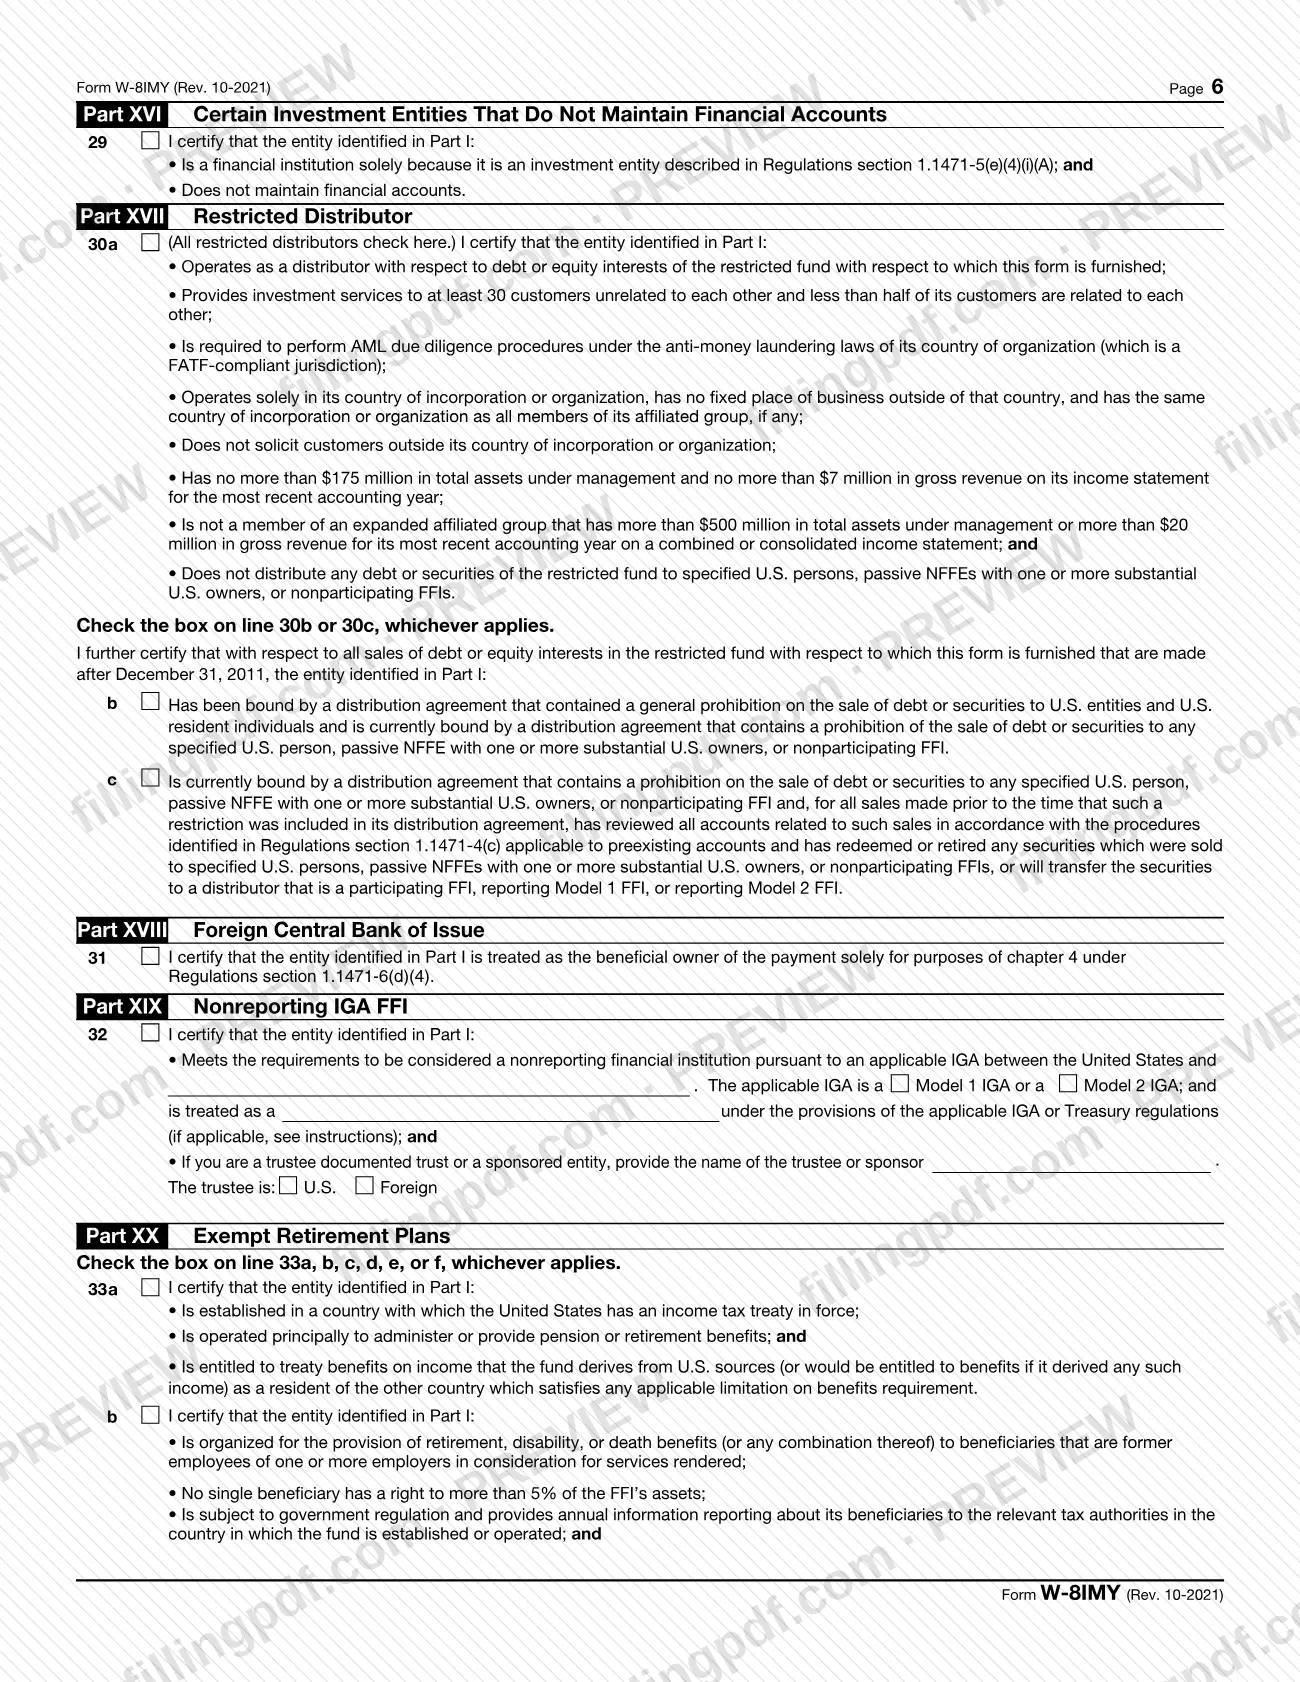
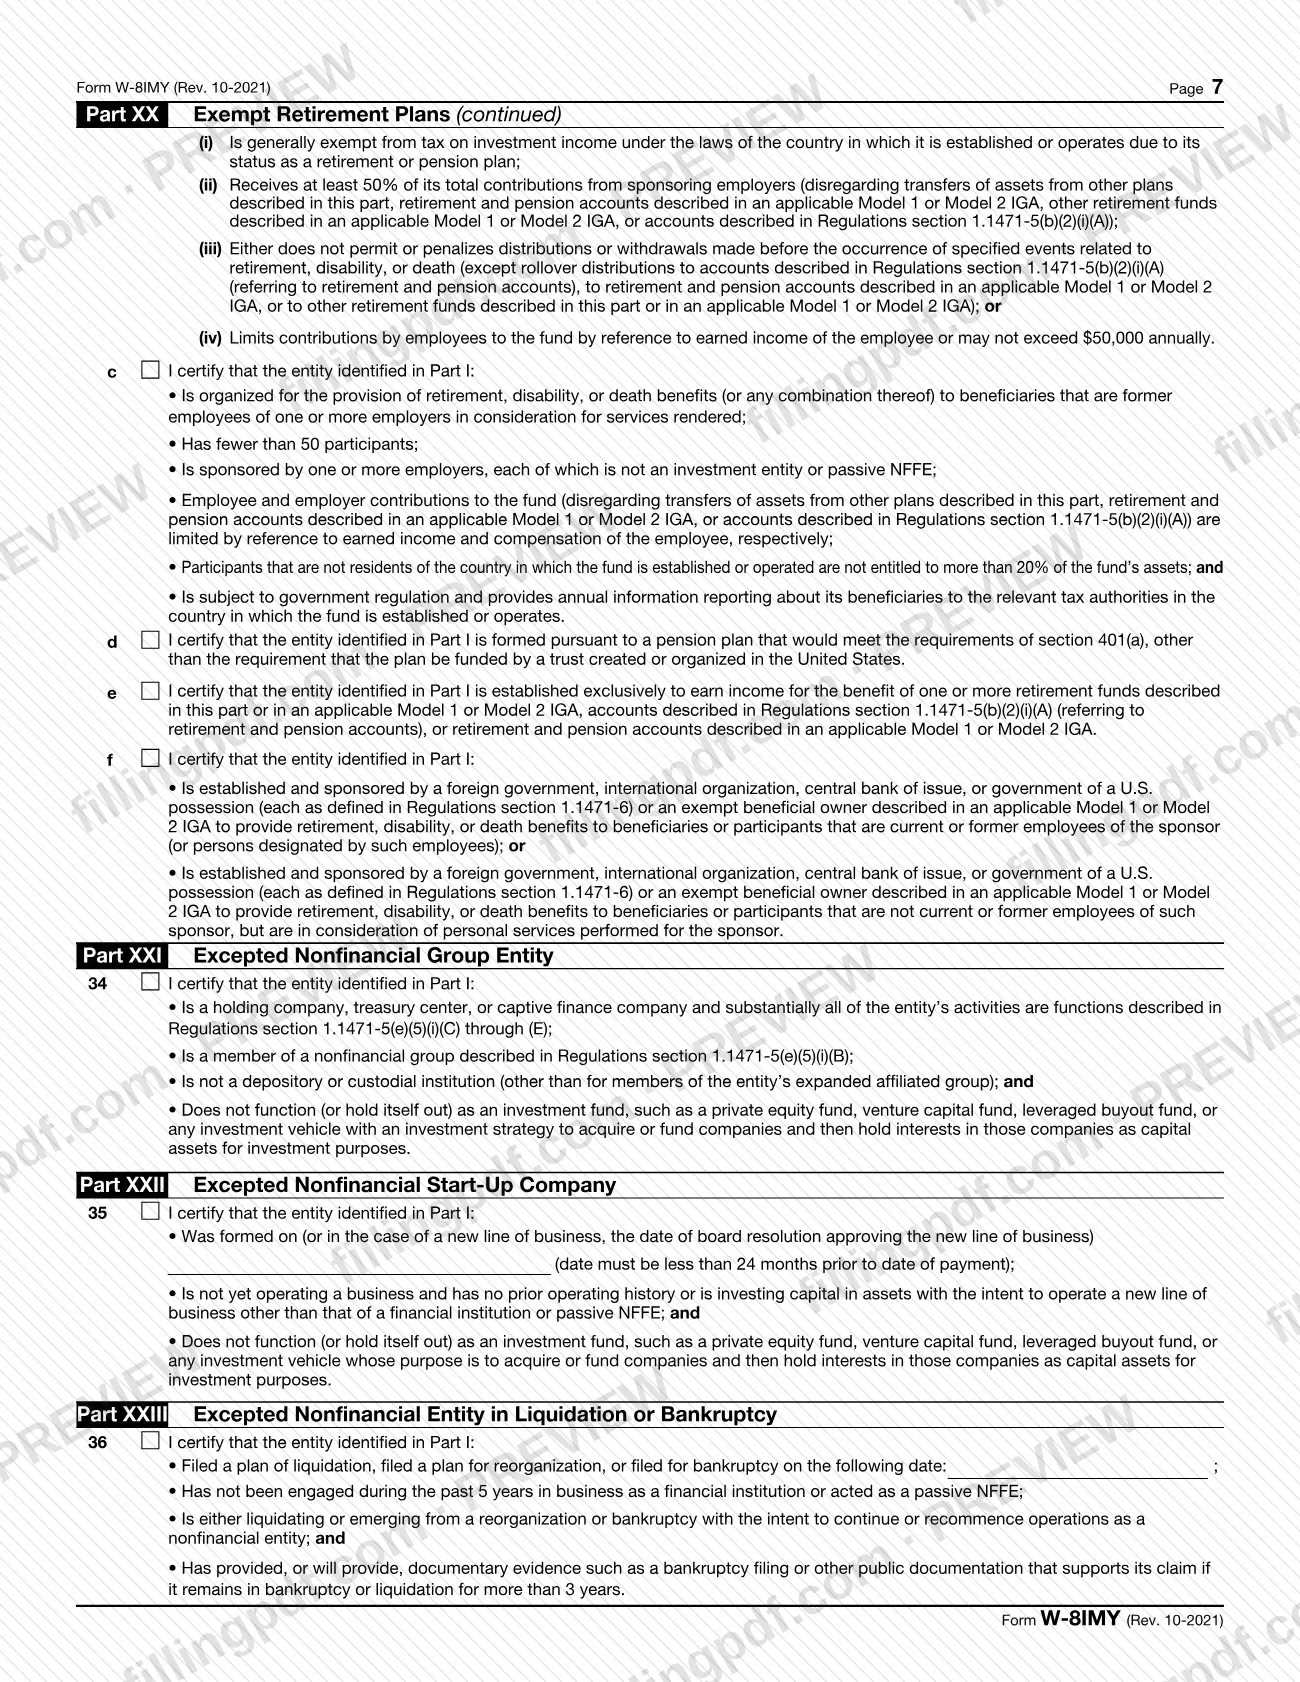
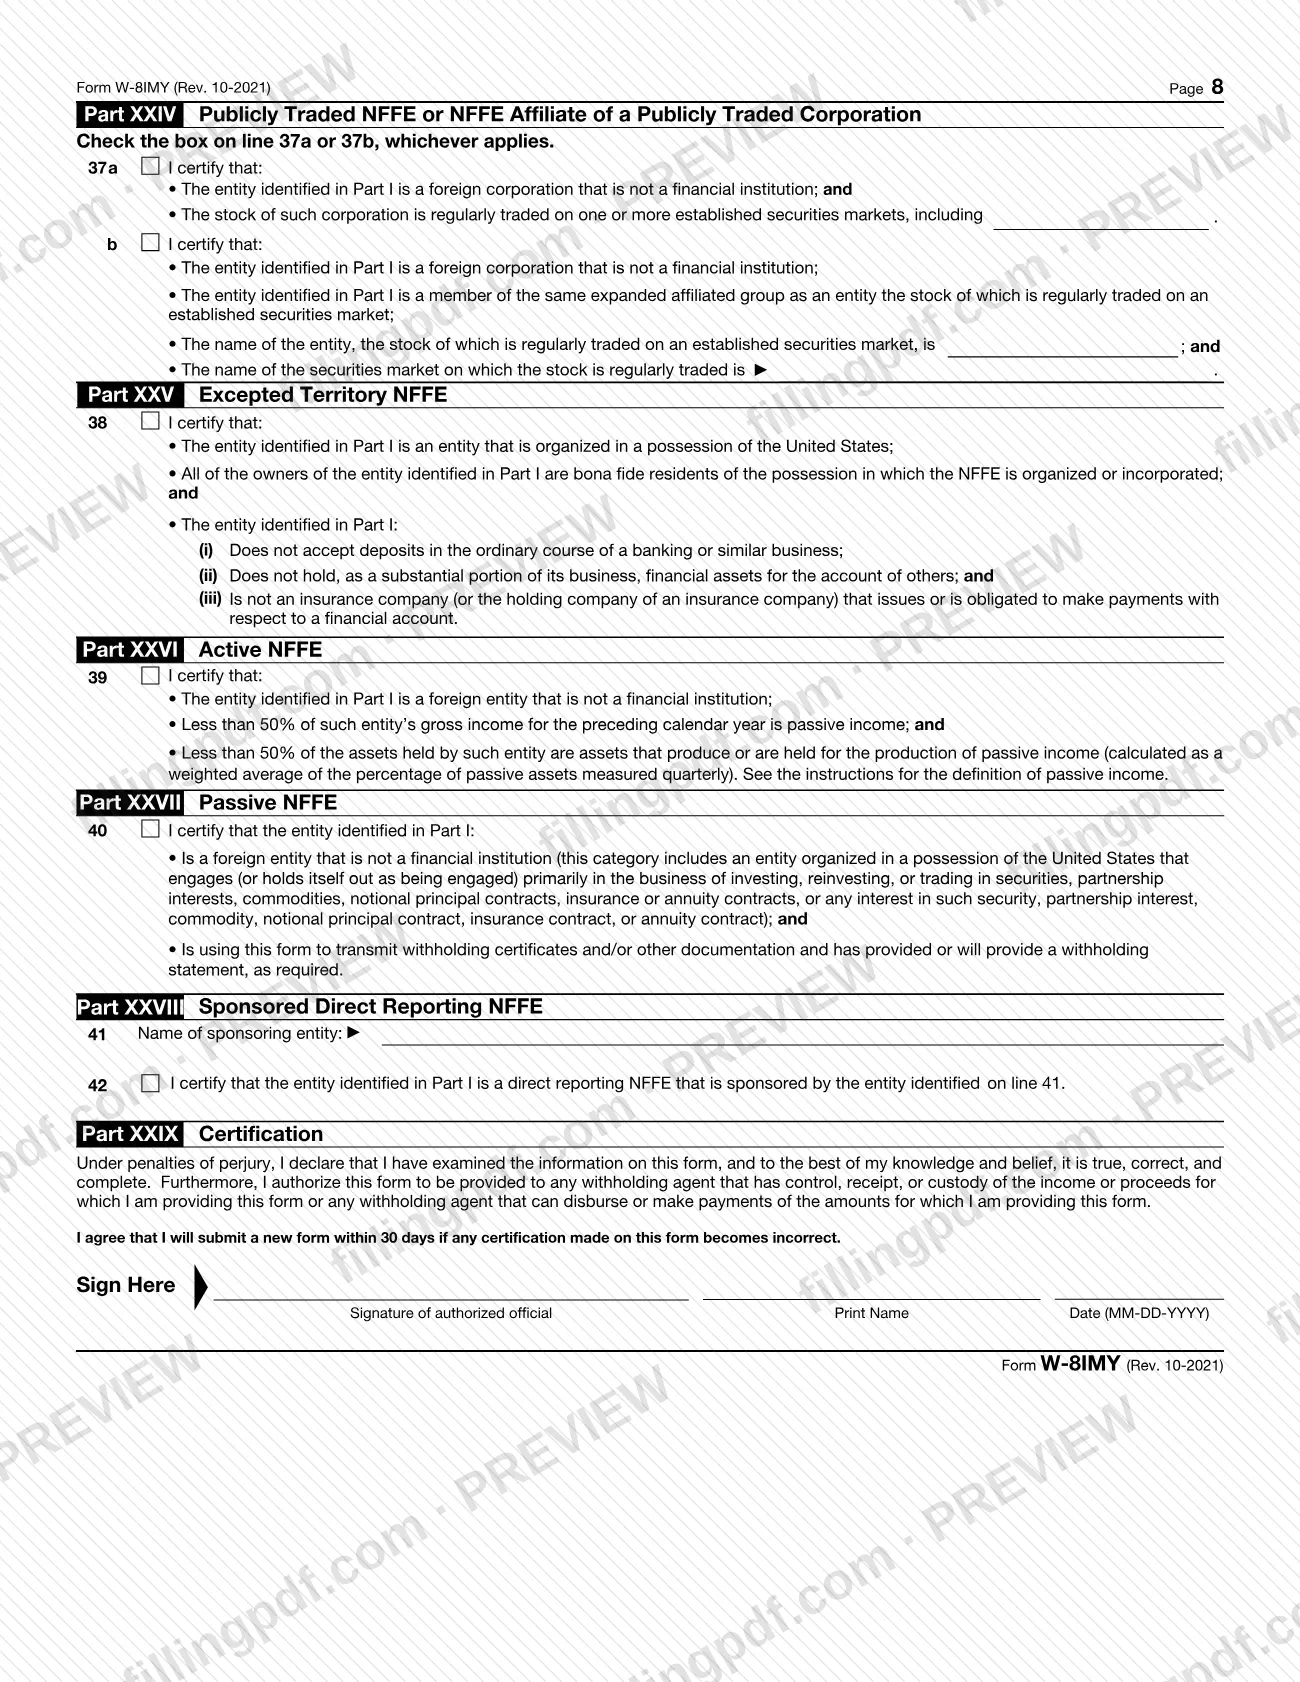
The form has a general identification block (Part I), an optional Part II for a disregarded entity or branch receiving payment, certifications of chapter 3 status (Parts III through VIII), certifications of chapter 4 or FATCA status (Parts IX through XXVIII) and a signed certification (Part XXIX). The entity completes only the parts that match the boxes it checks on lines 4 and 5.
The form does not replace other Forms W-8. The printed form lists the alternatives:
- W-8BEN or W-8BEN-E for a beneficial owner solely claiming foreign status or treaty benefits, and for a hybrid entity claiming treaty benefits on its own behalf (W-8BEN-E).
- W-8ECI for a foreign person claiming that income is effectively connected with a U.S. trade or business.
- W-8EXP for foreign governments, international organizations, foreign central banks of issue, foreign tax-exempt organizations and similar entities.
- W-9 for a U.S. entity or U.S. citizen or resident.
Who needs to file W-8IMY?
Form W-8IMY must be provided by the persons the IRS instructions list, when they receive a reportable amount or withholdable payment on behalf of someone else, or as a flow-through entity. The main groups are:
- A qualified intermediary (QI), including a QI acting as a QDD, or acting as a QSL.
- A nonqualified intermediary (NQI), meaning an intermediary that is not a U.S. person and not a QI.
- A withholding foreign partnership (WP) or withholding foreign trust (WT).
- A nonwithholding foreign partnership, foreign simple trust or foreign grantor trust, including one providing the form for section 1446(a) or 1446(f) purposes.
- A financial institution organized under the laws of a U.S. territory that acts as an intermediary or is a flow-through entity.
- A U.S. branch acting as an intermediary that represents the income it receives is not effectively connected with a U.S. trade or business.
- A nonparticipating FFI acting as an intermediary, or a flow-through entity transmitting documentation for exempt beneficial owners.
Do not use Form W-8IMY if you are the beneficial owner of the income and only need to prove foreign status or claim treaty benefits (use W-8BEN or W-8BEN-E), if the income is effectively connected with a U.S. trade or business (W-8ECI), or if you are a foreign government or tax-exempt organization claiming section 115(2), 501(c), 892, 895 or 1443(b) (W-8EXP). A disregarded entity generally does not submit this form: its single owner provides the appropriate Form W-8. U.S. persons use Form W-9.
When to file W-8IMY
Give Form W-8IMY to the withholding agent that requests it before income is paid, credited or allocated to your account. Without it, the withholding agent may have to withhold at the 30% rate, backup withhold, or withhold at the applicable rate under section 1446 for a foreign partner's share of effectively connected income.
A separate form generally goes to each withholding agent from which you receive payments. If you act in more than one capacity, for example as a QI for some accounts and an NQI for others, provide a separate form for each capacity.
The form generally remains valid until the status of the person named on it changes in a way relevant to the certificate, or a change in circumstances makes the information incorrect. That indefinite period does not extend to the withholding certificates, documentation or withholding statements attached to it. If a certification becomes incorrect, the form you sign says you will submit a new one within 30 days, and the IRS instructions require you to notify the withholding agent within 30 days of the change.
Documents you need
- A withholding statement, when required: it allocates each payment by income type to each payee or withholding rate pool and forms an integral part of the certificate.
- Withholding certificates (such as Form W-8BEN) or other documentation for the persons you receive payments for, when you check a box saying you are using the form to transmit them.
- A schedule with the Part II information for each branch or disregarded entity, only if you give one form covering multiple branches receiving payments from the same withholding agent.
- An FFI owner reporting statement with owner documentation, for an owner-documented FFI certifying on line 24b.
- An auditor's letter signed no more than 4 years before the date of payment, plus an FFI owner reporting statement and Form W-9 with applicable waivers, for an owner-documented FFI certifying on line 24c.
- Documentary evidence such as a bankruptcy filing or other public documentation, for an entity in liquidation or bankruptcy (line 36) that stays in that state for more than 3 years.
How to fill out W-8IMY
Identify the entity
Line 1: enter the name of the organization acting as intermediary; a disregarded entity enters the legal name of its owner instead. Line 2: country of incorporation or organization. Line 3: name of the disregarded entity, only if required.
Check your chapter 3 status
On line 4, check one box only, such as QI (including a QDD), Nonqualified intermediary, Territory financial institution, U.S. branch or a withholding or nonwithholding foreign partnership or trust. The box tells you which of Parts III through VIII to complete.
Check your chapter 4 status
On line 5, check one box only for your FATCA status, if required, for example Participating FFI, Passive NFFE or Owner-documented FFI. Each box names the part you complete later; if line 5 does not apply to you, the instructions say to leave it blank.
Enter permanent and mailing addresses
Line 6: your permanent residence address, with no P.O. box or in-care-of address other than a registered address. Line 7: mailing address, only if different from line 6.
Enter tax identification numbers
Line 8: your U.S. TIN if required, checking QI-EIN, WP-EIN, WT-EIN or EIN. Line 9a: your GIIN if applicable; line 9b: foreign TIN, if required for a QDD.
Add reference numbers
Line 10: enter any reference number the withholding agent needs, for example to associate this form with a Form W-8BEN or W-8BEN-E.
Complete Part II if it applies
Only for a disregarded entity with a GIIN or a branch of an FFI outside the FFI's country of residence. Check one status on line 11, give the branch address on line 12 and its GIIN on line 13.
Complete your chapter 3 part
Complete only the one part from III through VIII that matches line 4: for example Part III for a QI, Part IV for a nonqualified intermediary or Part VIII for a nonwithholding partnership or trust. Check the certification boxes that apply.
Complete your chapter 4 part
Complete the part from IX through XXVIII named beside the box you checked on line 5, filling in items such as the sponsoring entity name (lines 23a, 27a, 41) or the dates and market names it asks for.
Sign and date Part XXIX
The authorized official signs, prints a name and enters the date in MM-DD-YYYY format. The signature is made under penalties of perjury.
Review and download the PDF
Check that only one box is marked on lines 4 and 5, that the matching parts are completed and that attachments are ready. Download or print the completed PDF from FillingPDF, then give it to the withholding agent as described under How to submit.
How to submit W-8IMY
Form W-8IMY is not filed with the IRS. The form itself says to give it to the withholding agent or payer, and not to send it to the IRS. Delivery is by whatever method you and the requester use.
- To the requester: give the signed form to the person asking for it. The IRS instructions say this is generally the person from whom you receive the payment, the person who credits your account, or a partnership that allocates income to you. If you are an account holder of an FFI, the FFI may request it to document your account's chapter 4 status.
- With attachments: include any withholding statement and the withholding certificates or other documentation the form says you are transmitting. The withholding statement may be provided in any manner you and the withholding agent mutually agree, including electronically if the required safeguards are met.
- Multiple branches: if several branches or disregarded entities receive payments from the same withholding agent and Part I is identical, you may give one form with a schedule listing the Part II information for each branch.
- Withholding agent instructions: the IRS publishes separate instructions for the requester of Forms W-8BEN, W-8BEN-E, W-8ECI, W-8EXP and W-8IMY.
FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Sending Form W-8IMY to the IRS. The form says to give it to the withholding agent or payer and not to send it to the IRS.
- Checking more than one box on line 4 or line 5. The form allows one box only on each line.
- Completing more than one of Parts III through VIII. The instructions say to complete only one; use separate forms for separate capacities.
- Entering a disregarded entity's business name on line 1 instead of the legal name of the entity that owns it.
- Putting a P.O. box or in-care-of address on line 6, unless it is your registered address.
- Entering a disregarded entity's GIIN on line 9a instead of line 13 when you completed line 3.
- Using a QI-EIN, WP-EIN or WT-EIN on line 8 when you are not acting in that capacity; use your other U.S. TIN, if any.
- Using this form as a beneficial owner claiming only foreign status or treaty benefits, when Form W-8BEN or W-8BEN-E applies.
- Failing to submit a new form within 30 days after a certification becomes incorrect.
Frequently asked questions
What is Form W-8IMY used for?
Form W-8IMY is the IRS certificate an intermediary or flow-through entity gives a withholding agent to document its chapter 3 and chapter 4 status when it receives a payment on behalf of others. It is also used by QDDs, QSLs and certain U.S. branches.
Do I send Form W-8IMY to the IRS?
No. The form says to give it to the withholding agent or payer and not to send it to the IRS. Generally that is the person you receive the payment from, the person who credits your account, or a partnership that allocates income to you.
When do I use Form W-8BEN-E instead of Form W-8IMY?
Use Form W-8BEN or W-8BEN-E if you are the beneficial owner claiming foreign status or treaty benefits on your own behalf. A hybrid entity claiming treaty benefits for itself also uses W-8BEN-E. Form W-8IMY is for entities receiving payments for someone else.
How long is Form W-8IMY valid?
Generally until the status of the person named on it changes in a relevant way, or a change in circumstances makes the information incorrect. The indefinite period does not cover attached withholding certificates, documentation or withholding statements. Notify the withholding agent within 30 days of a change.
Can I complete more than one part from III through VIII?
No. The IRS instructions say to complete only one of Parts III through VIII. If you act in several capacities, such as QI for some accounts and NQI for others, provide a separate Form W-8IMY for each capacity.
Is a withholding statement required with Form W-8IMY?
Often, yes. Many certifications say you have provided or will provide a withholding statement, as required. It allocates payments to each payee or withholding rate pool and forms an integral part of the certificate. Check the instructions for your status.
Can I fill out Form W-8IMY online on FillingPDF?
Yes. You can fill out the W-8IMY PDF online on FillingPDF and download or print it. FillingPDF is an independent service that does not deliver the form; you give the completed form to the withholding agent that requested it.
Where do I find the instructions for Form W-8IMY?
The IRS publishes Instructions for Form W-8IMY (Rev. October 2021) and directs you to www.irs.gov/FormW8IMY for the latest information. Withholding agents have separate IRS instructions for the requester of Forms W-8BEN, W-8BEN-E, W-8ECI, W-8EXP and W-8IMY.
Ready to fill out W-8IMY?
Fill out W-8IMY now