
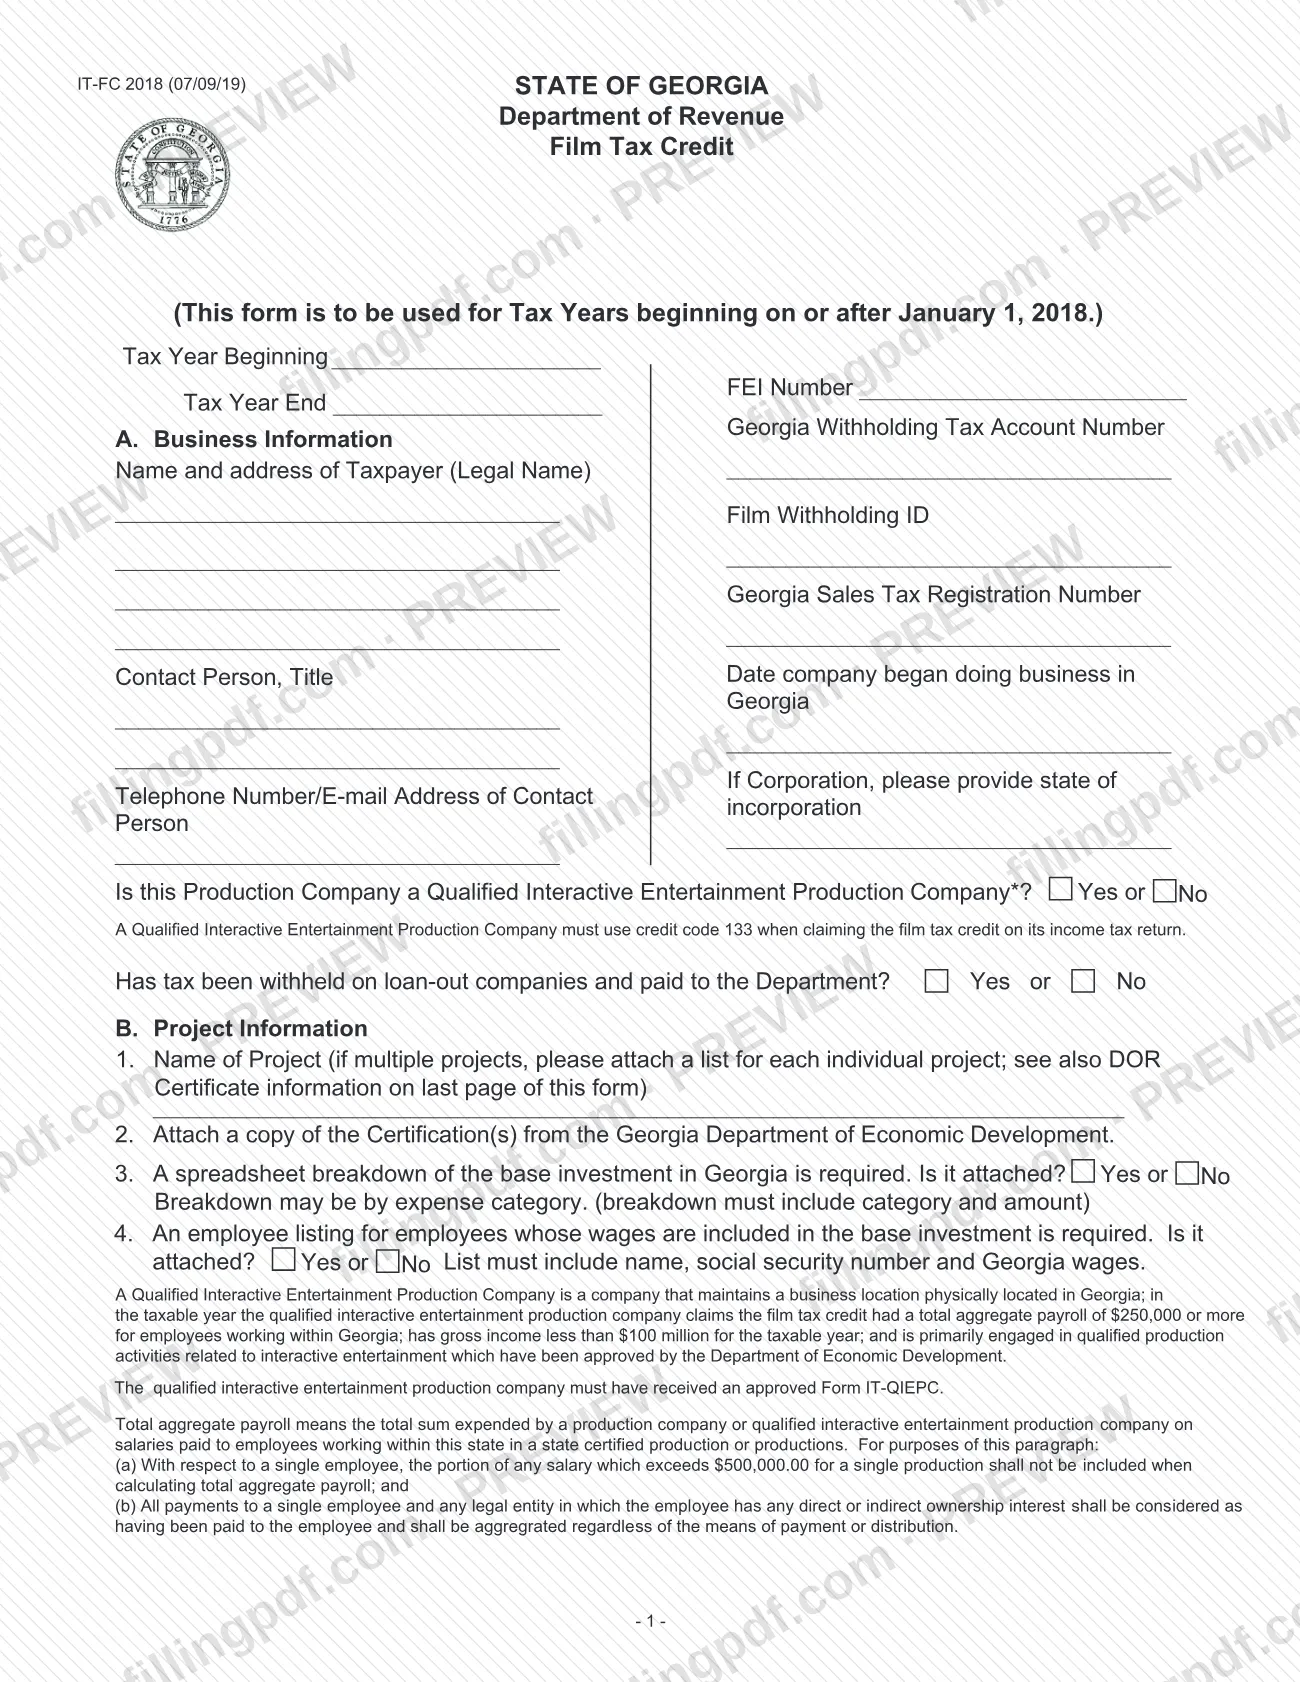
Form IT-FC, Film Tax Credit, is the State of Georgia Department of Revenue (DOR) form on which a production company figures its film tax credit for a tax year, applies it against Georgia income tax liability and tracks any balance carried forward. It is used for tax years beginning on or after January 1, 2018, and the revision printed on it is IT-FC 2018 (07/09/19). On this page you can fill out the form online on FillingPDF and download or print the completed PDF; the form itself is published by the Georgia Department of Revenue.
Last updated
What is IT-FC?
Form IT-FC, Film Tax Credit, is the Georgia Department of Revenue form on which a production company reports its business and project information, calculates the film tax credit for the current tax year and shows how much credit is used or carried forward.
The form is used for tax years beginning on or after January 1, 2018. It has three printed pages:
- Page 1: business information (Section A) and project information (Section B), including the attachments the form requires.
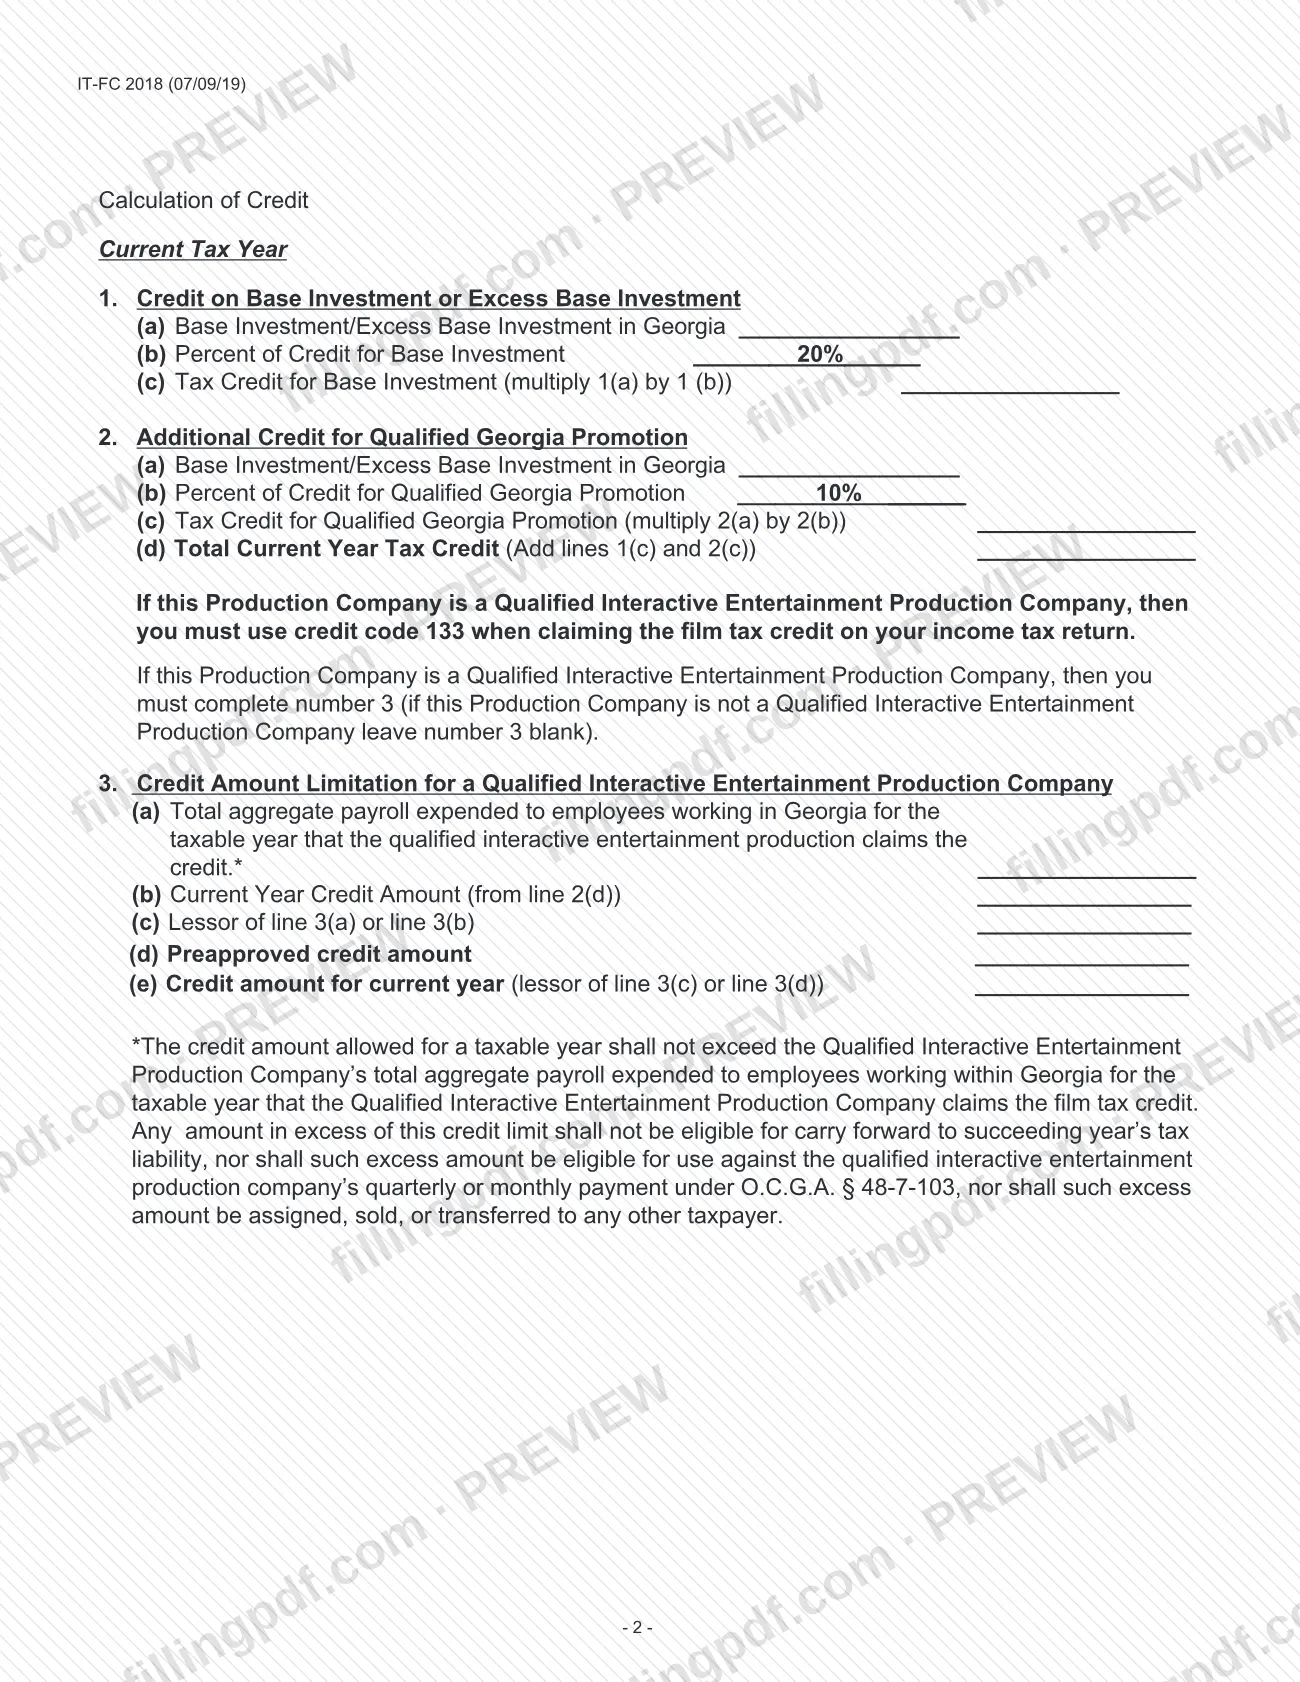
- Page 2: the Calculation of Credit. Line 1 is the credit on base investment or excess base investment, line 2 is the additional credit for a Qualified Georgia Promotion, and line 3 is a credit limitation that applies only to a Qualified Interactive Entertainment Production Company.
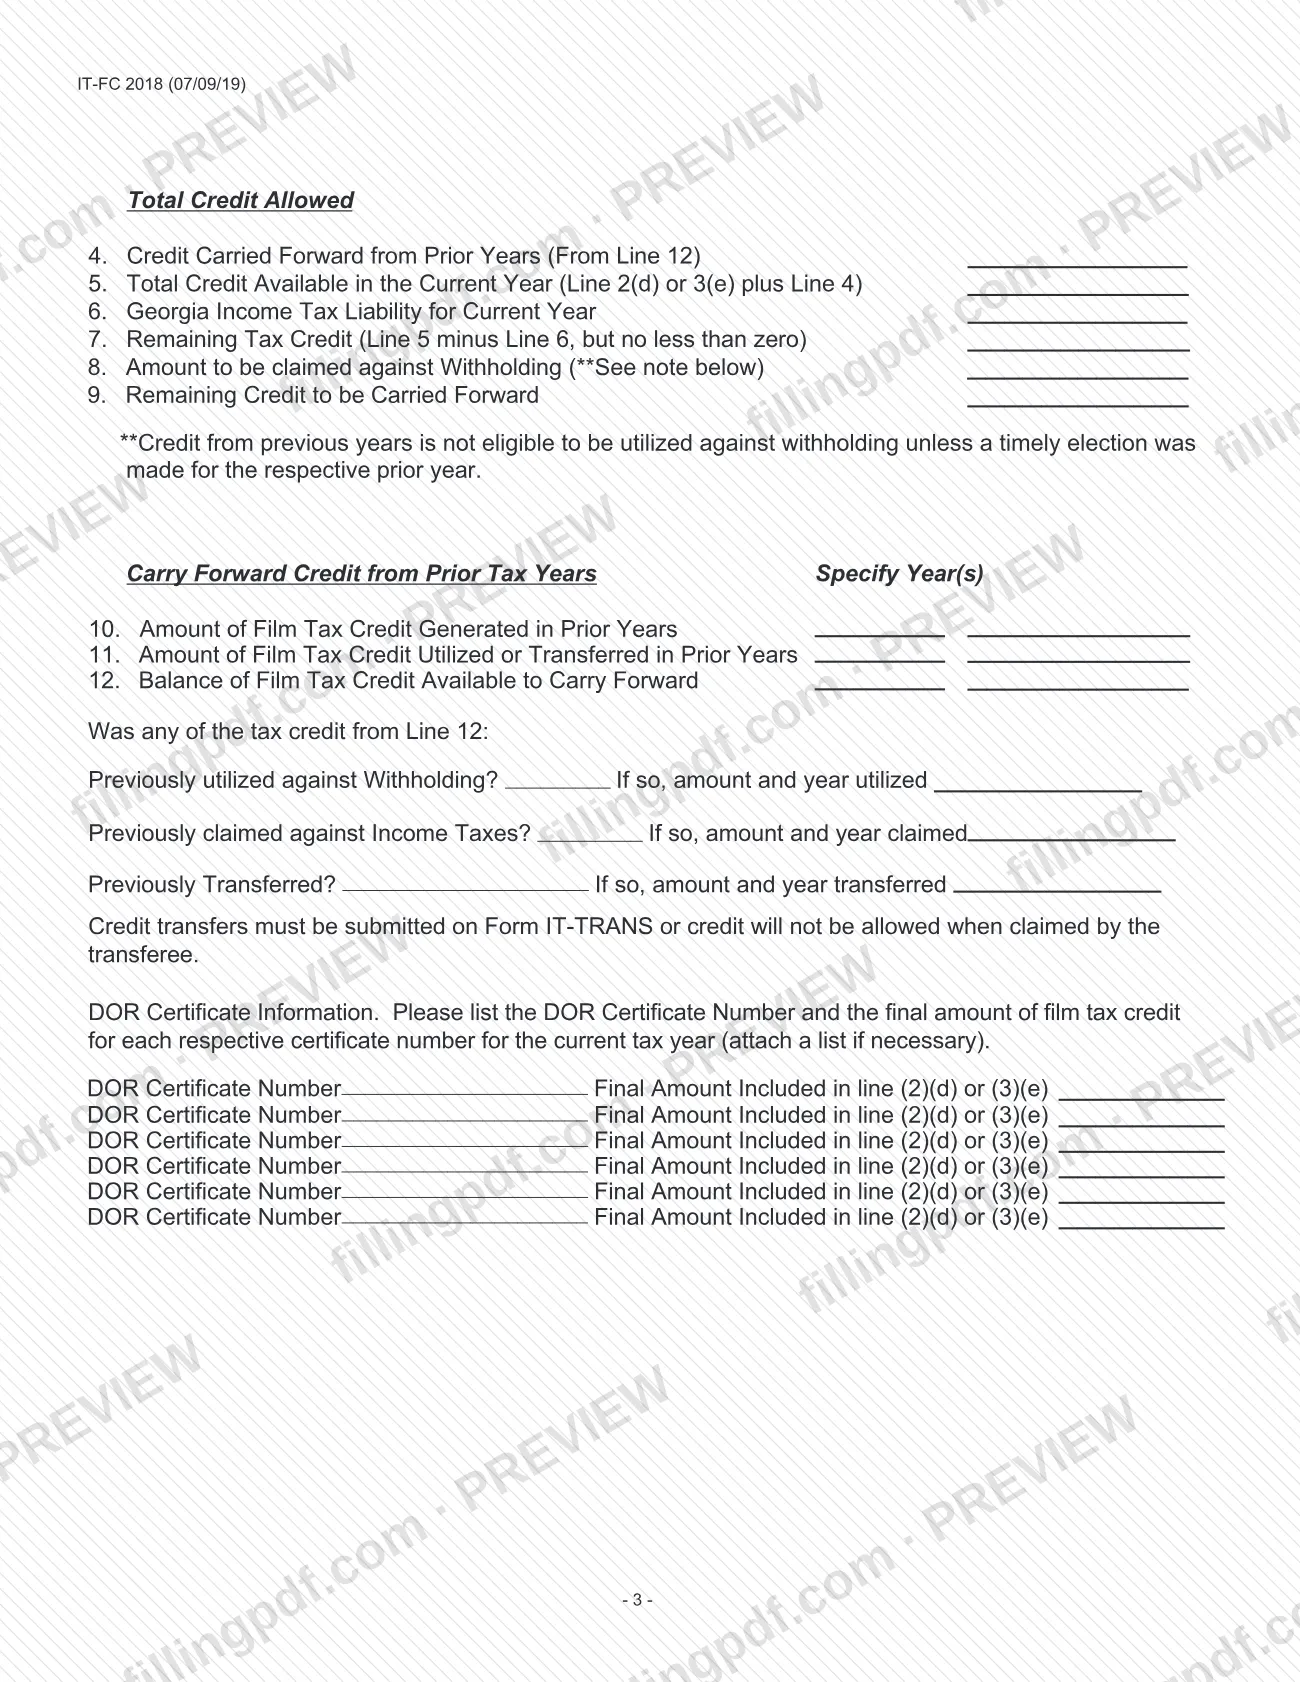
- Page 3: Total Credit Allowed (lines 4 to 9), the carry-forward schedule (lines 10 to 12) and the list of DOR Certificate Numbers with the final credit amount for each.
A Qualified Interactive Entertainment Production Company must have received an approved Form IT-QIEPC and must use credit code 133 when it claims the credit on its income tax return. Credit transfers are not made on this form: they must be submitted on Form IT-TRANS.
Who needs to file IT-FC?
Production companies that claim the Georgia film tax credit for a tax year beginning on or after January 1, 2018 use Form IT-FC. The form asks for the Georgia Department of Economic Development certification(s) for each project, so it belongs to companies whose projects have been certified.
Special rules apply to a Qualified Interactive Entertainment Production Company. The form describes it as a company that:
- maintains a business location physically in Georgia;
- meets the total aggregate payroll test for employees working within Georgia in the year it claims the credit;
- has gross income below the limit printed on the form for the taxable year; and
- is primarily engaged in qualified production activities related to interactive entertainment approved by the Department of Economic Development.
That company must also hold an approved Form IT-QIEPC, use credit code 133, and complete line 3. A production company that is not a Qualified Interactive Entertainment Production Company leaves line 3 blank.
Credit carried from earlier years can be used against withholding only if a timely election was made for that earlier year.
When to file IT-FC
Complete Form IT-FC when you claim the film tax credit for a tax year that begins on or after January 1, 2018. The form carries no due date of its own; it prints the tax year beginning and tax year end at the top, so it is prepared for the tax year in which the credit is claimed.
Timing matters in two places. A credit carried forward from prior years can be applied against withholding only if a timely election was made for the respective prior year. And for a Qualified Interactive Entertainment Production Company, any credit above the line 3 limit cannot be carried forward to later years. For any filing deadline that applies to your income tax return, check with the Georgia Department of Revenue.
Documents you need
- A copy of the Certification(s) from the Georgia Department of Economic Development for each project (Section B, item 2).
- A spreadsheet breakdown of the base investment in Georgia, by expense category if you choose, showing each category and amount (item 3).
- An employee listing for employees whose wages are included in the base investment, with name, social security number and Georgia wages (item 4).
- A list of projects, one entry for each individual project, if you are claiming credit for more than one project (item 1).
- A list of DOR Certificate Numbers with the final credit amount for each, attached if the six rows on page 3 are not enough.
- Approved Form IT-QIEPC: a Qualified Interactive Entertainment Production Company must have received it.
- Form IT-TRANS: needed for any credit transfer, or the credit will not be allowed when the transferee claims it.
How to fill out IT-FC
Enter the tax year and account numbers
At the top, write the Tax Year Beginning and Tax Year End dates, your FEI Number and your Georgia Withholding Tax Account Number.
Complete the business information
In Section A, enter the taxpayer's legal name and address, Film Withholding ID, Georgia Sales Tax Registration Number, the date the company began doing business in Georgia, and the state of incorporation if a corporation. Add the contact person, title, telephone number and e-mail address.
Answer the two Yes or No questions
Mark whether the company is a Qualified Interactive Entertainment Production Company, and whether tax has been withheld on loan-out companies and paid to the Department. A Qualified Interactive Entertainment Production Company must use credit code 133.
Identify the project and attachments
In Section B, line 1, enter the name of the project, with a separate list for each project if there are several. Attach the Department of Economic Development certification(s), and mark Yes or No for the base investment spreadsheet (line 3) and the employee listing (line 4).
Calculate the credit on lines 1 and 2
On line 1, enter the base investment or excess base investment in Georgia in 1(a), use the percentage printed in 1(b) and multiply for 1(c). Repeat for line 2(a) to 2(c), then add 1(c) and 2(c) on line 2(d) for the total current year tax credit.
Complete line 3 only if required
If you are a Qualified Interactive Entertainment Production Company, enter total aggregate payroll in 3(a), the line 2(d) amount in 3(b), the lesser of the two in 3(c), the preapproved credit amount in 3(d) and the lesser of 3(c) or 3(d) in 3(e). Otherwise leave line 3 blank.
Figure the total credit allowed
Enter the prior-year carryforward from line 12 on line 4, then add it to line 2(d) or 3(e) on line 5. Enter Georgia income tax liability on line 6, line 5 minus line 6 (not below zero) on line 7, the amount claimed against withholding on line 8 and the remainder on line 9.
Complete the carry-forward schedule
On lines 10 to 12, enter the credit generated, the credit utilized or transferred, and the balance available to carry forward, specifying the years. Then answer whether any line 12 credit was previously used against withholding, claimed against income taxes or transferred, with the amount and year.
List the DOR certificates
On page 3, enter each DOR Certificate Number and the final amount included in line 2(d) or 3(e). Attach a list if you need more than six rows.
Review and download the completed PDF
Check that every amount matches your attachments and that line 3 is filled only if it applies. Download or print the completed PDF from FillingPDF and send it with its attachments as the Georgia Department of Revenue directs.
How to submit IT-FC
Form IT-FC prints no mailing address, portal or other filing channel, so confirm how and where to send it with the Georgia Department of Revenue (DOR), which publishes the form and its agency page at https://dor.georgia.gov/it-fc.
What the form itself requires you to include:
- Project certifications: a copy of the Certification(s) from the Georgia Department of Economic Development (Section B, item 2).
- Base investment spreadsheet: a breakdown of the base investment in Georgia, which may be by expense category and must show category and amount (item 3).
- Employee listing: for employees whose wages are included in the base investment, with name, social security number and Georgia wages (item 4).
- Project list: a separate list for each project if you have more than one (item 1).
- DOR certificate list: an attached list if the six certificate rows on page 3 are not enough.
A Qualified Interactive Entertainment Production Company claims the credit on its income tax return using credit code 133. A credit transfer must be submitted on Form IT-TRANS, or the credit will not be allowed when the transferee claims it. FillingPDF lets you fill out and download the PDF; submission follows the channels the DOR specifies.
Common mistakes to avoid
- Completing line 3 when the company is not a Qualified Interactive Entertainment Production Company; the form says to leave number 3 blank in that case.
- Claiming the credit without credit code 133 on the income tax return when the company is a Qualified Interactive Entertainment Production Company.
- Leaving out the copy of the Georgia Department of Economic Development Certification(s) required under Section B, item 2.
- Attaching a base investment spreadsheet that lacks category and amount, or an employee listing that lacks name, social security number or Georgia wages.
- Listing several projects without attaching a list for each individual project.
- Applying credit from a previous year against withholding without a timely election for that year.
- Transferring credit without submitting Form IT-TRANS; the transferee's claim will not be allowed.
- Entering a negative number on line 7; the form says Remaining Tax Credit is line 5 minus line 6, but no less than zero.
- Using this form for a tax year beginning before January 1, 2018.
Frequently asked questions
What is Form IT-FC, the Georgia Film Tax Credit form?
Form IT-FC, Film Tax Credit, is a State of Georgia Department of Revenue form for tax years beginning on or after January 1, 2018. A production company uses it to calculate the film tax credit, apply it against income tax liability and track the balance carried forward.
What do I need to attach to the film tax credit form?
Attach a copy of the Georgia Department of Economic Development Certification(s), a spreadsheet breakdown of the base investment in Georgia with category and amount, and an employee listing with name, social security number and Georgia wages. Multiple projects need a list for each project.
When do I use credit code 133?
A Qualified Interactive Entertainment Production Company must use credit code 133 when claiming the film tax credit on its income tax return. The company must also hold an approved Form IT-QIEPC and complete line 3 of Form IT-FC.
Do I have to complete line 3 of Form IT-FC?
Only if the production company is a Qualified Interactive Entertainment Production Company. Line 3 limits the credit to the company's total aggregate payroll in Georgia and to the preapproved amount. Any other production company leaves line 3 blank.
Can I carry forward an unused film tax credit?
Yes, the form has a carry-forward schedule on lines 10 to 12 and carries the balance to line 9. The exception is a Qualified Interactive Entertainment Production Company: credit above its line 3 limit cannot be carried forward, used against quarterly or monthly payments, or transferred.
Can I use prior-year film tax credit against withholding?
Only if a timely election was made for that prior year. The note under line 9 states that credit from previous years is not eligible to be used against withholding unless a timely election was made for the respective year.
How do I transfer film tax credit to another taxpayer?
Submit the transfer on Form IT-TRANS. The form warns that credit transfers must be submitted on Form IT-TRANS or the credit will not be allowed when the transferee claims it. Form IT-FC asks whether any carried-forward credit was previously transferred.
Can I fill out Form IT-FC online?
You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the form with the Georgia Department of Revenue; you send it through the channels the department specifies.
Ready to fill out IT-FC?
Fill out IT-FC now