
The Business Equipment Tax Exemption Application, which some people search for as the UT application, is the Maine Revenue Services (MRS) Property Tax Division form for property in the unorganized territory (36 M.R.S. §§ 691 - 700-B). Owners of qualifying business equipment list each item on it to claim the Business Equipment Tax Exemption (BETE), a 100% property tax exemption, and the form must be filed every year. On FillingPDF you can fill out the form online and download or print the completed PDF; MRS publishes the original PDF at the official URL.
Last updated
What is Business Equipment Tax Exemption Application – Maine?
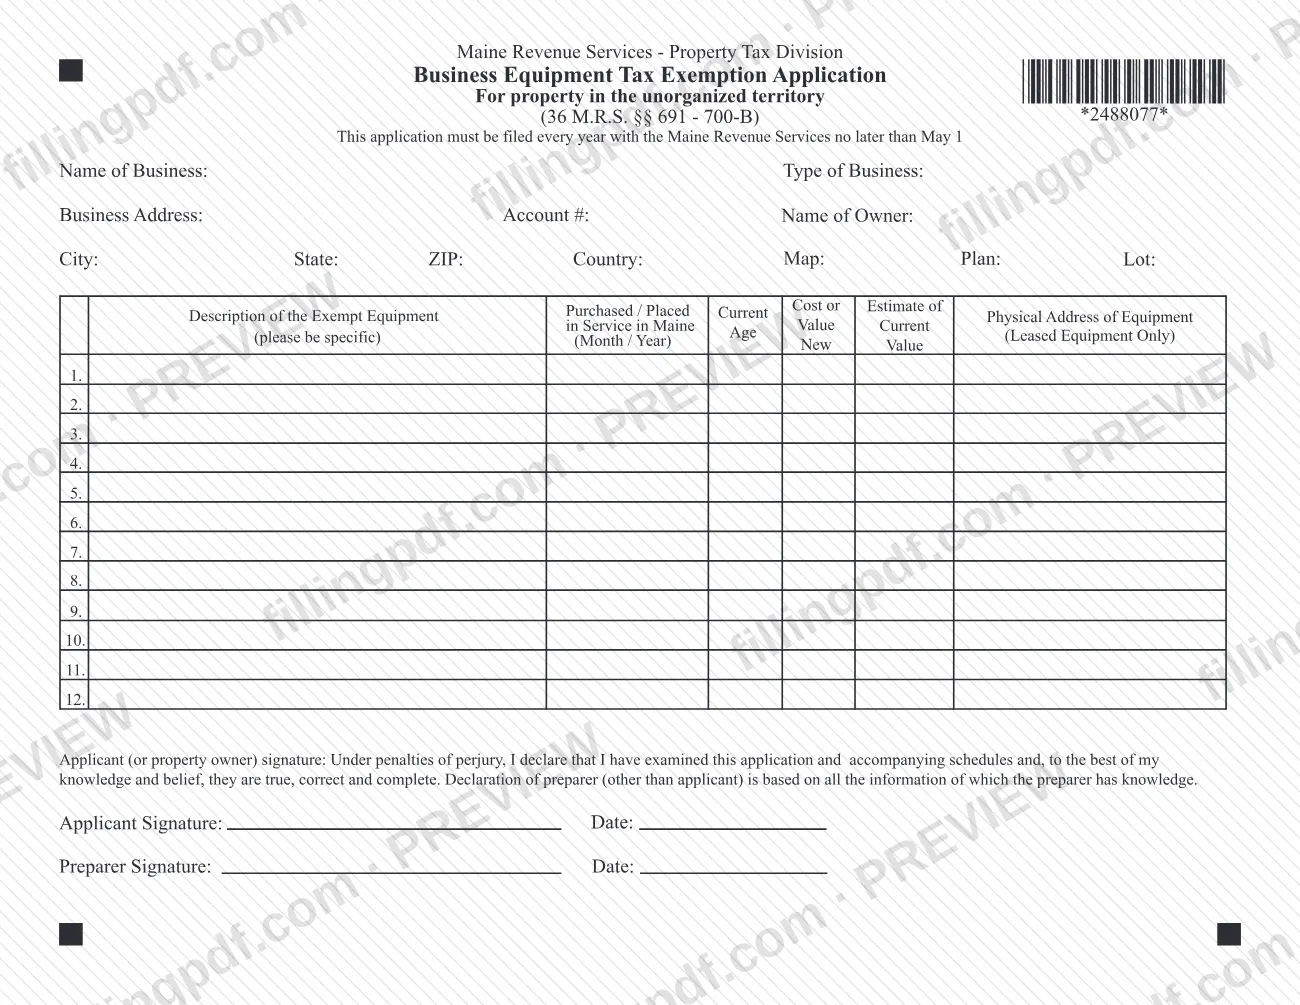
The Business Equipment Tax Exemption Application is the Maine Revenue Services Property Tax Division form on which a business lists eligible equipment in the unorganized territory to claim the Business Equipment Tax Exemption (BETE) under 36 M.R.S. §§ 691 - 700-B.
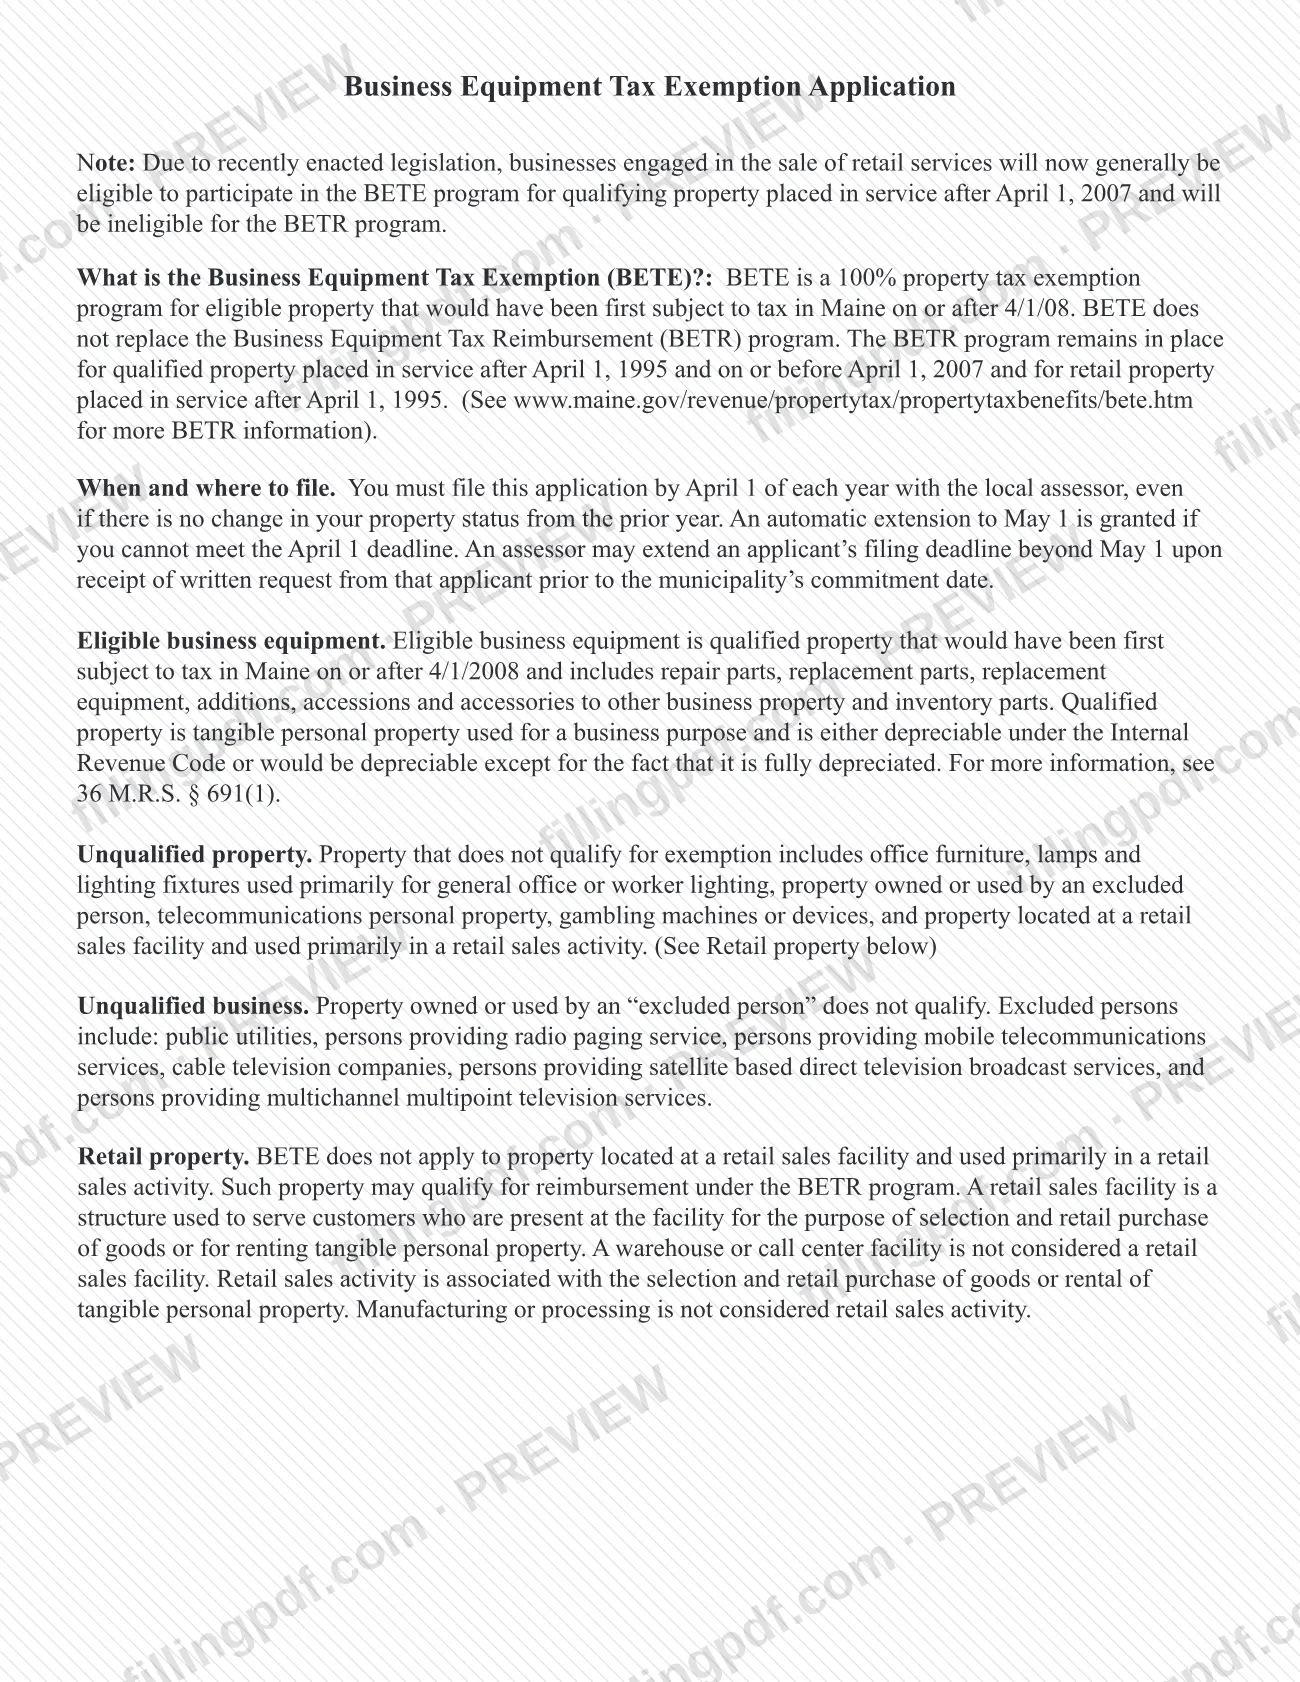
BETE is a 100% property tax exemption for eligible property that would have been first subject to tax in Maine on or after 4/1/08. It does not replace the Business Equipment Tax Reimbursement (BETR) program, which remains in place for qualified property placed in service after April 1, 1995 and on or before April 1, 2007, and for retail property placed in service after April 1, 1995.
Eligible equipment is qualified property: tangible personal property used for a business purpose that is depreciable under the Internal Revenue Code, or would be depreciable except that it is fully depreciated. It includes repair parts, replacement parts, replacement equipment, additions, accessions and accessories to other business property, and inventory parts. The form's note adds that, because of recent legislation, businesses engaged in the sale of retail services are generally eligible for BETE for qualifying property placed in service after April 1, 2007 and are ineligible for BETR.
The form is a single list of up to 12 numbered items, each with a description, in-service date, cost or value new, current age, estimate of current value and, for leased equipment, the physical address. It ends with a declaration under penalties of perjury.
Who needs to file Business Equipment Tax Exemption Application – Maine?
Owners or users of eligible business equipment located in the unorganized territory file this application to claim BETE. The form is signed by the applicant (or property owner); a preparer other than the applicant also signs the preparer line.
Some property and persons do not qualify:
- Office furniture, and lamps and lighting fixtures used primarily for general office or worker lighting.
- Telecommunications personal property and gambling machines or devices.
- Property located at a retail sales facility and used primarily in a retail sales activity. That property may qualify for reimbursement under the BETR program instead. A warehouse or call center is not a retail sales facility, and manufacturing or processing is not retail sales activity.
- Property owned or used by an "excluded person": public utilities, persons providing radio paging service, persons providing mobile telecommunications services, cable television companies, persons providing satellite based direct television broadcast services, and persons providing multichannel multipoint television services.
The instructions also state that only equipment placed in service after April 1, 2007 is eligible for BETE.
When to file Business Equipment Tax Exemption Application – Maine
The form's heading says the application must be filed every year with Maine Revenue Services no later than May 1. The accompanying general instructions describe the same cycle another way: file by April 1 of each year with the local assessor, even if your property status has not changed since the prior year.
An automatic extension to May 1 is granted if you cannot meet the April 1 deadline. An assessor may extend an applicant's deadline beyond May 1 on receiving that applicant's written request before the municipality's commitment date. Because the form is annual, a new application is needed each year even when the equipment list is unchanged.
How to fill out Business Equipment Tax Exemption Application – Maine
Enter business name and type
Write the Name of Business, the Type of Business and the Name of Owner at the top of the form.
Add address and account number
Enter the Business Address, Account #, City, State, ZIP and Country.
Fill in map, plan and lot
Enter the Map, Plan and Lot identifiers in the header block.
Describe each piece of equipment
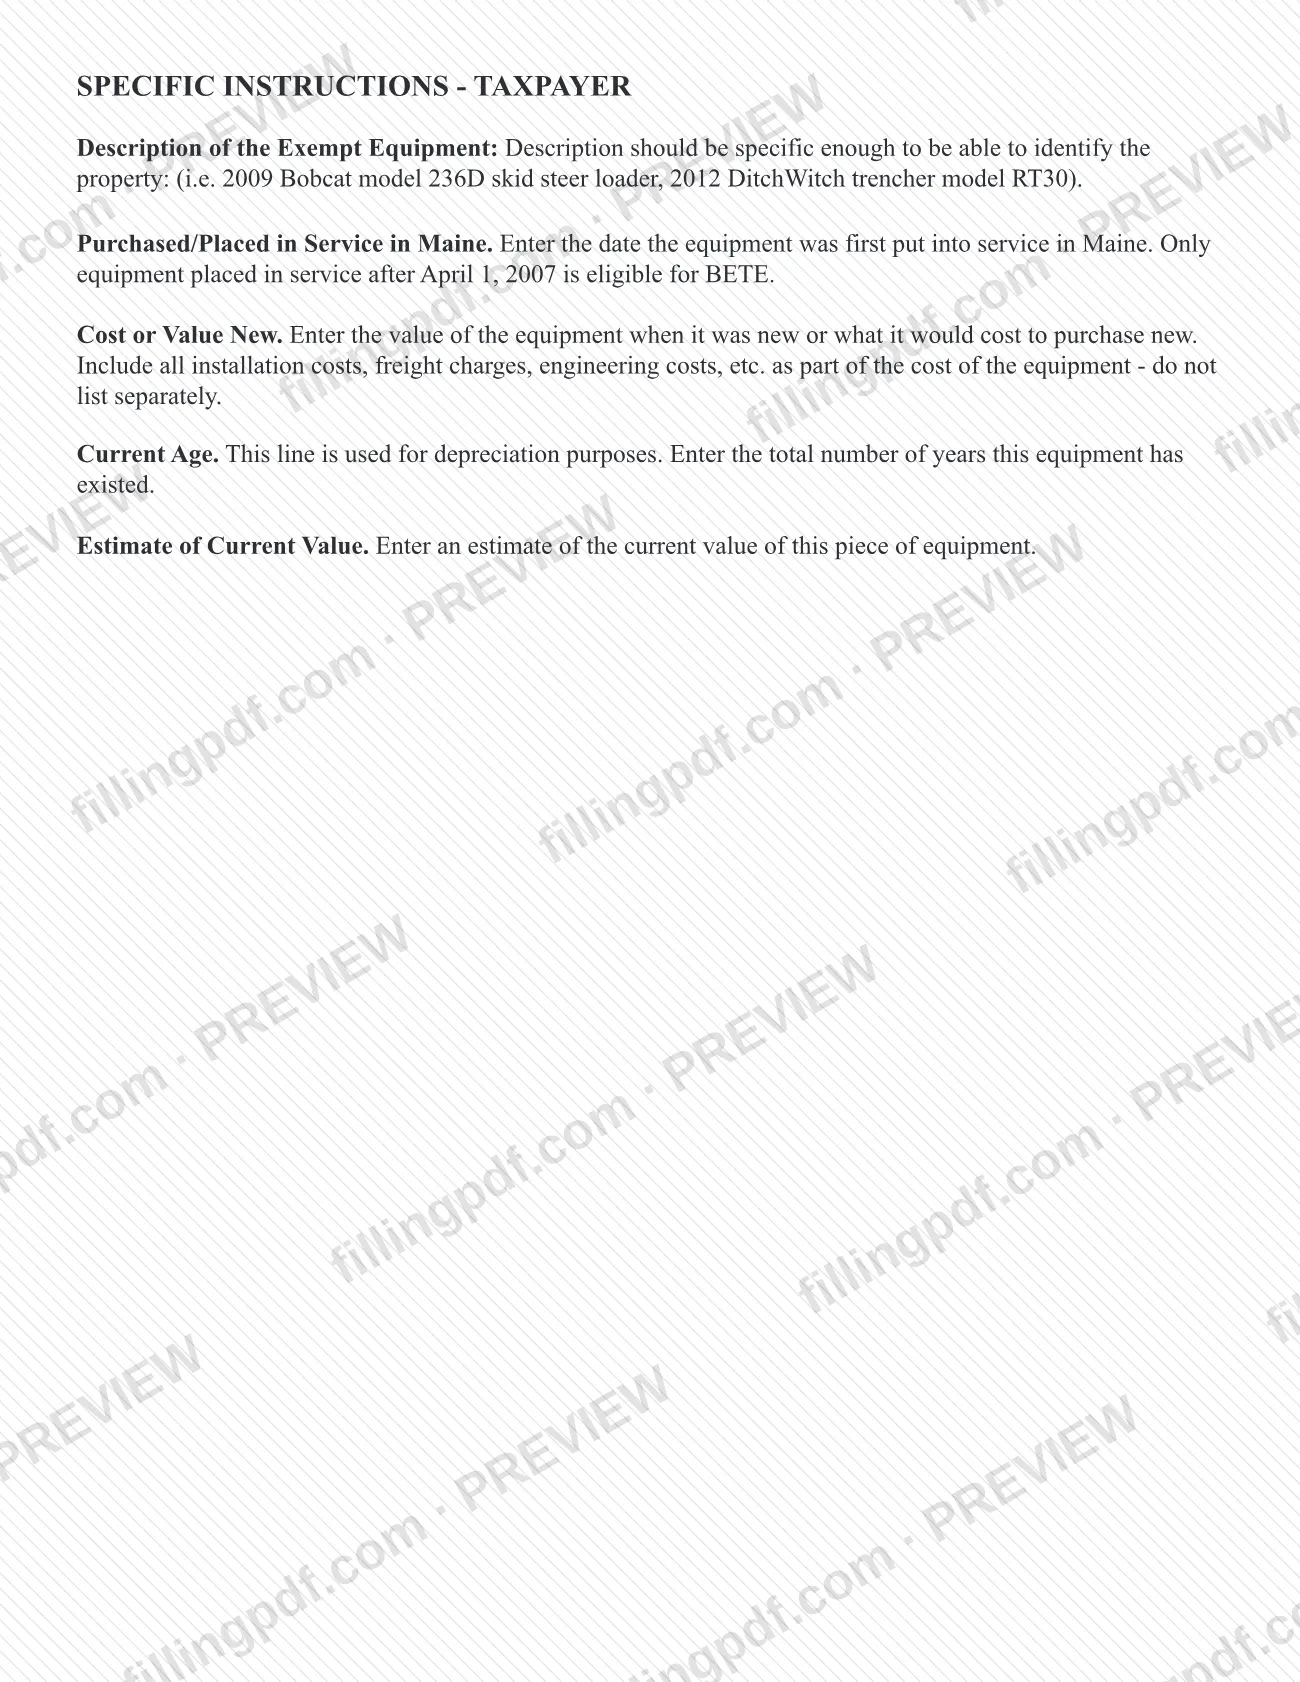
In the Description of the Exempt Equipment column, use up to 12 numbered lines and be specific enough to identify the item, for example a model year, make and model.
Enter the in-service date
In the Purchased / Placed in Service in Maine column, enter the month and year the equipment was first put into service in Maine. Only equipment placed in service after April 1, 2007 is eligible.
Enter cost or value new
Enter the value of the equipment when new, or what it would cost to buy new, including installation, freight and engineering costs. Do not list those costs separately.
Enter current age
In the Current Age column, enter the total number of years the equipment has existed; it is used for depreciation purposes.
Estimate current value
Enter your estimate of the current value of each piece of equipment in the Estimate of Current Value column.
Add address for leased equipment
In the Physical Address of Equipment column, enter the address for leased equipment only.
Sign and date the declaration
The applicant (or property owner) signs and dates under penalties of perjury. A preparer other than the applicant also signs and dates the preparer line.
Review and download the PDF
Check each line against the eligibility rules, then download or print the completed PDF from FillingPDF and file it through the channels described under How to submit.
How to submit Business Equipment Tax Exemption Application – Maine
The form's heading directs you to file the application with Maine Revenue Services, and the general instructions refer to filing with the local assessor; the form prints no mailing address, portal or appointment rule of its own.
- Maine Revenue Services: the heading states the application is filed with MRS each year no later than May 1.
- Local assessor: the general instructions say to file with the local assessor by April 1, with an automatic extension to May 1. A request for a later deadline goes to the assessor in writing before the municipality's commitment date.
The application must be signed and dated by the applicant (or property owner), and by the preparer if someone other than the applicant prepared it. For where to send it and any fee, contact Maine Revenue Services. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Skipping the yearly filing because nothing changed; the instructions say to file every year even with no change in property status.
- Listing property that does not qualify, such as office furniture, general office lighting, telecommunications personal property or gambling machines.
- Including retail property located at a retail sales facility and used primarily in retail sales activity; that property may fall under BETR instead.
- Claiming equipment first placed in service in Maine on or before April 1, 2007; only equipment placed in service after that date is eligible for BETE.
- Writing a vague description instead of one specific enough to identify the item, such as year, make and model.
- Listing installation, freight or engineering costs on separate lines; they belong in the cost or value new of the equipment.
- Leaving out the physical address of equipment that is leased.
- Sending the form unsigned or without the preparer's signature when someone other than the applicant prepared it.
Frequently asked questions
What is the UT application for Maine property tax?
It is the Business Equipment Tax Exemption Application from Maine Revenue Services for property in the unorganized territory. Businesses list eligible equipment on it to claim BETE, a 100% property tax exemption under 36 M.R.S. §§ 691 - 700-B.
When is the Business Equipment Tax Exemption Application due?
The form says it must be filed every year with Maine Revenue Services no later than May 1. The general instructions say April 1 with the local assessor, with an automatic extension to May 1. An assessor may extend further on a written request made before the commitment date.
Do I have to file the BETE application every year?
Yes. The instructions say the application must be filed each year, even if there is no change in your property status from the prior year.
What equipment qualifies for BETE?
Qualified property is tangible personal property used for a business purpose that is depreciable under the Internal Revenue Code, or would be except that it is fully depreciated. It must be placed in service after April 1, 2007 and would have been first taxed in Maine on or after 4/1/2008.
Does retail equipment qualify for BETE?
No. BETE does not apply to property at a retail sales facility used primarily in retail sales activity. That property may qualify for reimbursement under the BETR program. Warehouses and call centers are not retail sales facilities, and manufacturing is not retail sales activity.
What is the difference between BETE and BETR?
BETE is a 100% exemption for eligible property first taxed in Maine on or after 4/1/08. BETR is a reimbursement program that remains for qualified property placed in service after April 1, 1995 and on or before April 1, 2007, and for retail property placed in service after April 1, 1995.
What do I enter for cost or value new?
Enter the equipment's value when new, or what it would cost to buy new. Include installation costs, freight charges and engineering costs in that figure rather than listing them separately.
Can I fill out this application online on FillingPDF?
Yes. You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service, not affiliated with Maine Revenue Services, and does not file the application; you submit it through the agency's channels.
Ready to fill out Business Equipment Tax Exemption Application – Maine?
Fill out Business Equipment Tax Exemption Application – Maine now