
2025 Schedule NIIT, Net Investment Income Tax, is the Minnesota Department of Revenue schedule that figures Minnesota net investment income and the tax due on it. Individuals, estates and trusts with over $1,000,000 of investment income complete it and include it with Form M1 or Form M2. On this page you can fill out the form online on FillingPDF and download or print the completed PDF; the PDF and its instructions are published by the Minnesota Department of Revenue.
Last updated
What is Schedule NIIT?
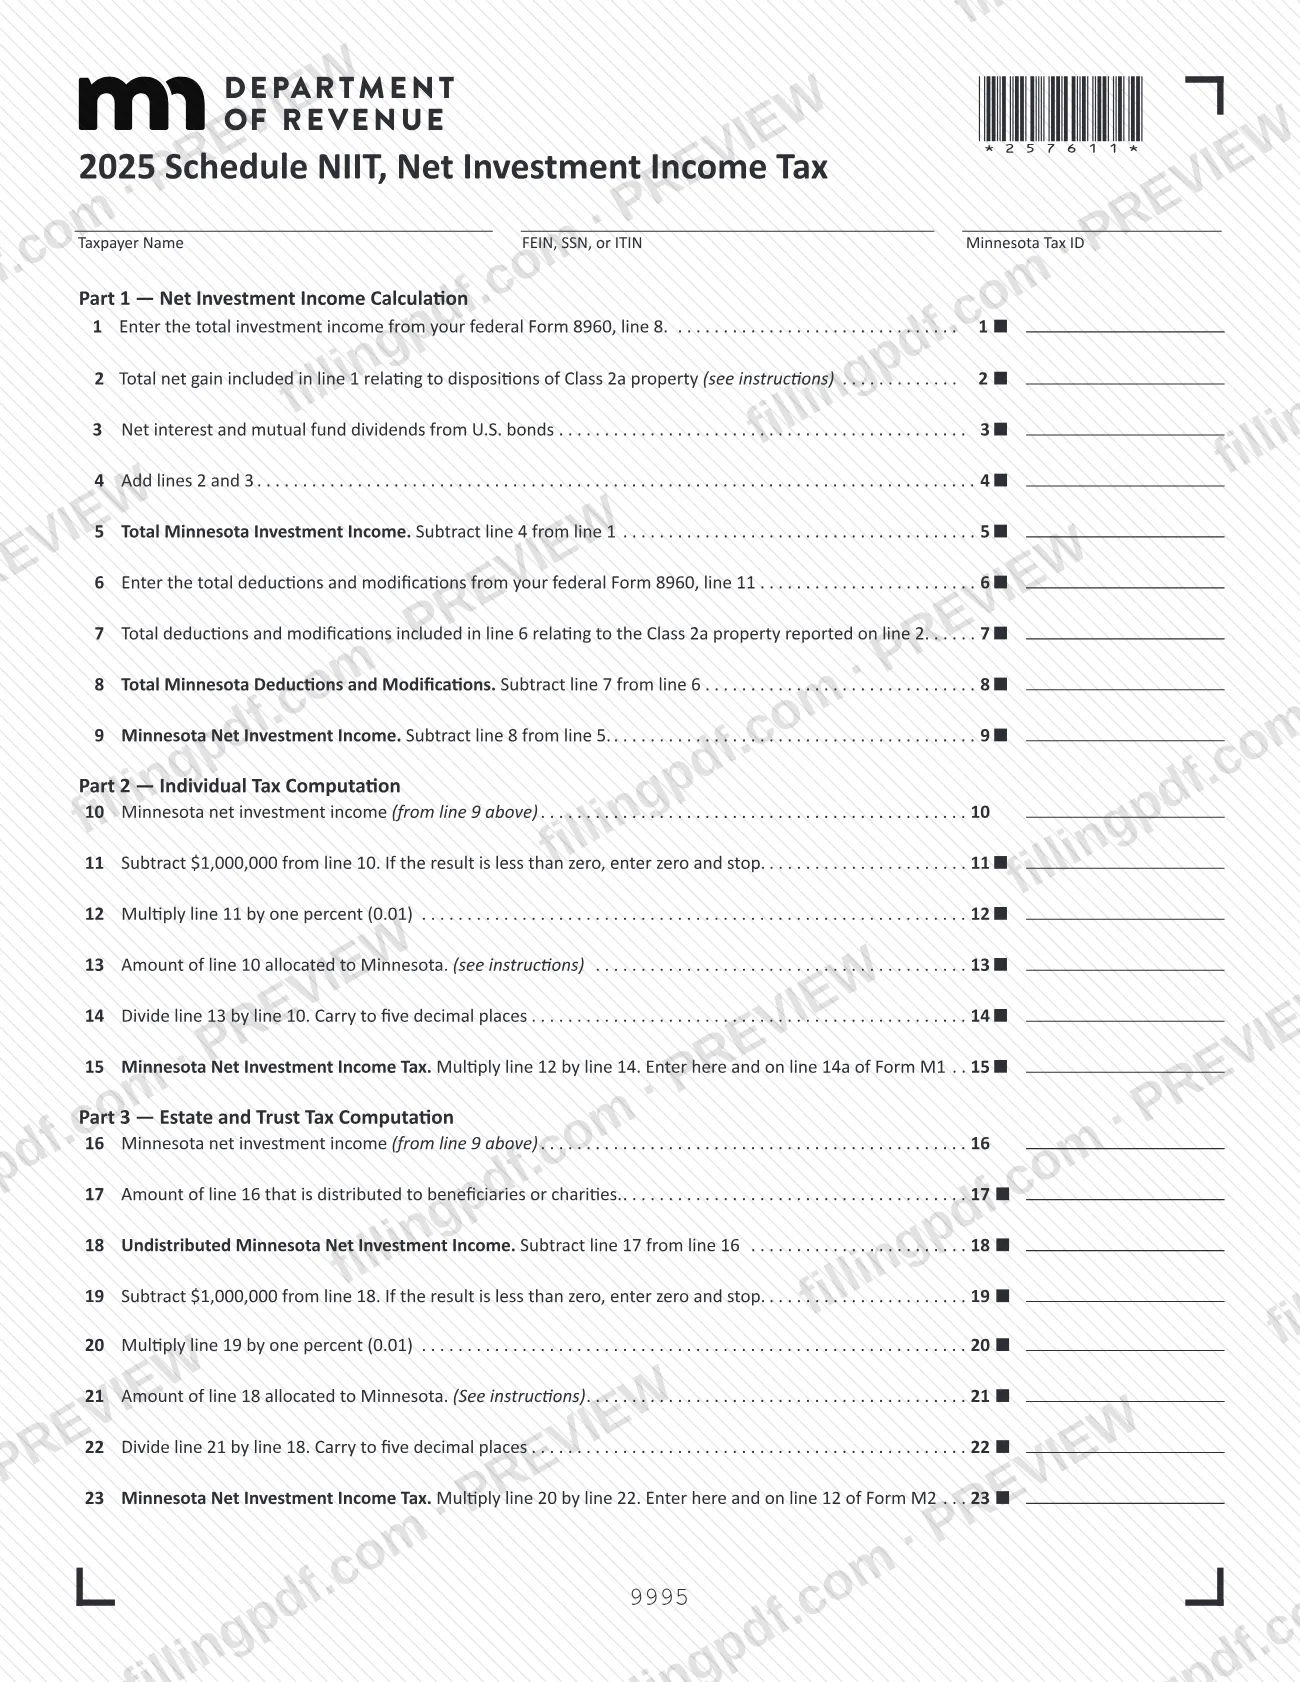
2025 Schedule NIIT, Net Investment Income Tax, is the Minnesota Department of Revenue schedule for tax year 2025 on which an individual, estate or trust determines its Minnesota net investment income and calculates any Minnesota net investment income tax owed.
The schedule has three parts. Part 1 starts from two figures on your federal Form 8960 (total investment income from line 8 and deductions and modifications from line 11) and adjusts them to arrive at Minnesota net investment income on line 9. Part 2 is the tax computation for individuals who file Form M1. Part 3 is the computation for estates and trusts that file Form M2.
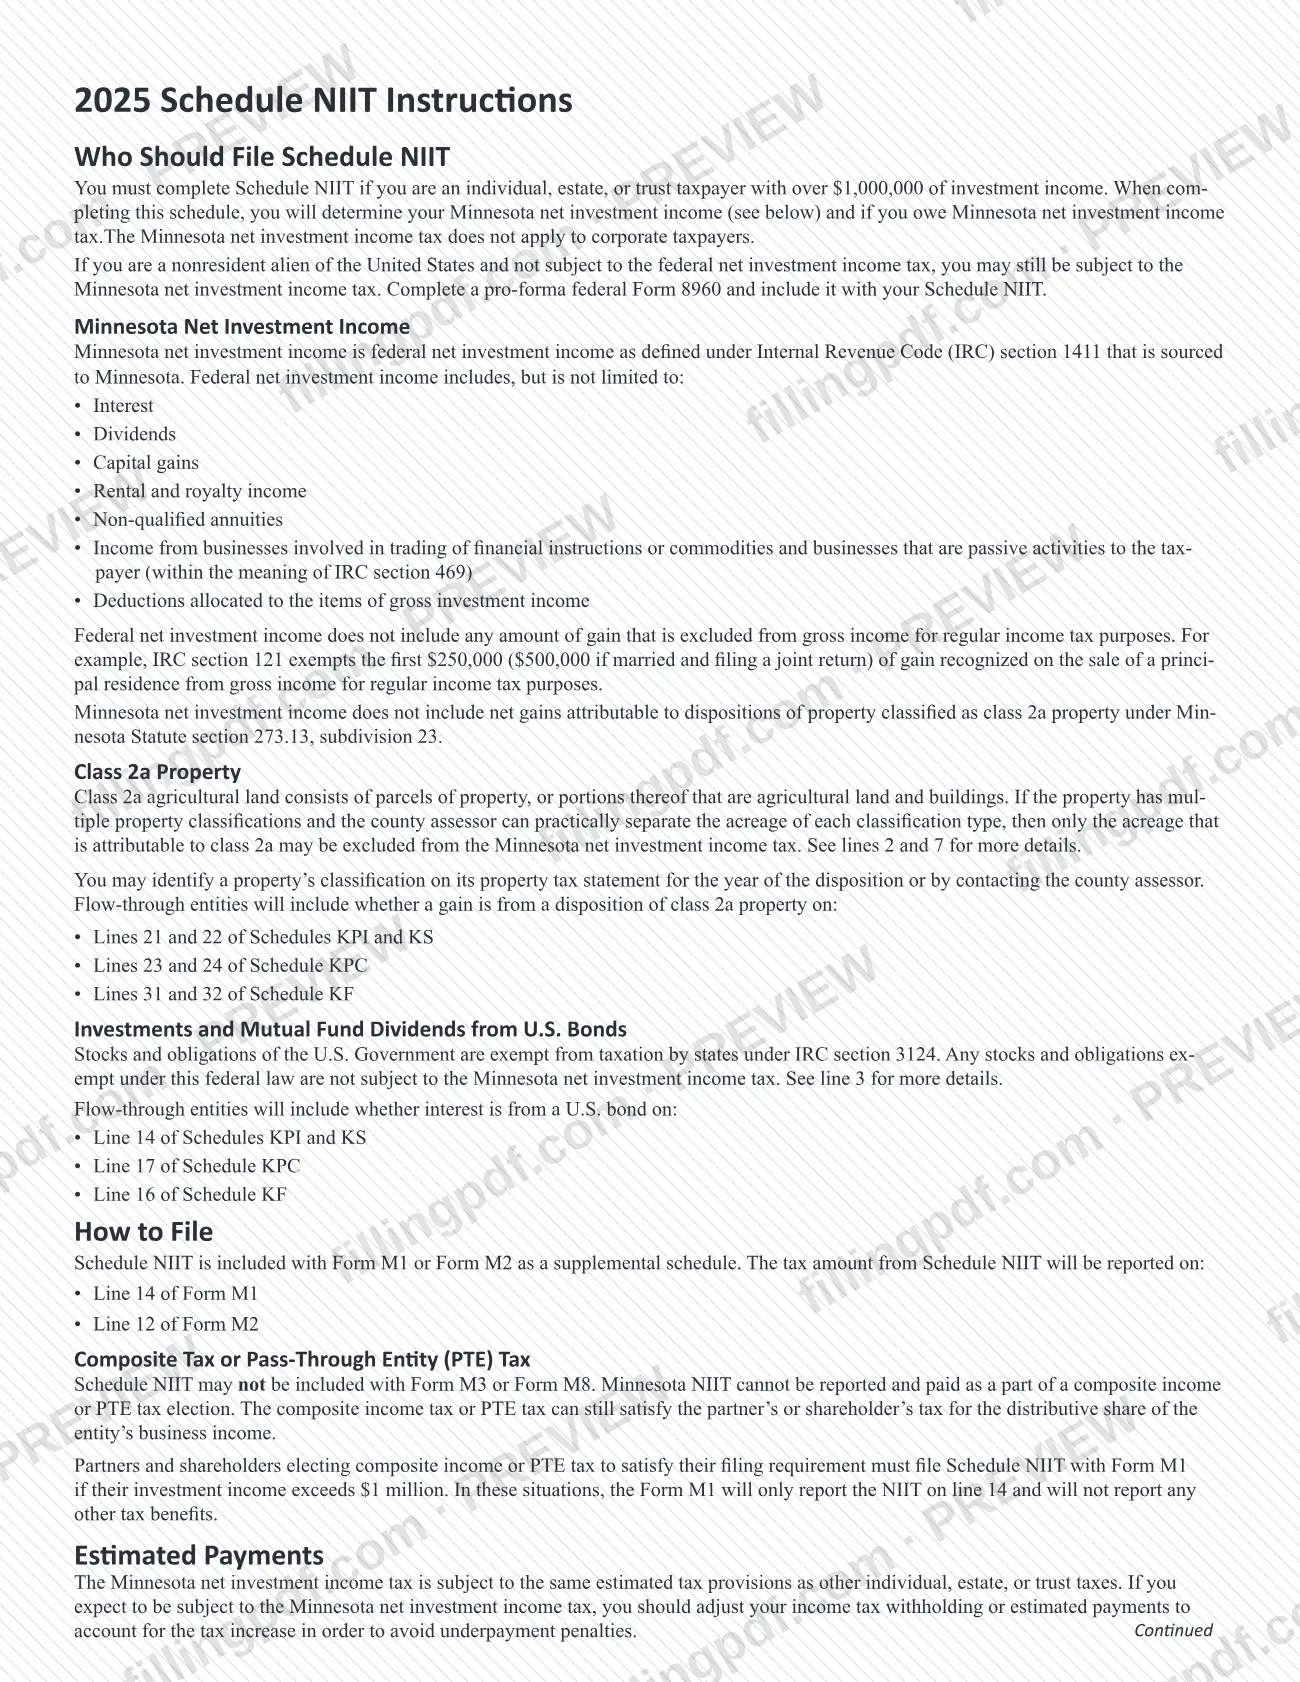
Minnesota net investment income is federal net investment income, as defined in Internal Revenue Code (IRC) section 1411, that is sourced to Minnesota. It includes interest, dividends, capital gains, rental and royalty income, non-qualified annuities and income from certain trading and passive businesses, less deductions allocated to those items. Three things are left out: gain that is excluded from gross income for regular income tax purposes, net gains from dispositions of class 2a property under Minnesota Statute section 273.13, subdivision 23, and certain interest and mutual fund dividends from U.S. bonds.
Schedule NIIT is not a return. It is a supplemental schedule included with Form M1 or Form M2, and the tax it produces is carried to those forms. The tax does not apply to corporate taxpayers.
Who needs to file Schedule NIIT?
You must complete Schedule NIIT if you are an individual, estate or trust taxpayer with over $1,000,000 of investment income.
- Individuals who file Form M1 complete Parts 1 and 2 and skip Part 3.
- Estates and trusts that file Form M2 complete Parts 1 and 3 and skip Part 2.
- Nonresident aliens of the United States who are not subject to the federal net investment income tax may still owe the Minnesota tax. They complete a pro-forma federal Form 8960 and include it with Schedule NIIT.
- Partners and shareholders who elect composite income tax or pass-through entity (PTE) tax to satisfy their filing requirement must still file Schedule NIIT with Form M1 if their investment income exceeds $1 million. Their Form M1 then reports only the NIIT on line 14.
Do not use this schedule if you are a corporate taxpayer: the Minnesota net investment income tax does not apply to corporations. Schedule NIIT may not be included with Form M3 or Form M8. If the result on line 11 (individuals) or line 19 (estates and trusts) is zero or less, you stop there: you are not subject to the tax.
When to file Schedule NIIT
Schedule NIIT has no due date of its own: it is included with Form M1 or Form M2 as a supplemental schedule, so it is completed and submitted whenever that return is filed. You complete it when your investment income is over $1,000,000.
The tax is subject to the same estimated tax provisions as other individual, estate and trust taxes. If you expect to owe the Minnesota net investment income tax, the instructions say to adjust your income tax withholding or estimated payments for the increase, so you avoid underpayment penalties.
Partners and shareholders who satisfy their filing requirement through a composite income or PTE tax election file Schedule NIIT with their Form M1 when investment income exceeds $1 million.
Documents you need
- Pro-forma federal Form 8960, if you are a nonresident alien of the United States who is not subject to the federal net investment income tax; include it with Schedule NIIT.
- An attachment showing the calculation of the amount on line 13, the part of line 10 allocated to Minnesota (individuals completing Part 2).
- An attachment showing the calculation of the amount on line 21, the part of line 18 allocated to Minnesota (estates and trusts completing Part 3).
How to fill out Schedule NIIT
Enter taxpayer name and ID numbers
At the top, enter the taxpayer name, your FEIN, SSN or ITIN, and your Minnesota Tax ID.
Copy federal investment income
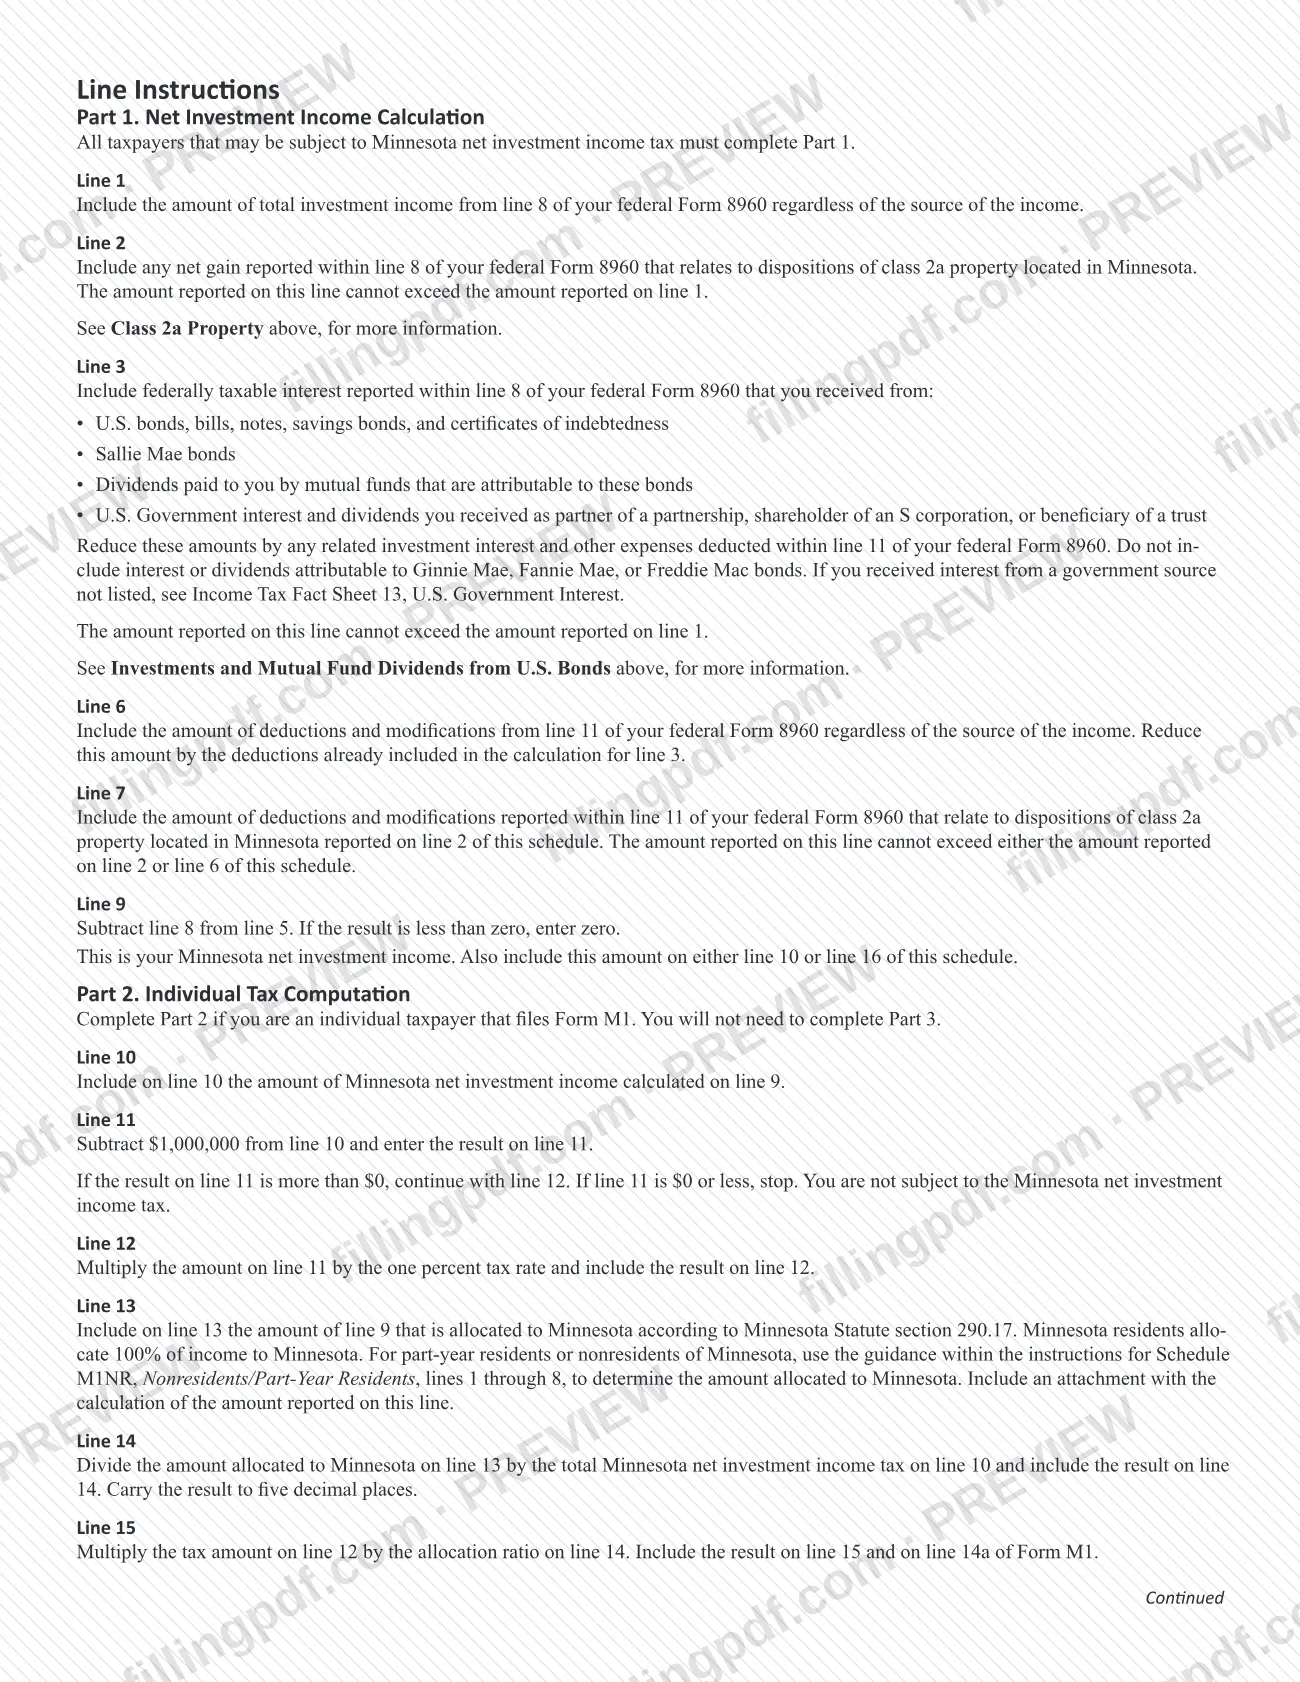
Line 1: enter total investment income from line 8 of your federal Form 8960, regardless of where the income was sourced. Nonresident aliens not subject to the federal tax use a pro-forma Form 8960.
Remove class 2a gains and U.S. bond interest
Line 2: net gain from dispositions of class 2a property located in Minnesota, not more than line 1. Line 3: net interest and mutual fund dividends from U.S. bonds, not more than line 1. Add them on line 4 and subtract line 4 from line 1 on line 5.
Enter deductions and modifications
Line 6: deductions and modifications from line 11 of federal Form 8960, reduced by the deductions already used for line 3. Line 7: the part tied to the class 2a property on line 2, not more than line 2 or line 6. Subtract line 7 from line 6 on line 8.
Figure Minnesota net investment income
Line 9: subtract line 8 from line 5. If the result is less than zero, enter zero. Then carry this amount to line 10 (individuals) or line 16 (estates and trusts).
Start the tax computation for individuals
If you file Form M1, complete Part 2 only. Line 10: copy line 9. Line 11: subtract $1,000,000 from line 10; if the result is less than zero, enter zero and stop.
Compute the individual tax and allocation
Line 12: multiply line 11 by the tax rate printed on the form. Line 13: the part of line 10 allocated to Minnesota; residents allocate 100%, others follow the Schedule M1NR instructions and attach the calculation. Line 14: divide line 13 by line 10 to five decimal places.
Enter the individual Minnesota tax
Line 15: multiply line 12 by line 14. Enter the result here and on line 14a of Form M1.
Figure undistributed income for estates and trusts
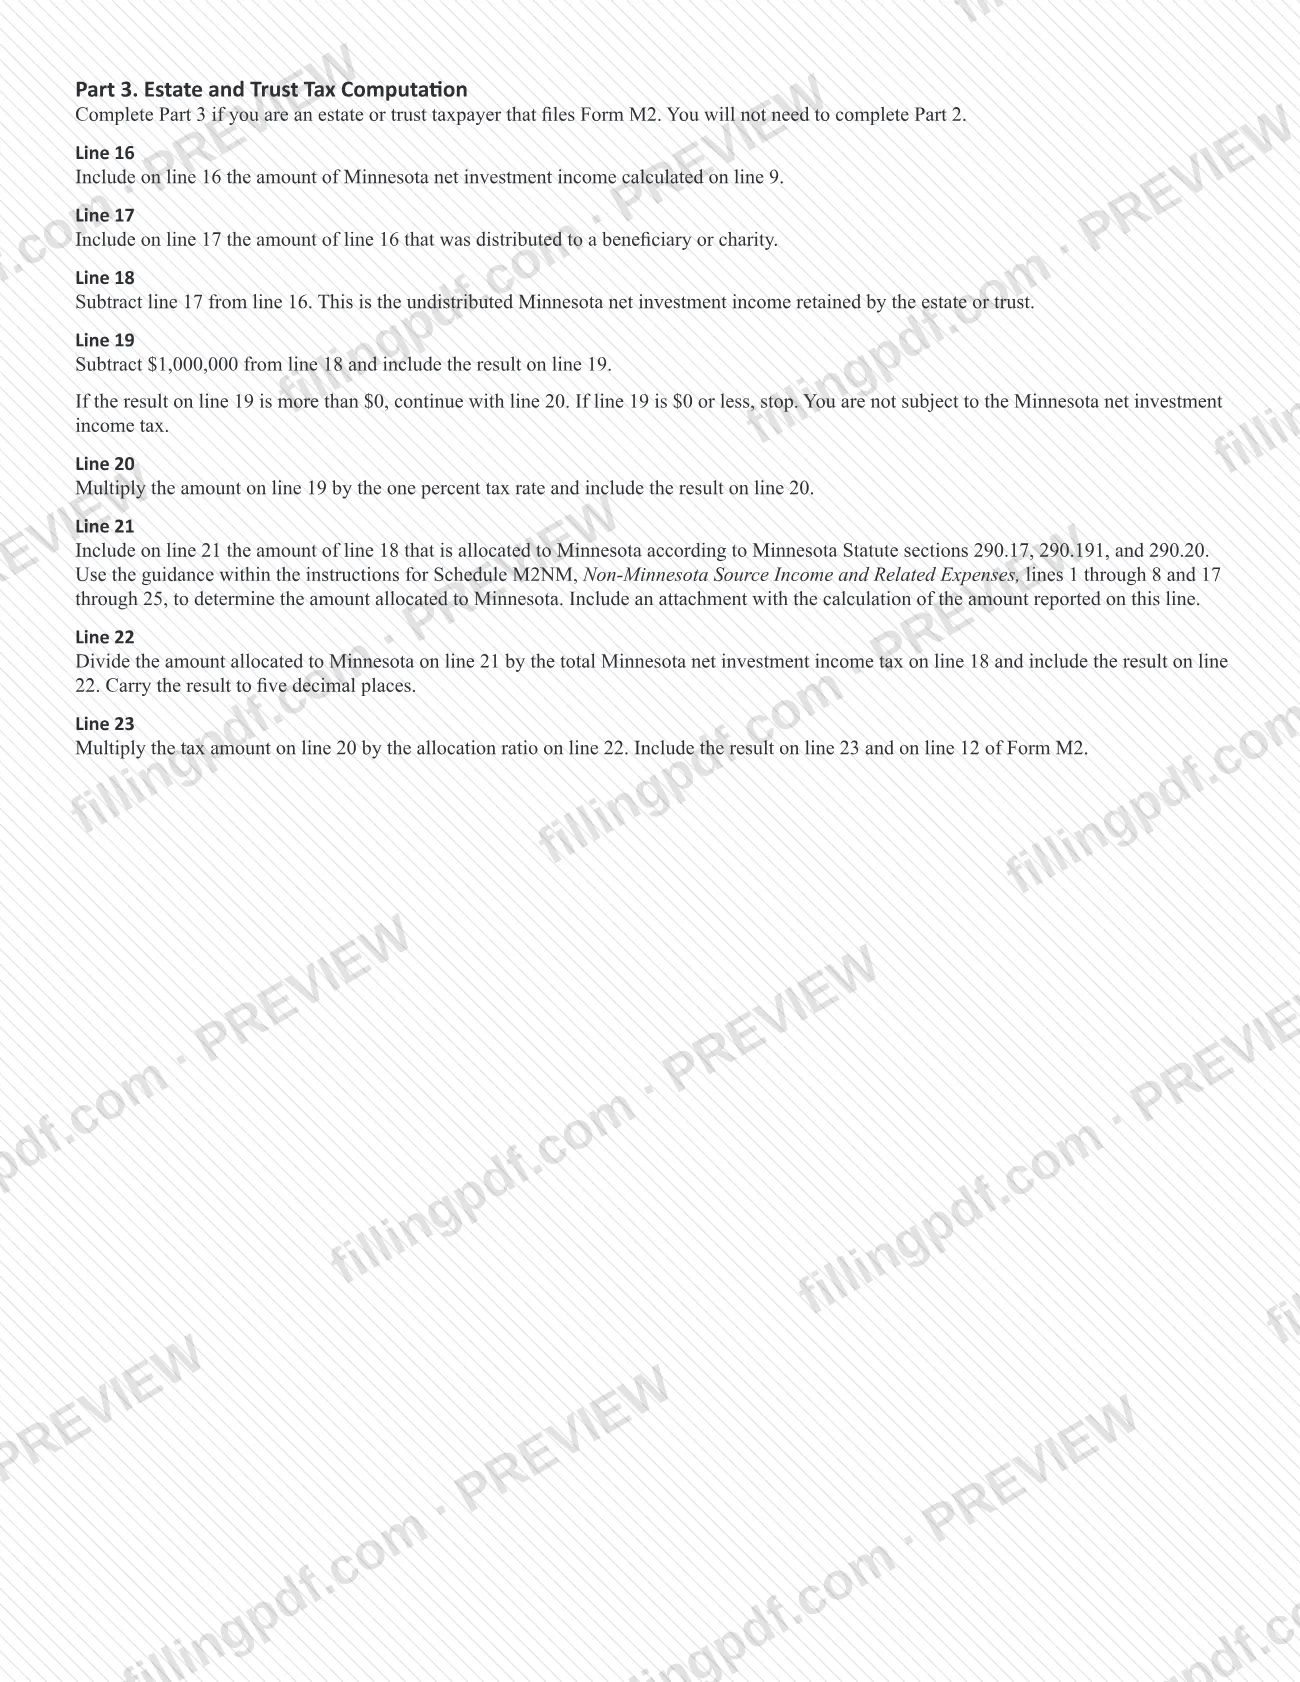
If you file Form M2, complete Part 3 only. Line 16: copy line 9. Line 17: the part of line 16 distributed to beneficiaries or charities. Line 18: subtract line 17 from line 16.
Apply the threshold for estates and trusts
Line 19: subtract $1,000,000 from line 18; if the result is less than zero, enter zero and stop. Line 20: multiply line 19 by the tax rate printed on the form.
Allocate and enter the estate or trust tax
Line 21: the part of line 18 allocated to Minnesota, using the Schedule M2NM instructions, with an attached calculation. Line 22: divide line 21 by line 18 to five decimal places. Line 23: multiply line 20 by line 22 and enter it here and on line 12 of Form M2.
Review and download the completed PDF
Check that you completed only the Part that applies to you and that every line matches your federal Form 8960. Download or print the completed PDF from FillingPDF and include it, with any attachments, with Form M1 or Form M2.
How to submit Schedule NIIT
Schedule NIIT is not filed on its own. It is submitted as part of your Minnesota return, with one of two forms:
- Form M1: individuals include the schedule with Form M1 and enter the tax from line 15 on line 14a of Form M1.
- Form M2: estates and trusts include the schedule with Form M2 and enter the tax from line 23 on line 12 of Form M2.
Send the package the way you send that return; the schedule prints no address, portal or separate channel of its own. Do not include Schedule NIIT with Form M3 or Form M8: Minnesota NIIT cannot be reported and paid as part of a composite income or PTE tax election.
Attach what the lines require: a calculation of the amount on line 13 (individuals) or line 21 (estates and trusts), and a pro-forma federal Form 8960 if you are a nonresident alien not subject to the federal tax.
FillingPDF lets you fill out and download the PDF; submission follows the Minnesota Department of Revenue channels for Form M1 or Form M2.
Common mistakes to avoid
- Including Schedule NIIT with Form M3 or Form M8; it goes only with Form M1 or Form M2, and the tax cannot be paid as part of a composite income or PTE tax election.
- Entering an amount on line 2 or line 3 that is larger than line 1; the instructions say neither line can exceed the amount on line 1.
- Including interest or dividends from Ginnie Mae, Fannie Mae or Freddie Mac bonds on line 3, which the instructions say to leave out.
- Not reducing line 6 by the deductions already included in the calculation for line 3.
- Entering on line 7 more than line 2 or line 6; the instructions cap it at the smaller of the two.
- Completing both Part 2 and Part 3; individuals filing Form M1 skip Part 3, and estates and trusts filing Form M2 skip Part 2.
- Continuing past line 11 or line 19 when the result is zero or less; at that point you stop, because you are not subject to the tax.
- Leaving out the attachment showing how the line 13 or line 21 amount was calculated.
- Filing as a corporation; the Minnesota net investment income tax does not apply to corporate taxpayers.
Frequently asked questions
What is Minnesota Schedule NIIT?
Schedule NIIT is the Minnesota Department of Revenue schedule for the Minnesota net investment income tax. It starts from your federal Form 8960, adjusts it to Minnesota net investment income and calculates the tax. It is included with Form M1 or Form M2.
Do I owe Minnesota net investment income tax?
Only if you are an individual, estate or trust with over $1,000,000 of investment income and your Minnesota net investment income is more than $1,000,000. If line 11 (individuals) or line 19 (estates and trusts) is zero or less, you stop and owe none. The tax does not apply to corporations.
Where do I report the tax from Schedule NIIT?
Individuals enter the tax from line 15 on line 14a of Form M1. Estates and trusts enter the tax from line 23 on line 12 of Form M2. The schedule itself is included with that return as a supplemental schedule.
Can I include Schedule NIIT with Form M3 or Form M8?
No. Schedule NIIT may not be included with Form M3 or Form M8, and the Minnesota NIIT cannot be reported or paid through a composite income or PTE tax election. Partners and shareholders in that situation file Schedule NIIT with Form M1 if their investment income exceeds $1 million.
What is class 2a property on Schedule NIIT?
Class 2a property is agricultural land and buildings, as classified under Minnesota Statute section 273.13, subdivision 23. Net gains from selling it are excluded from Minnesota net investment income on lines 2 and 7. Check the property tax statement for the year of the sale or ask the county assessor.
Is there a separate due date for Schedule NIIT?
No. It travels with Form M1 or Form M2 and is submitted when that return is. The instructions do advise adjusting withholding or estimated payments if you expect to owe the tax, to avoid underpayment penalties.
Do nonresident aliens have to complete Schedule NIIT?
They may. A nonresident alien who is not subject to the federal net investment income tax can still owe the Minnesota tax. In that case complete a pro-forma federal Form 8960 and include it with Schedule NIIT.
What do I enter on line 13 if I am not a Minnesota resident?
Enter the part of your Minnesota net investment income allocated to Minnesota under Minnesota Statute section 290.17. Part-year residents and nonresidents follow lines 1 through 8 of the Schedule M1NR instructions and attach the calculation. Residents allocate 100% of income to Minnesota.
Can I fill out Schedule NIIT online on FillingPDF?
Yes. You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file anything with the Minnesota Department of Revenue; you submit the schedule with your Form M1 or Form M2.
Ready to fill out Schedule NIIT?
Fill out Schedule NIIT now