
Form AMTI, Alternative Minimum Tax (Calculation of Income) (2025), is the Minnesota Department of Revenue schedule that works out a corporation's alternative minimum tax income, starting from Minnesota net income on Form M4I. Corporations and designated filers that are not excluded use it to add adjustments, preferences and the adjusted current earnings (ACE) adjustment. On this page you can fill out the form online on FillingPDF and download or print the completed PDF; the form and its instructions are published by the Minnesota Department of Revenue.
Last updated
What is AMTI?
Form AMTI, Alternative Minimum Tax (Calculation of Income) (2025), also called Schedule AMTI, is the Minnesota Department of Revenue schedule on which a corporation or designated filer starts from Minnesota net income, adds alternative minimum tax adjustments and preferences, and arrives at its alternative minimum taxable income.
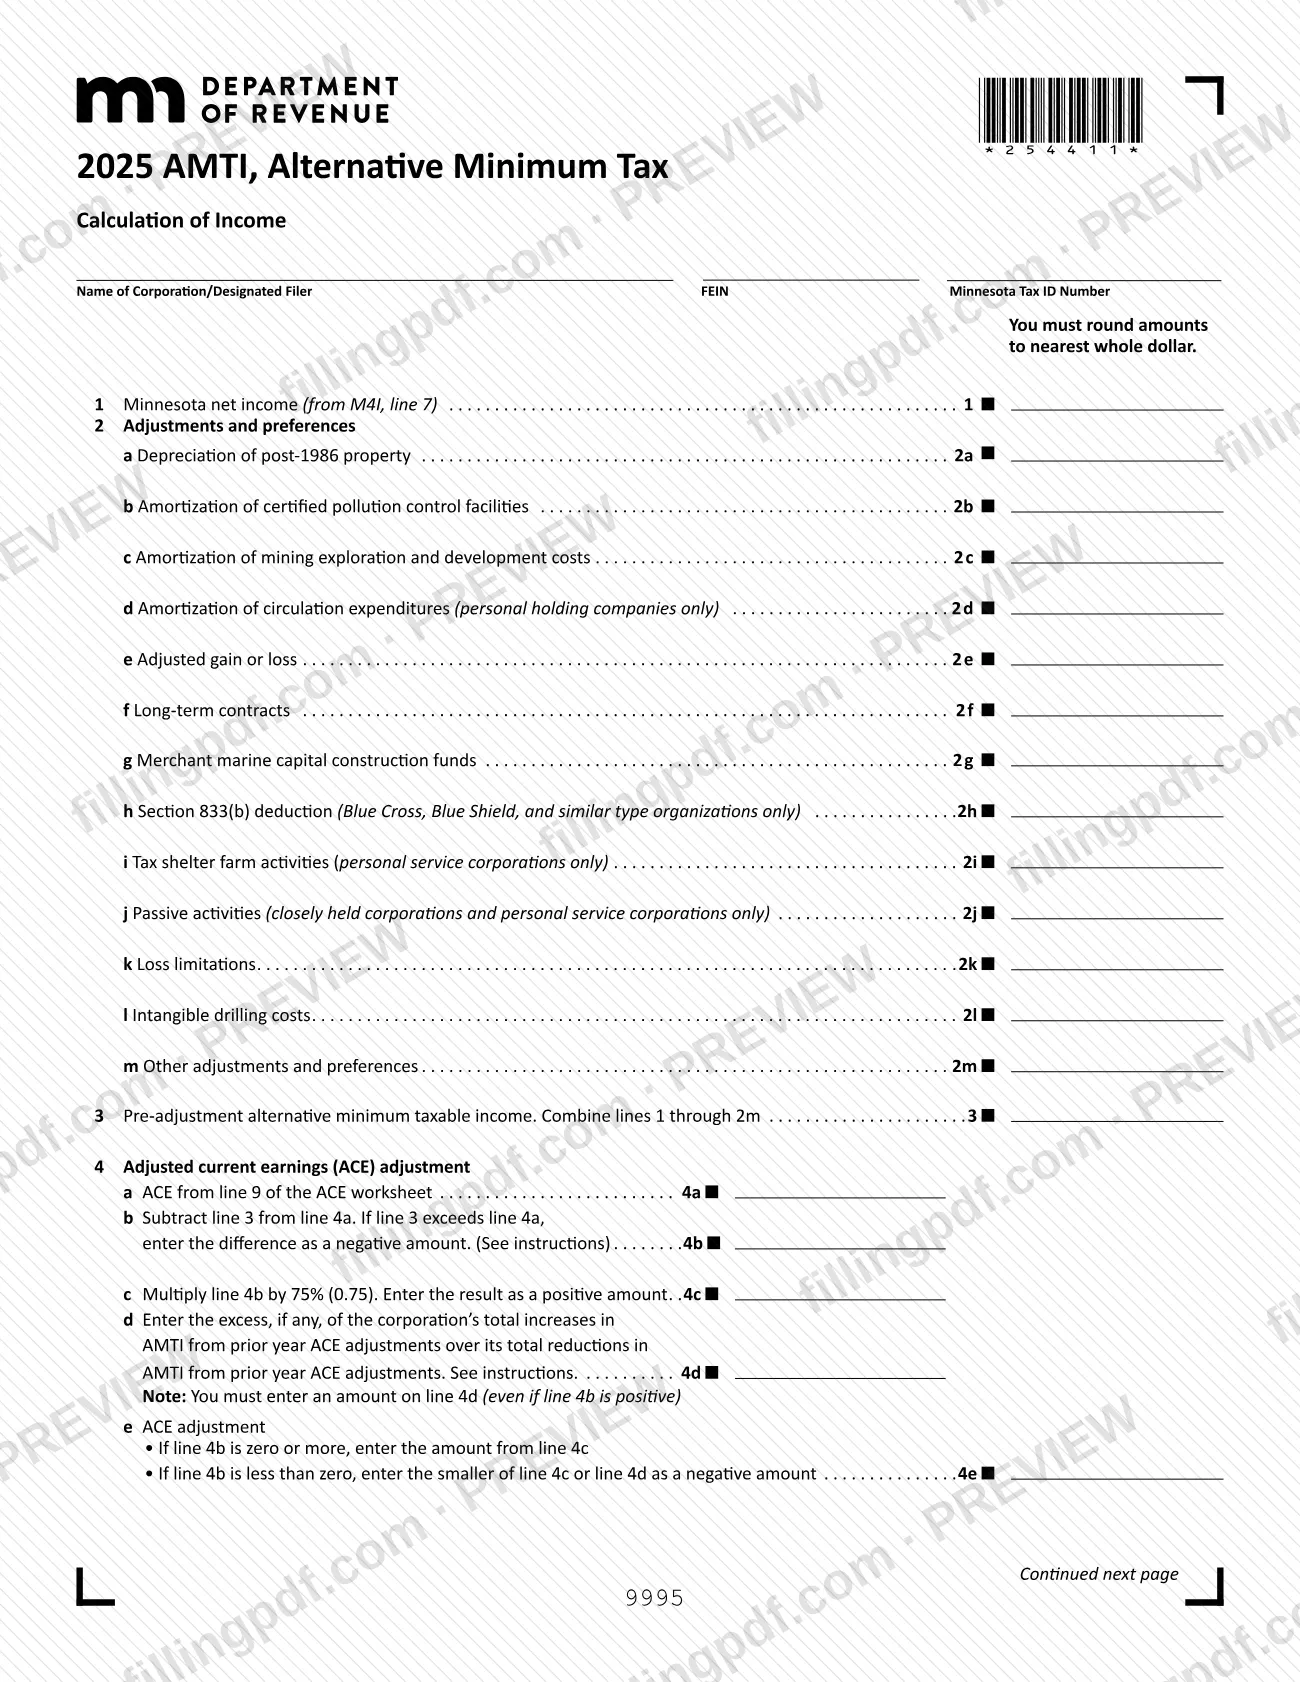
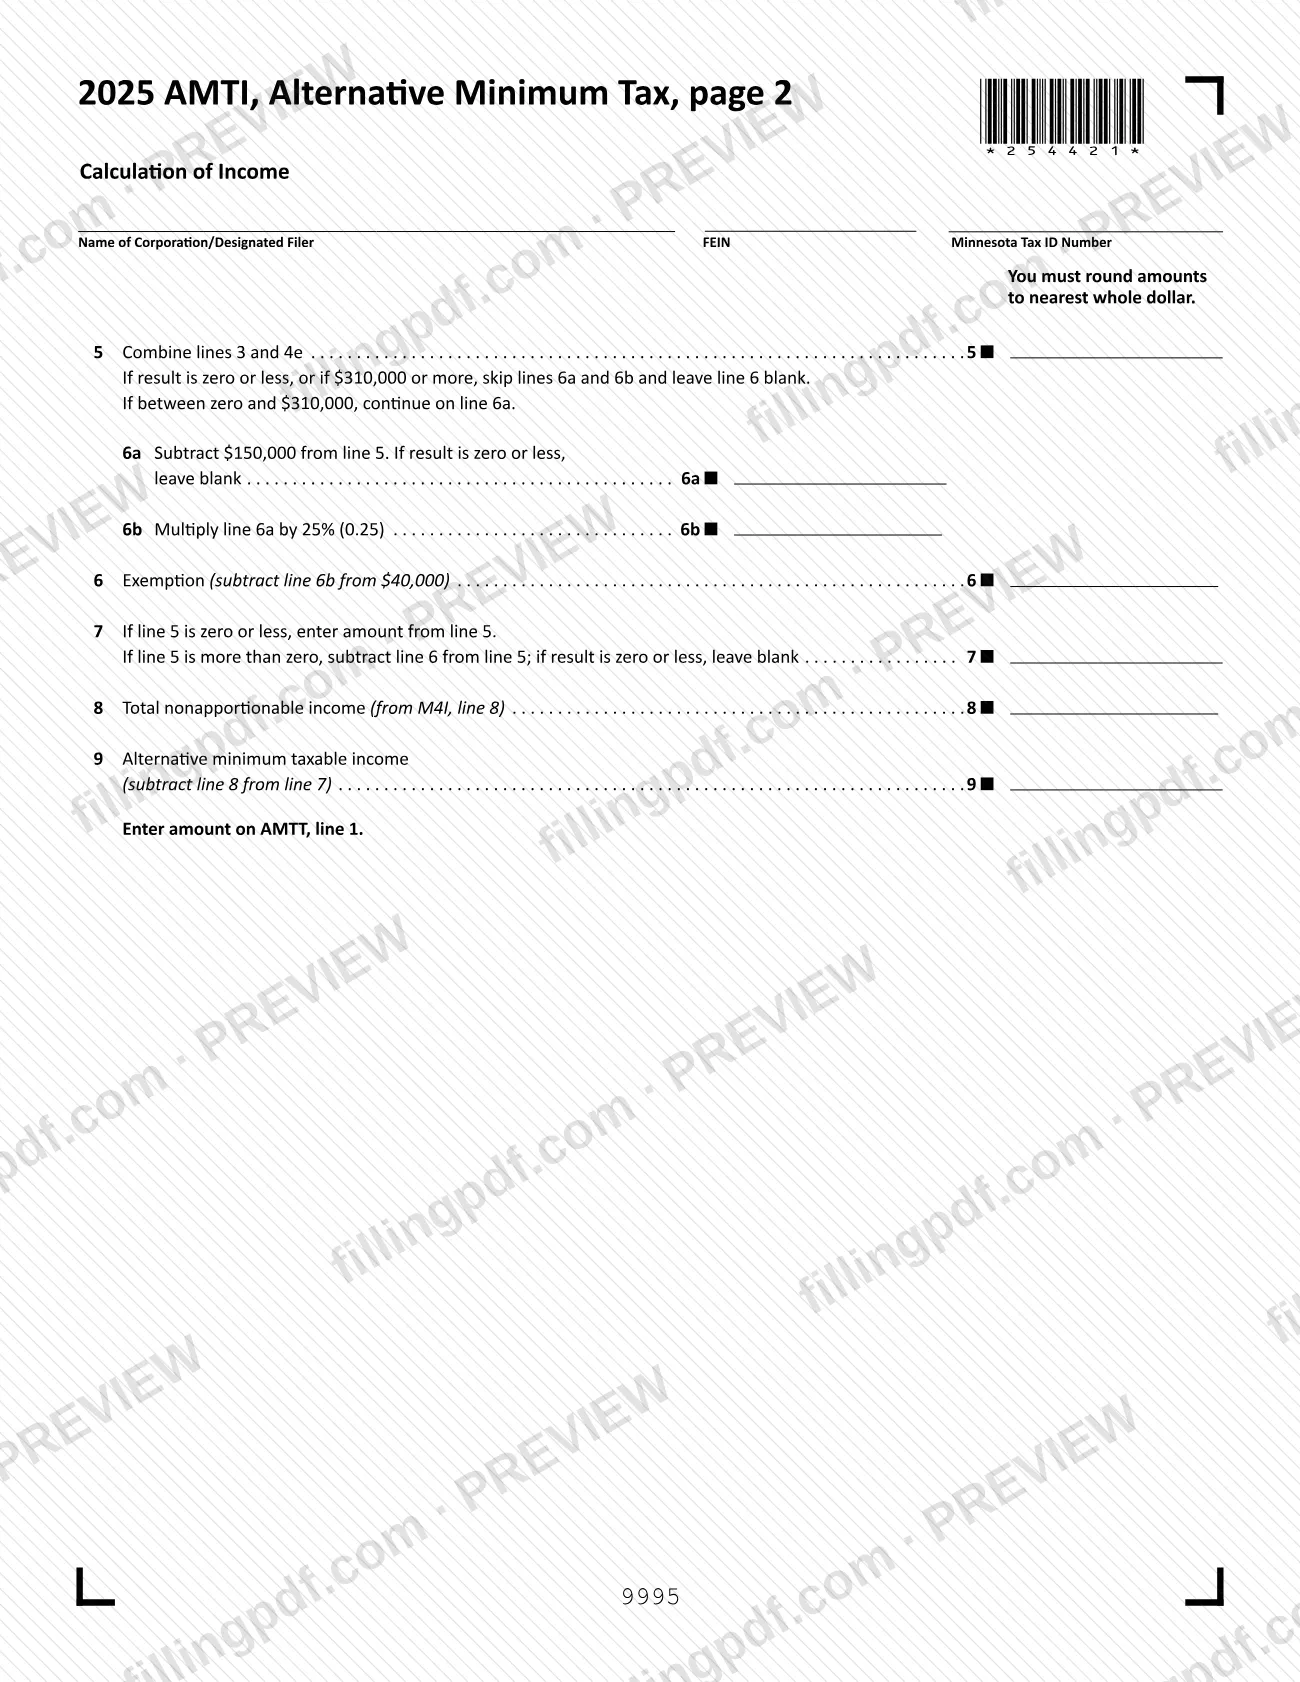
The form is built in steps. Line 1 takes Minnesota net income from Form M4I, line 7. Lines 2a through 2m list the adjustments and preferences, such as depreciation of post-1986 property, long-term contracts, passive activities, loss limitations and intangible drilling costs. Line 3 combines them into pre-adjustment alternative minimum taxable income. Lines 4a through 4e add the adjusted current earnings (ACE) adjustment, using line 9 of the ACE worksheet printed with the instructions. Lines 5 through 7 apply the exemption, line 8 subtracts total nonapportionable income from Form M4I, line 8, and line 9 gives the alternative minimum taxable income, which you enter on AMTT, line 1.
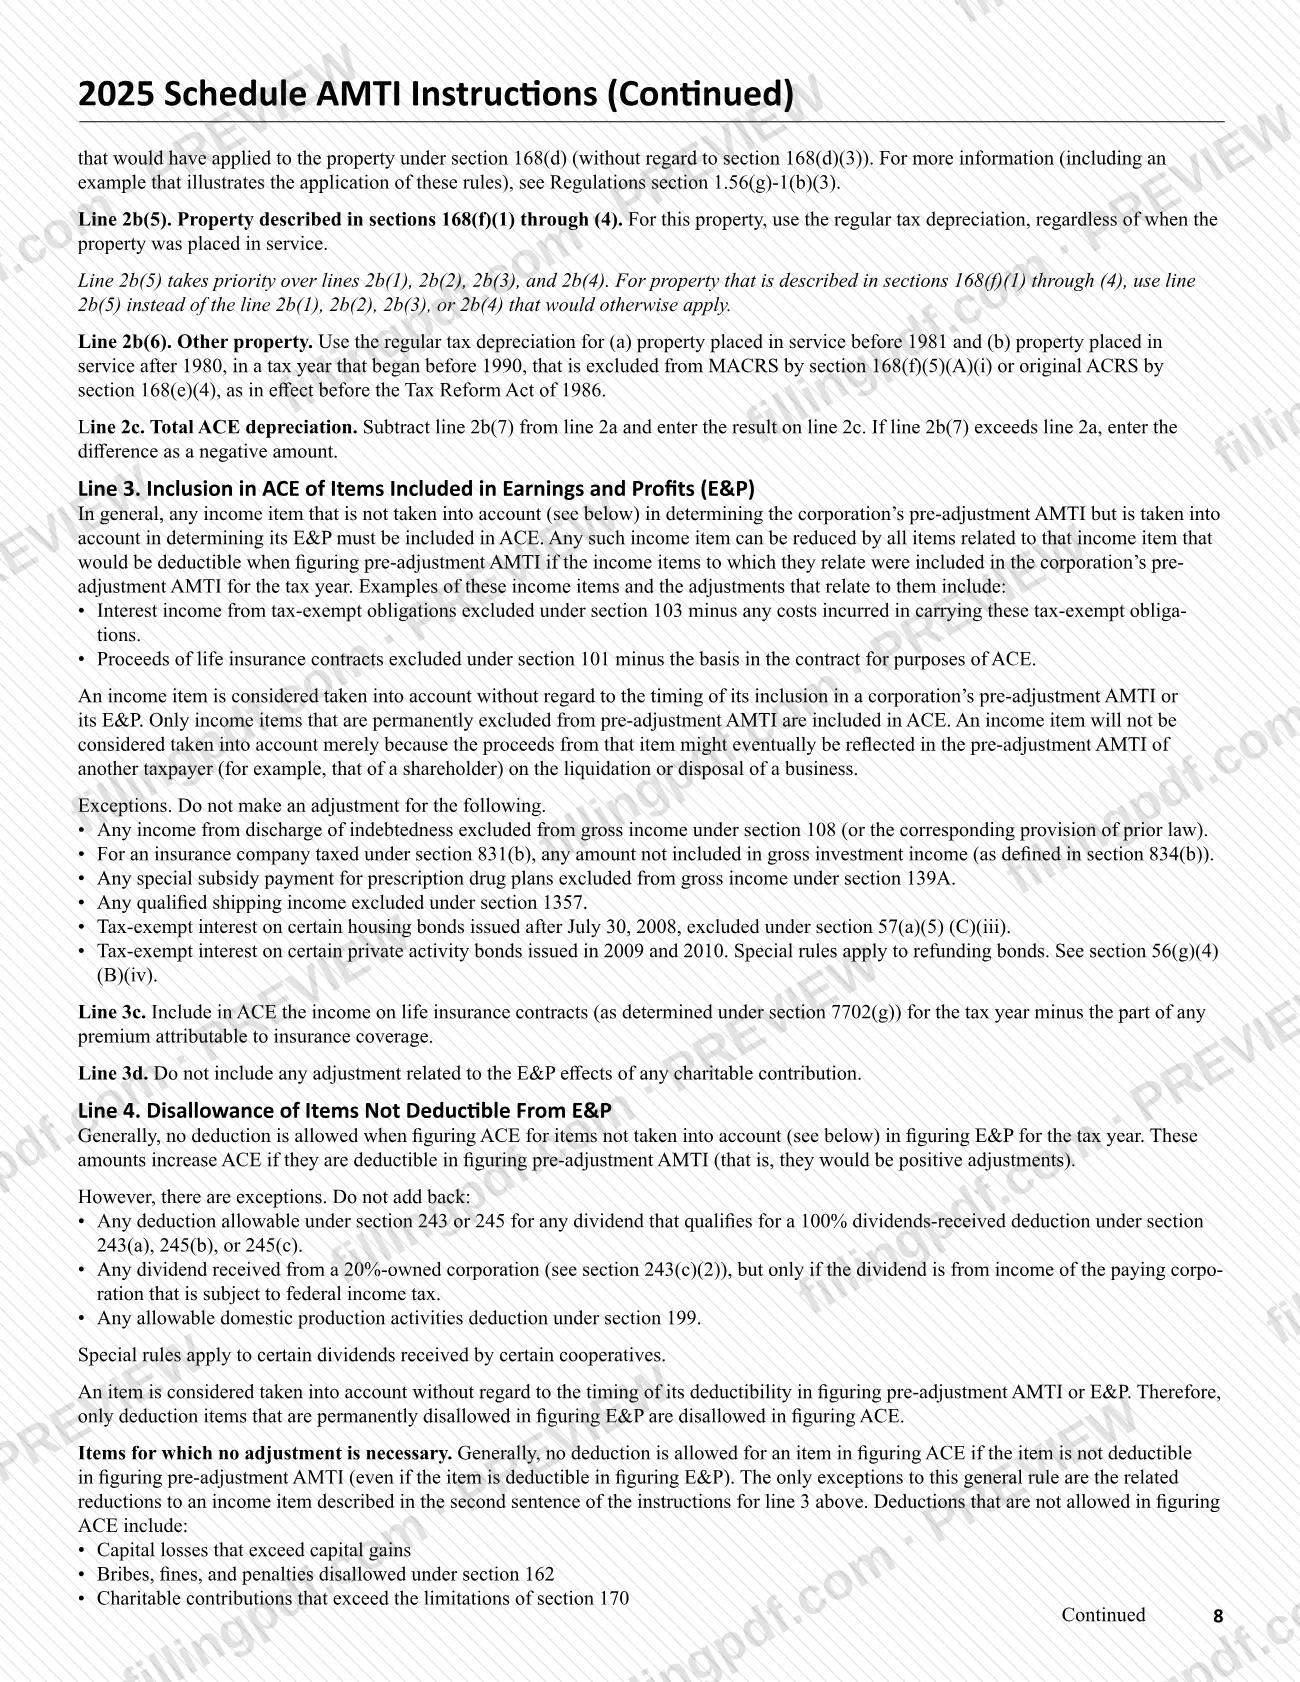
The instructions treat all code sections, regulations and publications as federal provisions as amended through December 16, 2016. Line 4d is carried from the 2024 Form 4626, which is a different form from this schedule.
The schedule does not compute the tax itself: it produces the income figure that goes to the AMTT form.
Who needs to file AMTI?
Corporations and designated filers that are subject to Minnesota alternative minimum tax complete Form AMTI. The instructions say you must file the schedule if you are not in an excluded category and your Minnesota net income (from Form M4I, line 7), combined with your adjustments and tax preferences (including adjusted current earnings), exceeds $40,000 or your allowable exemption amount.
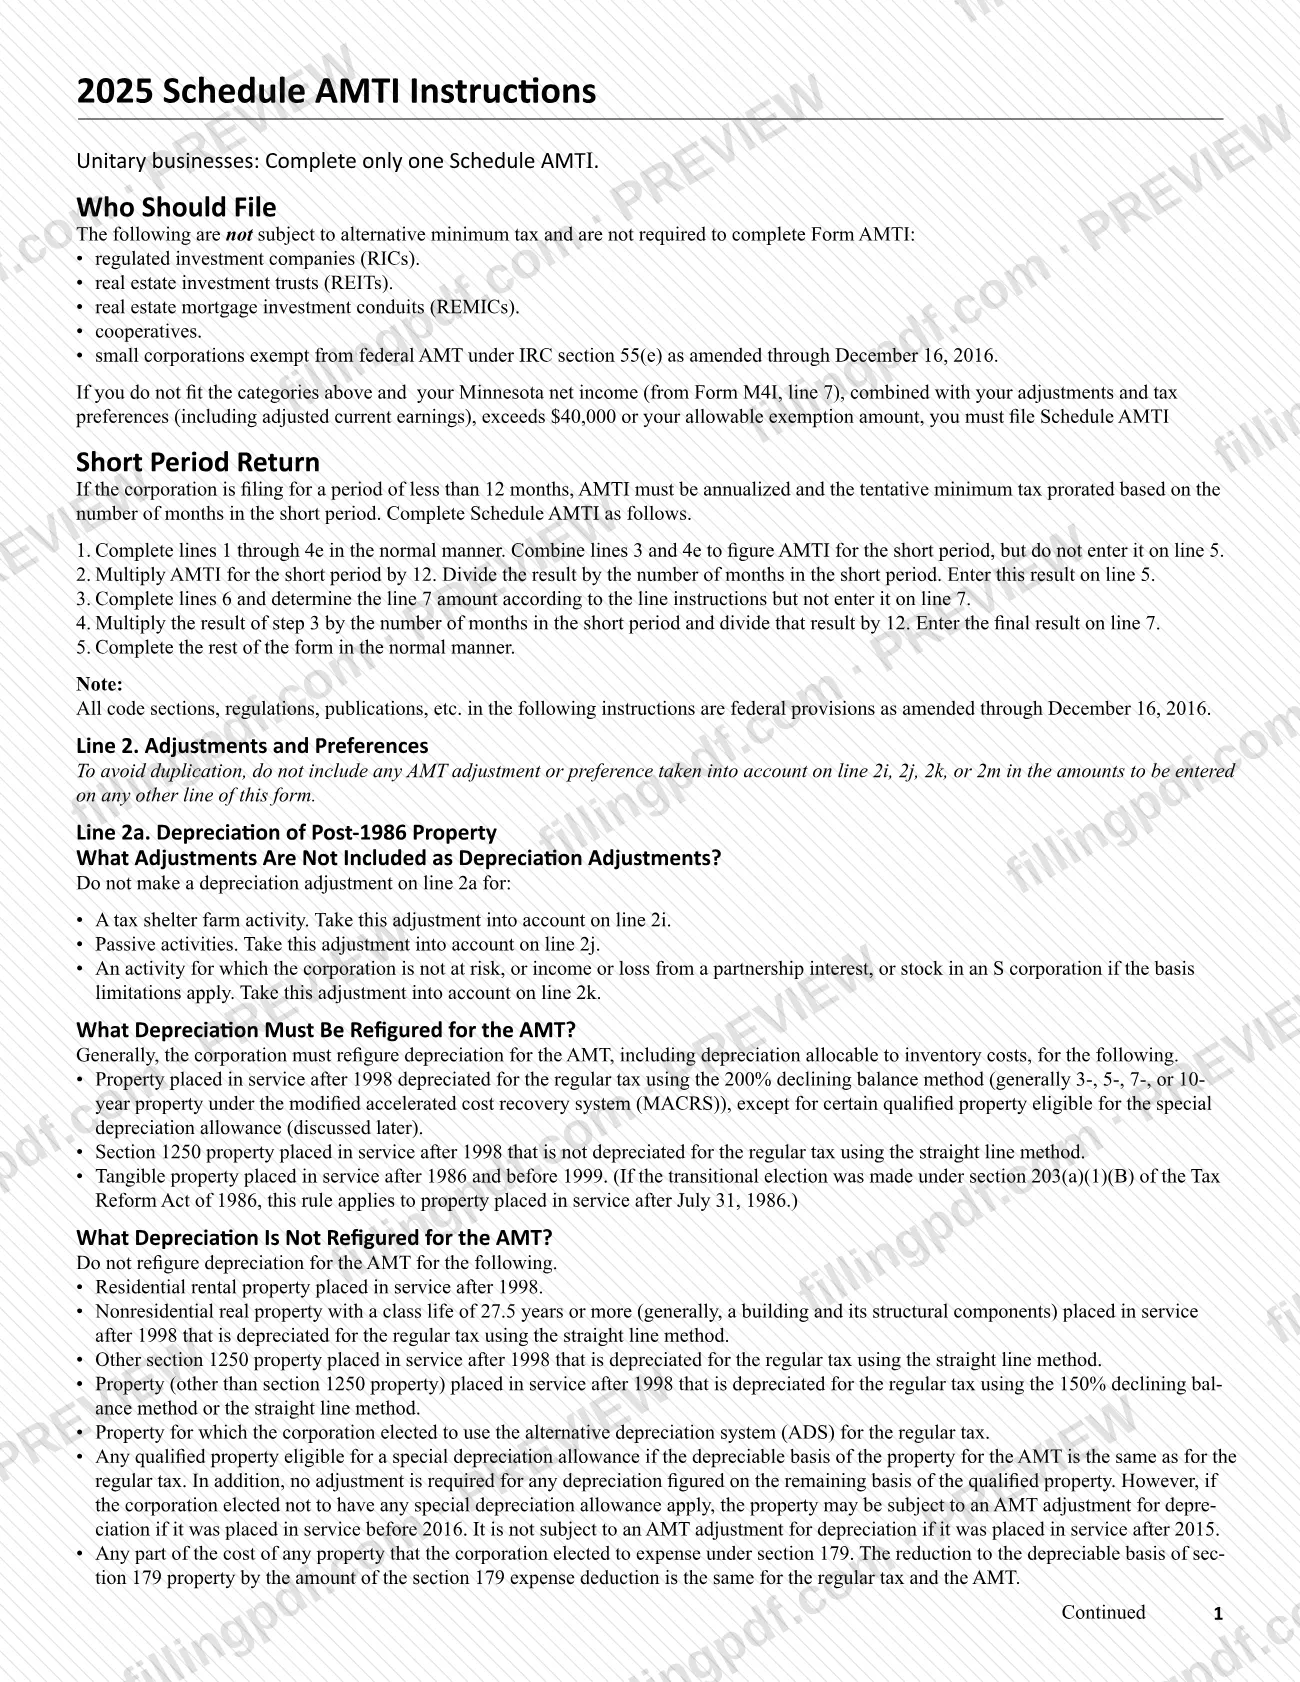
The following are not subject to alternative minimum tax and are not required to complete Form AMTI:
- regulated investment companies (RICs);
- real estate investment trusts (REITs);
- real estate mortgage investment conduits (REMICs);
- cooperatives;
- small corporations exempt from federal AMT under IRC section 55(e) as amended through December 16, 2016.
Unitary businesses complete only one Schedule AMTI.
Some lines apply to particular filers only: line 2d to personal holding companies, line 2h to Blue Cross, Blue Shield and similar organizations, line 2i to personal service corporations, and line 2j to closely held corporations and personal service corporations. The ACE adjustment on line 4 does not apply to a regulated investment company or a real estate investment trust. The instructions do not describe who may sign or file for another person.
When to file AMTI
Complete Form AMTI for 2025 when your Minnesota net income, combined with adjustments and tax preferences, exceeds $40,000 or your allowable exemption amount. No separate due date is printed on the schedule; it supports the alternative minimum tax computation, because line 9 is entered on AMTT, line 1.
If the corporation files for a period of less than 12 months, AMTI must be annualized and the tentative minimum tax prorated by the number of months in the short period. The instructions give a five-step method: complete lines 1 through 4e normally, multiply the short-period AMTI by 12 and divide by the number of months, enter that on line 5, then scale the line 7 amount back by the months divided by 12.
Keep records from year to year, such as a copy of Schedule AMTI completed at least through line 5, even in years when no AMT is owed, because line 4d depends on prior-year ACE adjustments.
Documents you need
- Form M4I: the amounts from line 7 (Minnesota net income) for line 1 and from line 8 (total nonapportionable income) for line 8.
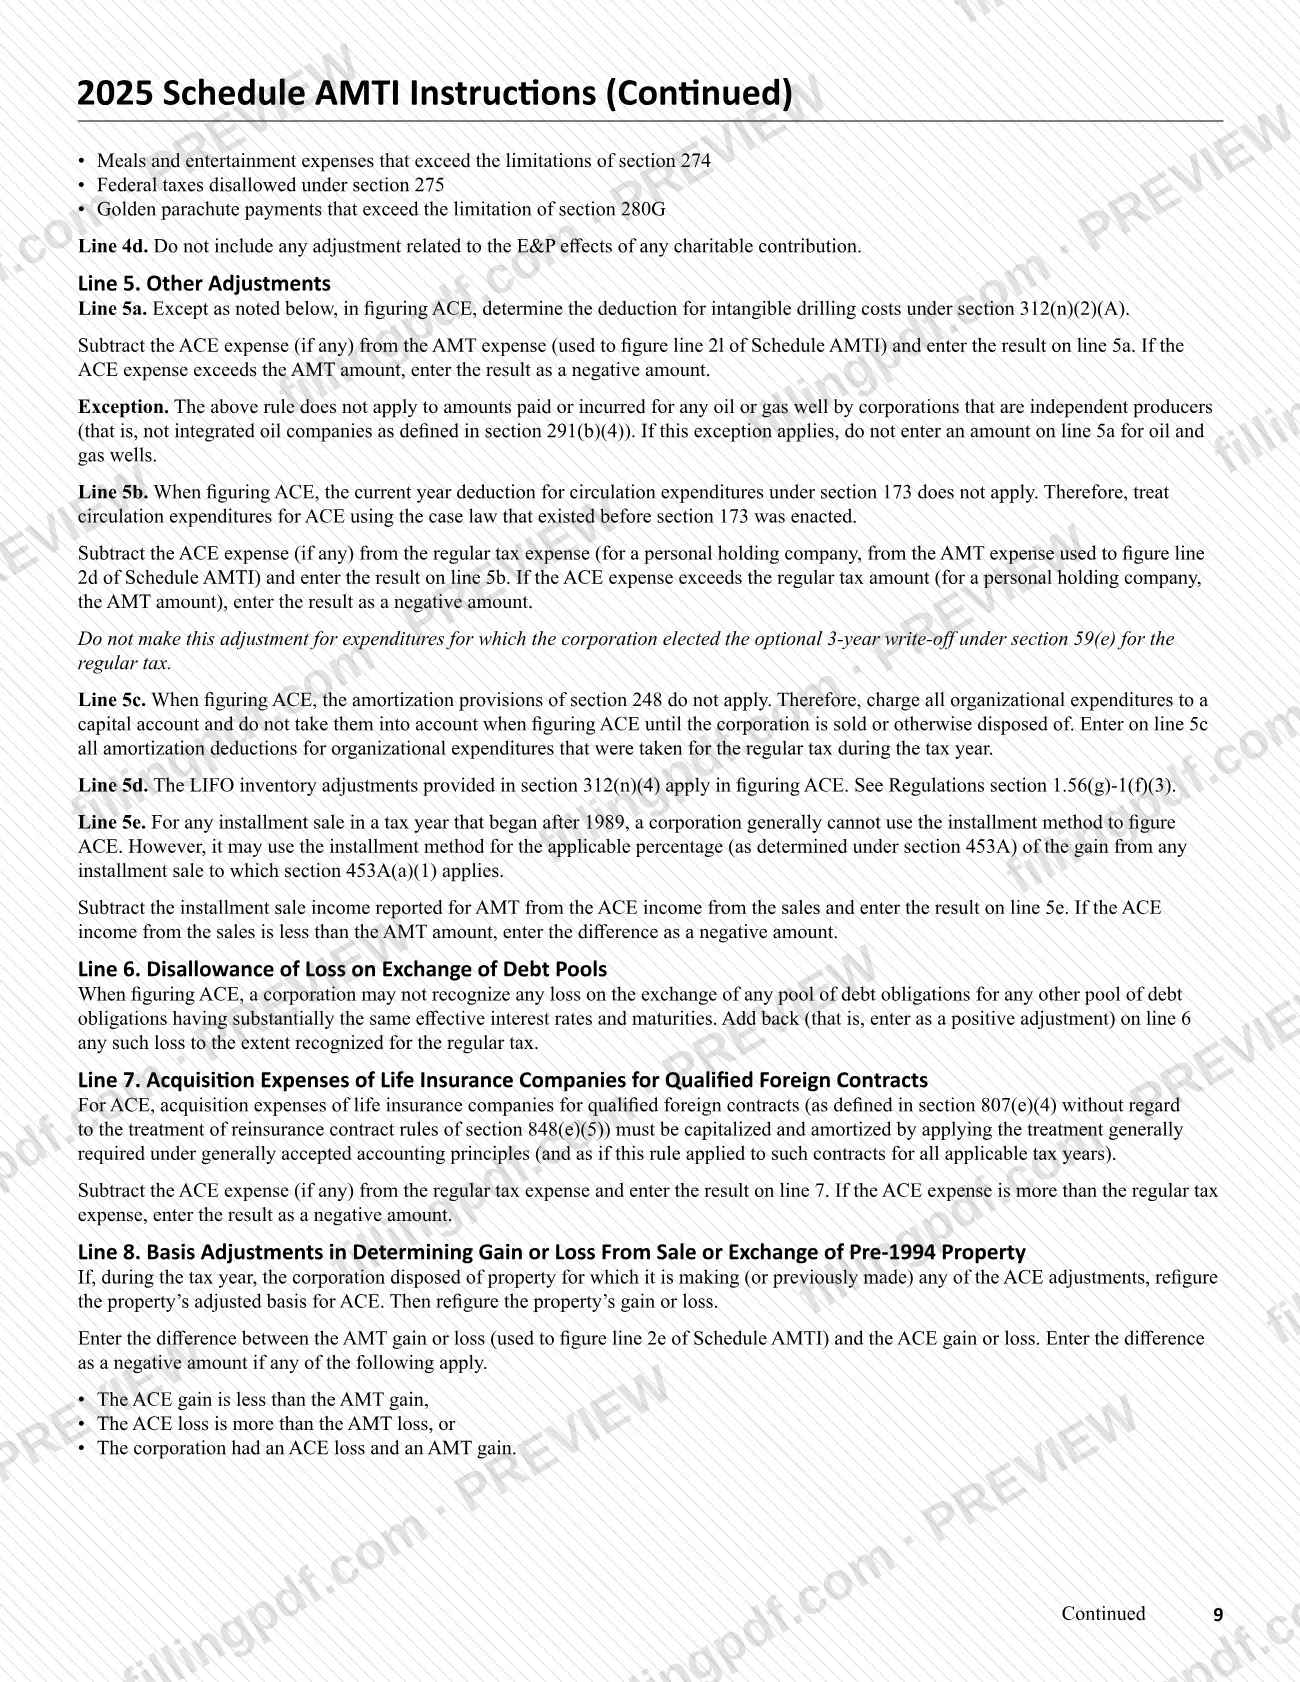
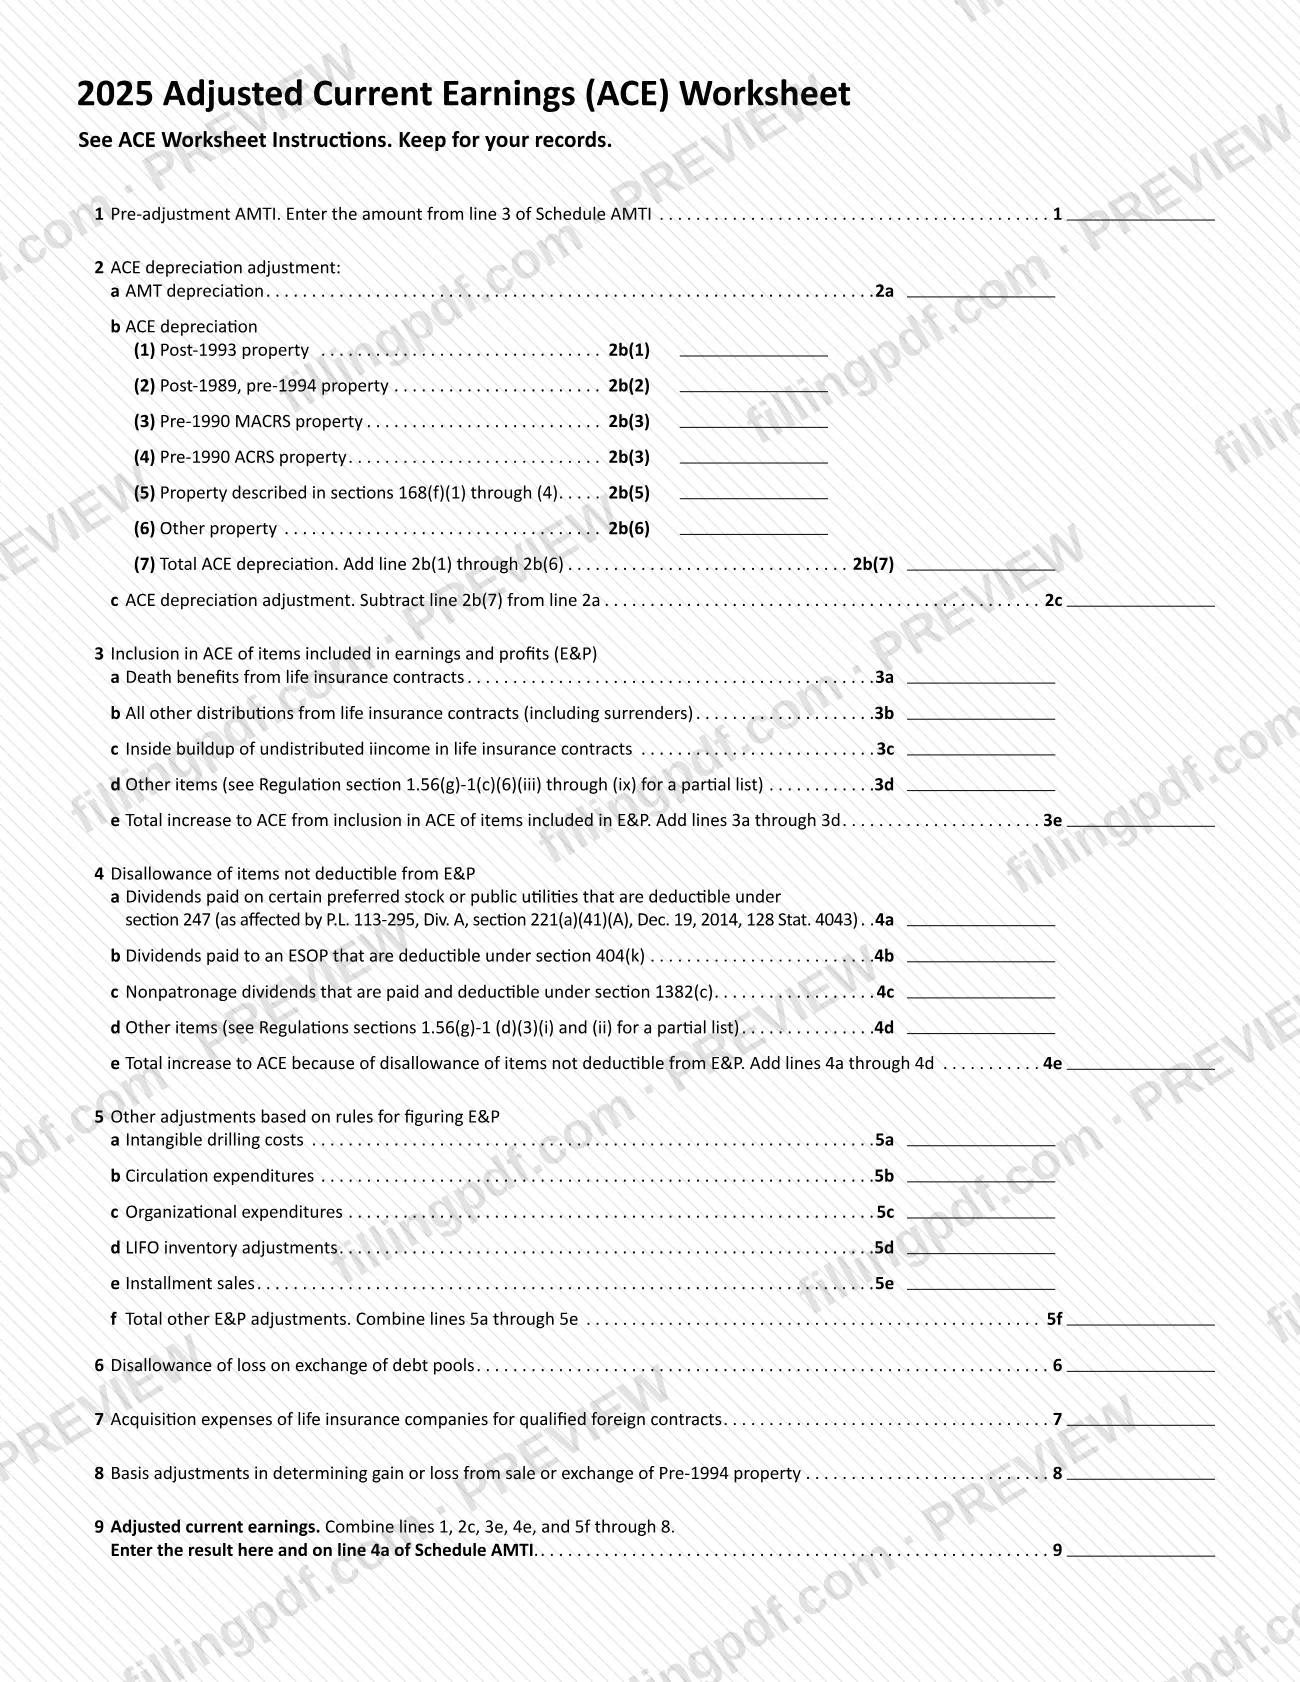
- The Adjusted Current Earnings (ACE) Worksheet printed with the instructions, completed first: its line 9 is entered on line 4a of the schedule.
- The 2024 Form 4626, lines 4d and 4e, to figure line 4d: combine them and enter the result, but not less than zero.
- Records of prior-year Schedule AMTI completed at least through line 5, kept from year to year, to support the line 4d running balance.
- For independent producers claiming the oil and gas intangible drilling cost exception: a second Schedule AMTI completed through line 5, including the IDC preference.
How to fill out AMTI
Enter corporation name and IDs
At the top, enter the Name of Corporation/Designated Filer, the FEIN and the Minnesota Tax ID Number. Round every amount on the form to the nearest whole dollar.
Enter Minnesota net income
On line 1, enter Minnesota net income from Form M4I, line 7.
Complete depreciation and amortization lines
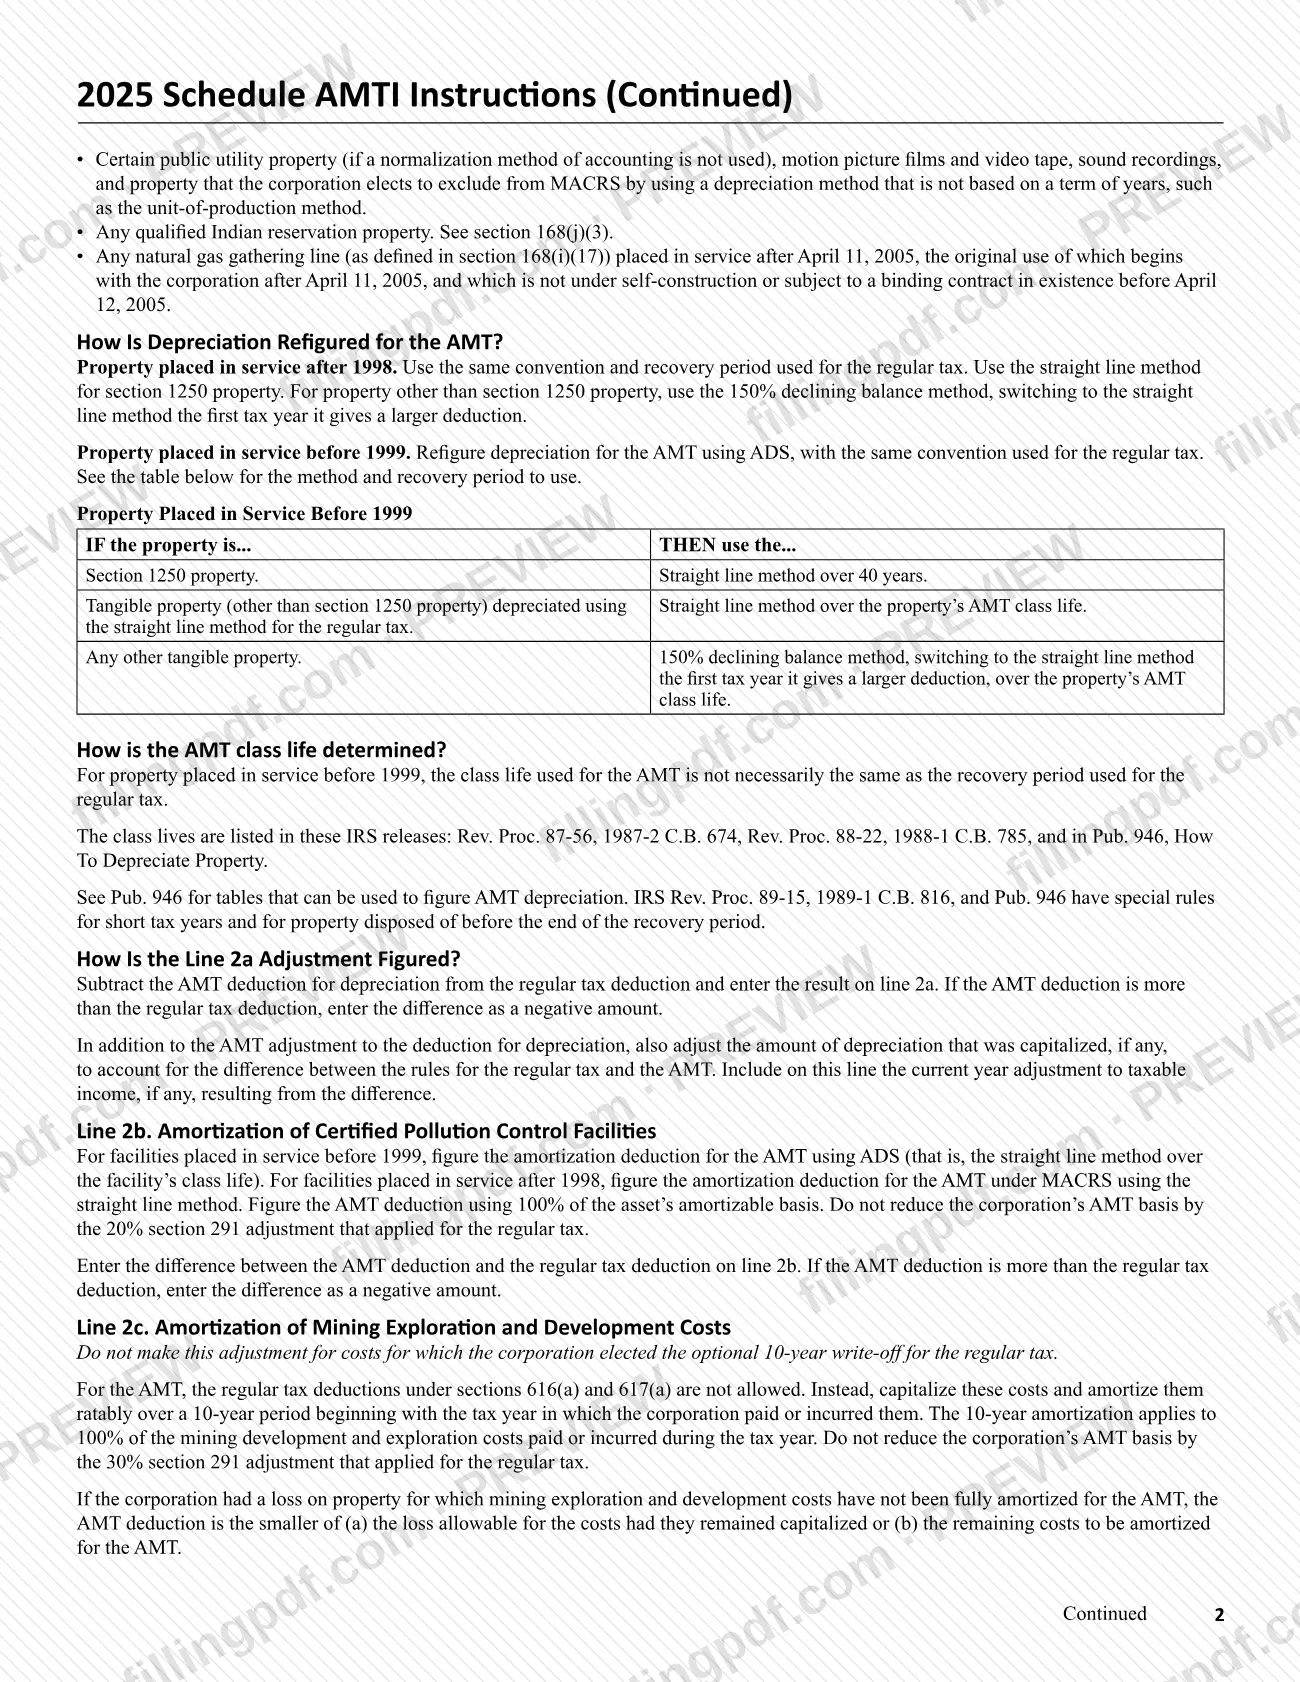
Lines 2a through 2d cover depreciation of post-1986 property, certified pollution control facilities, mining exploration and development costs, and circulation expenditures (personal holding companies only). For each, subtract the AMT deduction from the regular tax deduction; enter a negative amount if the AMT deduction is larger.
Complete gain, contract and fund lines
Line 2e is adjusted gain or loss on disposed property, line 2f long-term contracts, line 2g merchant marine capital construction funds, and line 2h the section 833(b) deduction (Blue Cross, Blue Shield and similar organizations only). Add back on 2g and 2h any amounts deducted or excluded for the regular tax.
Complete lines 2i through 2m
Line 2i is for personal service corporations (tax shelter farm activities), 2j for closely held and personal service corporations (passive activities), 2k loss limitations, 2l intangible drilling costs. Use 2m for other net adjustments and preferences, such as an estate or trust AMT adjustment from Schedule K-1 (Form 1041), Part III, box 12.
Combine lines 1 through 2m
On line 3, enter pre-adjustment alternative minimum taxable income by combining lines 1 through 2m.
Figure the ACE adjustment
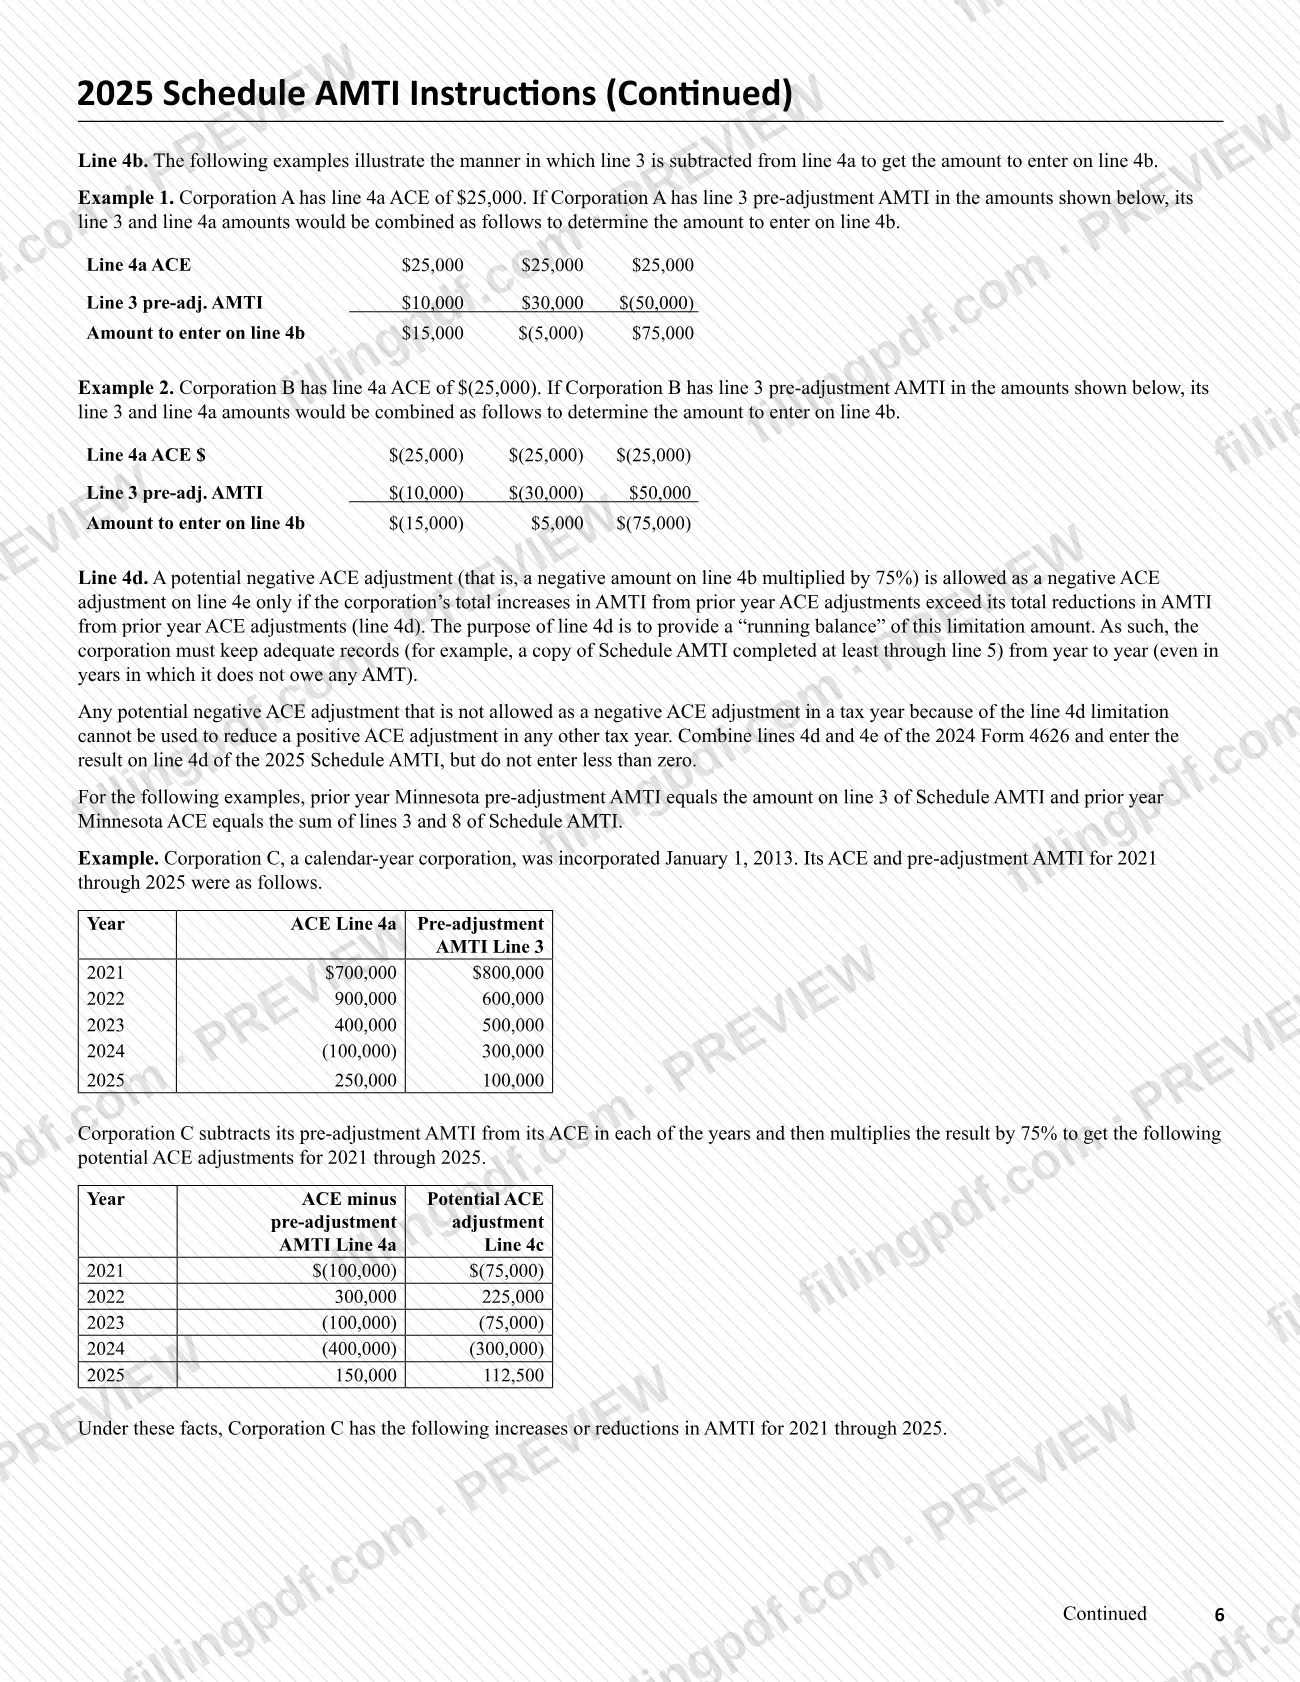
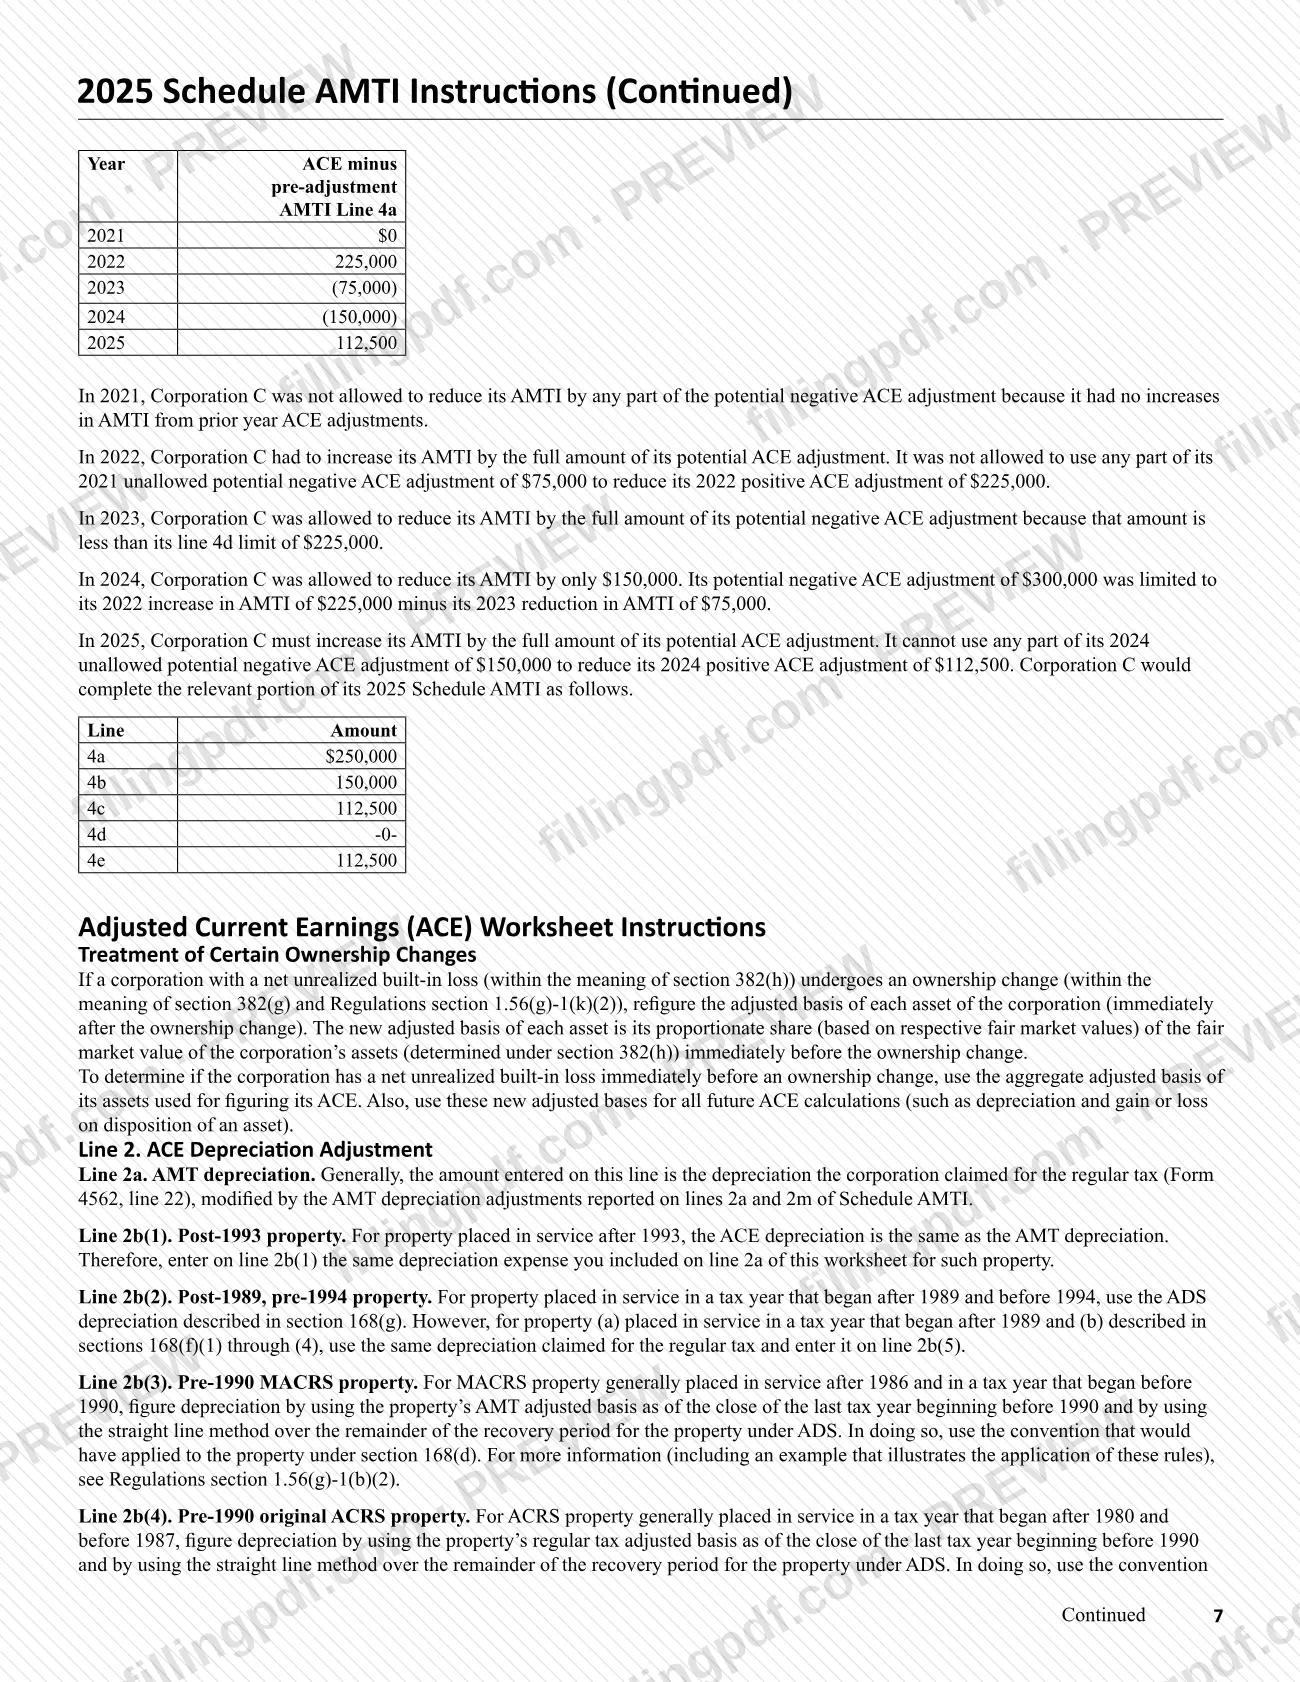
Complete the ACE worksheet, then enter its line 9 on line 4a. Subtract line 3 from line 4a for line 4b, multiply by 75% for line 4c as a positive amount, enter the line 4d balance, and enter the ACE adjustment on line 4e following the printed rules.
Combine lines 3 and 4e
Enter the combined amount on line 5. If the result is zero or less, or $310,000 or more, skip lines 6a and 6b and leave line 6 blank.
Figure the exemption on line 6
If line 5 is between zero and $310,000: on line 6a subtract $150,000 from line 5 (leave blank if zero or less), on line 6b multiply 6a by 25%, then on line 6 subtract 6b from $40,000.
Complete lines 7 and 8
On line 7, if line 5 is zero or less enter the line 5 amount; if more than zero, subtract line 6 from line 5 and leave blank if zero or less. On line 8, enter total nonapportionable income from Form M4I, line 8.
Calculate line 9 and short periods
Subtract line 8 from line 7 to get alternative minimum taxable income on line 9, and enter it on AMTT, line 1. For a period under 12 months, use the short-period steps in the instructions for lines 5 and 7.
Review and download the completed PDF
Check that each applicable line is complete, negative amounts are marked and the ACE worksheet is kept for your records. Download or print the completed PDF from FillingPDF.
How to submit AMTI
Form AMTI does not print a mailing address, portal or appointment rule of its own. Its result goes to another form: enter the amount from line 9 on AMTT, line 1. Unitary businesses complete only one Schedule AMTI.
The ACE worksheet that follows the instructions is marked "Keep for your records"; line 9 of the worksheet is entered on line 4a of the schedule. Keep adequate records of the prior-year ACE adjustments used on line 4d.
You can find this and other Minnesota Department of Revenue forms at https://www.revenue.state.mn.us/find-form. FillingPDF lets you fill out and download the PDF; submission follows the Minnesota Department of Revenue's channels for the forms this schedule supports.
Common mistakes to avoid
- Entering amounts with cents; the form says you must round amounts to the nearest whole dollar.
- Leaving line 4d blank when line 4b is positive; the form says you must enter an amount on line 4d even then.
- Counting an adjustment taken into account on line 2i, 2j, 2k or 2m again on another line of the form, which duplicates it.
- Making a depreciation adjustment on line 2a for tax shelter farm activities, passive activities or at-risk and partnership-basis items, which belong on lines 2i, 2j and 2k.
- Entering a negative result on line 4c; the instructions say to enter the result as a positive amount.
- Filing separate Schedules AMTI for each member of a unitary business; the instructions say to complete only one.
- Entering the 4e negative ACE amount without comparing line 4c with the line 4d limit; enter the smaller of line 4c or 4d.
- Completing a short-period return without annualizing: line 5 must be the short-period AMTI times 12 divided by the number of months.
Frequently asked questions
What is Form AMTI for alternative minimum tax in Minnesota?
Form AMTI, also called Schedule AMTI, is the Minnesota Department of Revenue schedule that calculates alternative minimum taxable income for a corporation or designated filer. You start from Minnesota net income on Form M4I, line 7, add adjustments and the ACE adjustment, and carry line 9 to AMTT, line 1.
Who does not have to complete Form AMTI?
Regulated investment companies, real estate investment trusts, real estate mortgage investment conduits, cooperatives, and small corporations exempt from federal AMT under IRC section 55(e) as amended through December 16, 2016 are not subject to alternative minimum tax and need not complete the form.
When must a corporation file Schedule AMTI?
If it is not an excluded type and its Minnesota net income from Form M4I, line 7, combined with adjustments and tax preferences (including adjusted current earnings), exceeds $40,000 or its allowable exemption amount. The schedule prints no separate due date.
What do I enter on line 4d of Form AMTI?
Enter the excess of the corporation's total increases in AMTI from prior-year ACE adjustments over its total reductions. Combine lines 4d and 4e of the 2024 Form 4626 and enter the result, but not less than zero. You must enter an amount even if line 4b is positive.
How do I complete Form AMTI for a short tax period?
Annualize AMTI: complete lines 1 through 4e, multiply the short-period AMTI by 12, divide by the number of months, and enter it on line 5. Work out line 6 and the line 7 amount, then multiply by the months and divide by 12 before entering it on line 7.
Where does the result of Form AMTI go?
Line 9, alternative minimum taxable income, is entered on AMTT, line 1. Form AMTI prints no address or portal of its own. Unitary businesses complete only one Schedule AMTI.
Can I fill out Form AMTI online on FillingPDF?
Yes. You can fill out the fillable PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the form with the Minnesota Department of Revenue; the agency receives it only through its own channels.
Ready to fill out AMTI?
Fill out AMTI now