
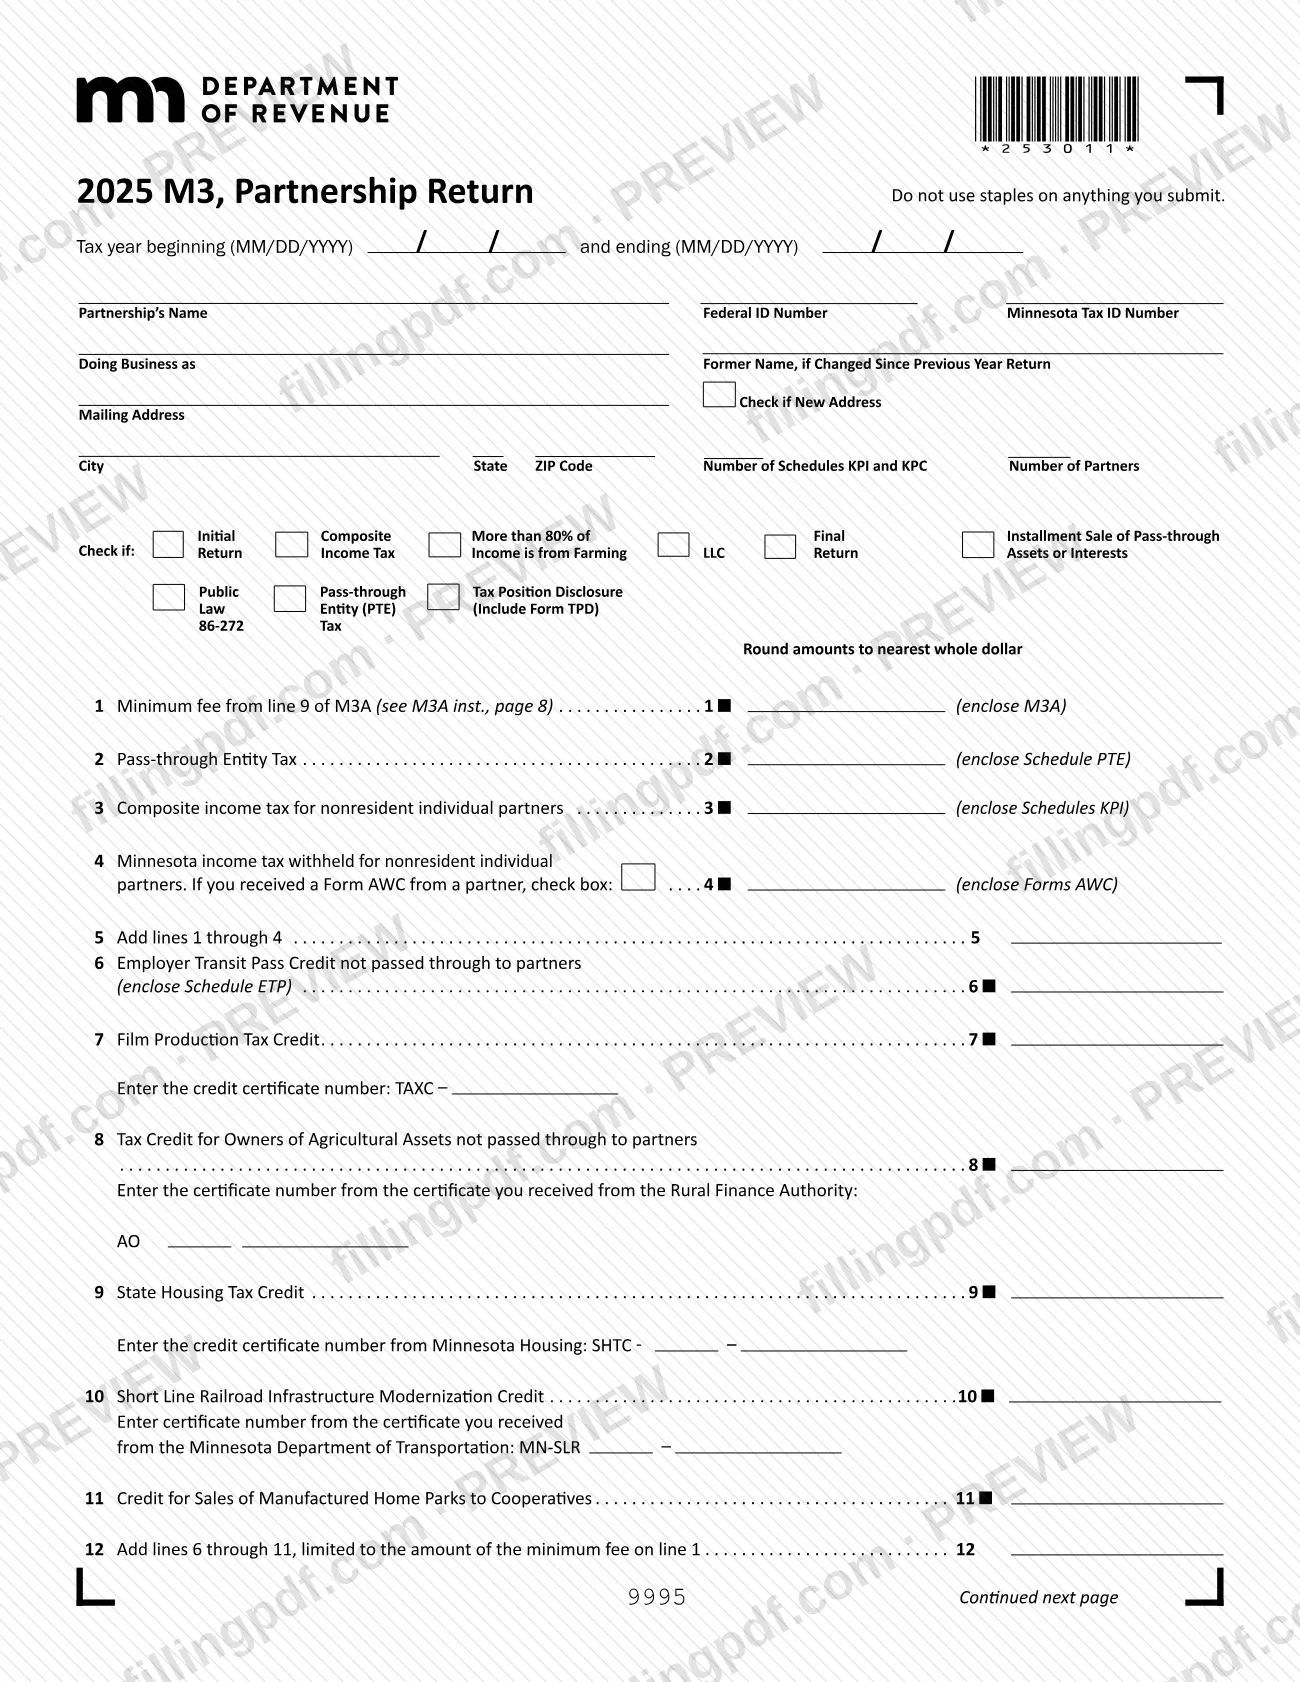
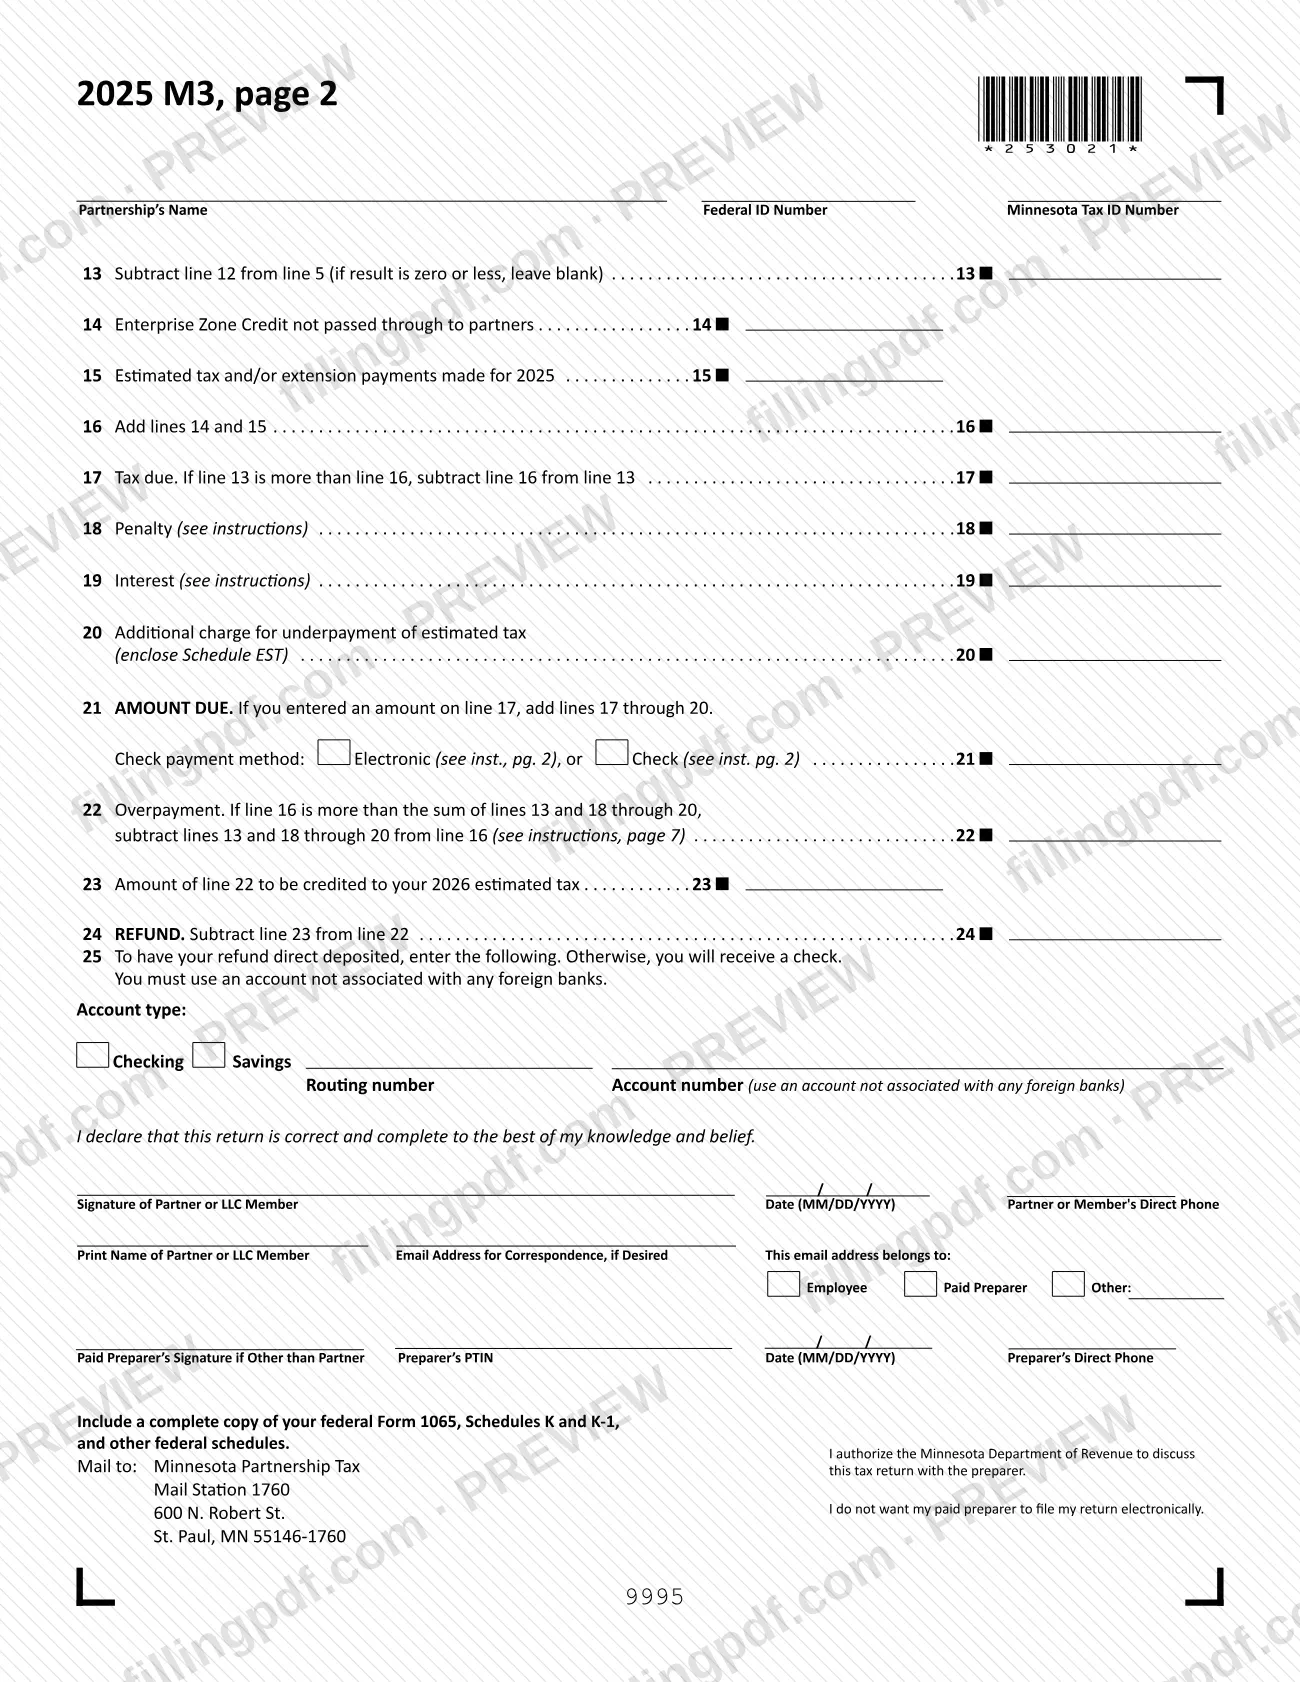
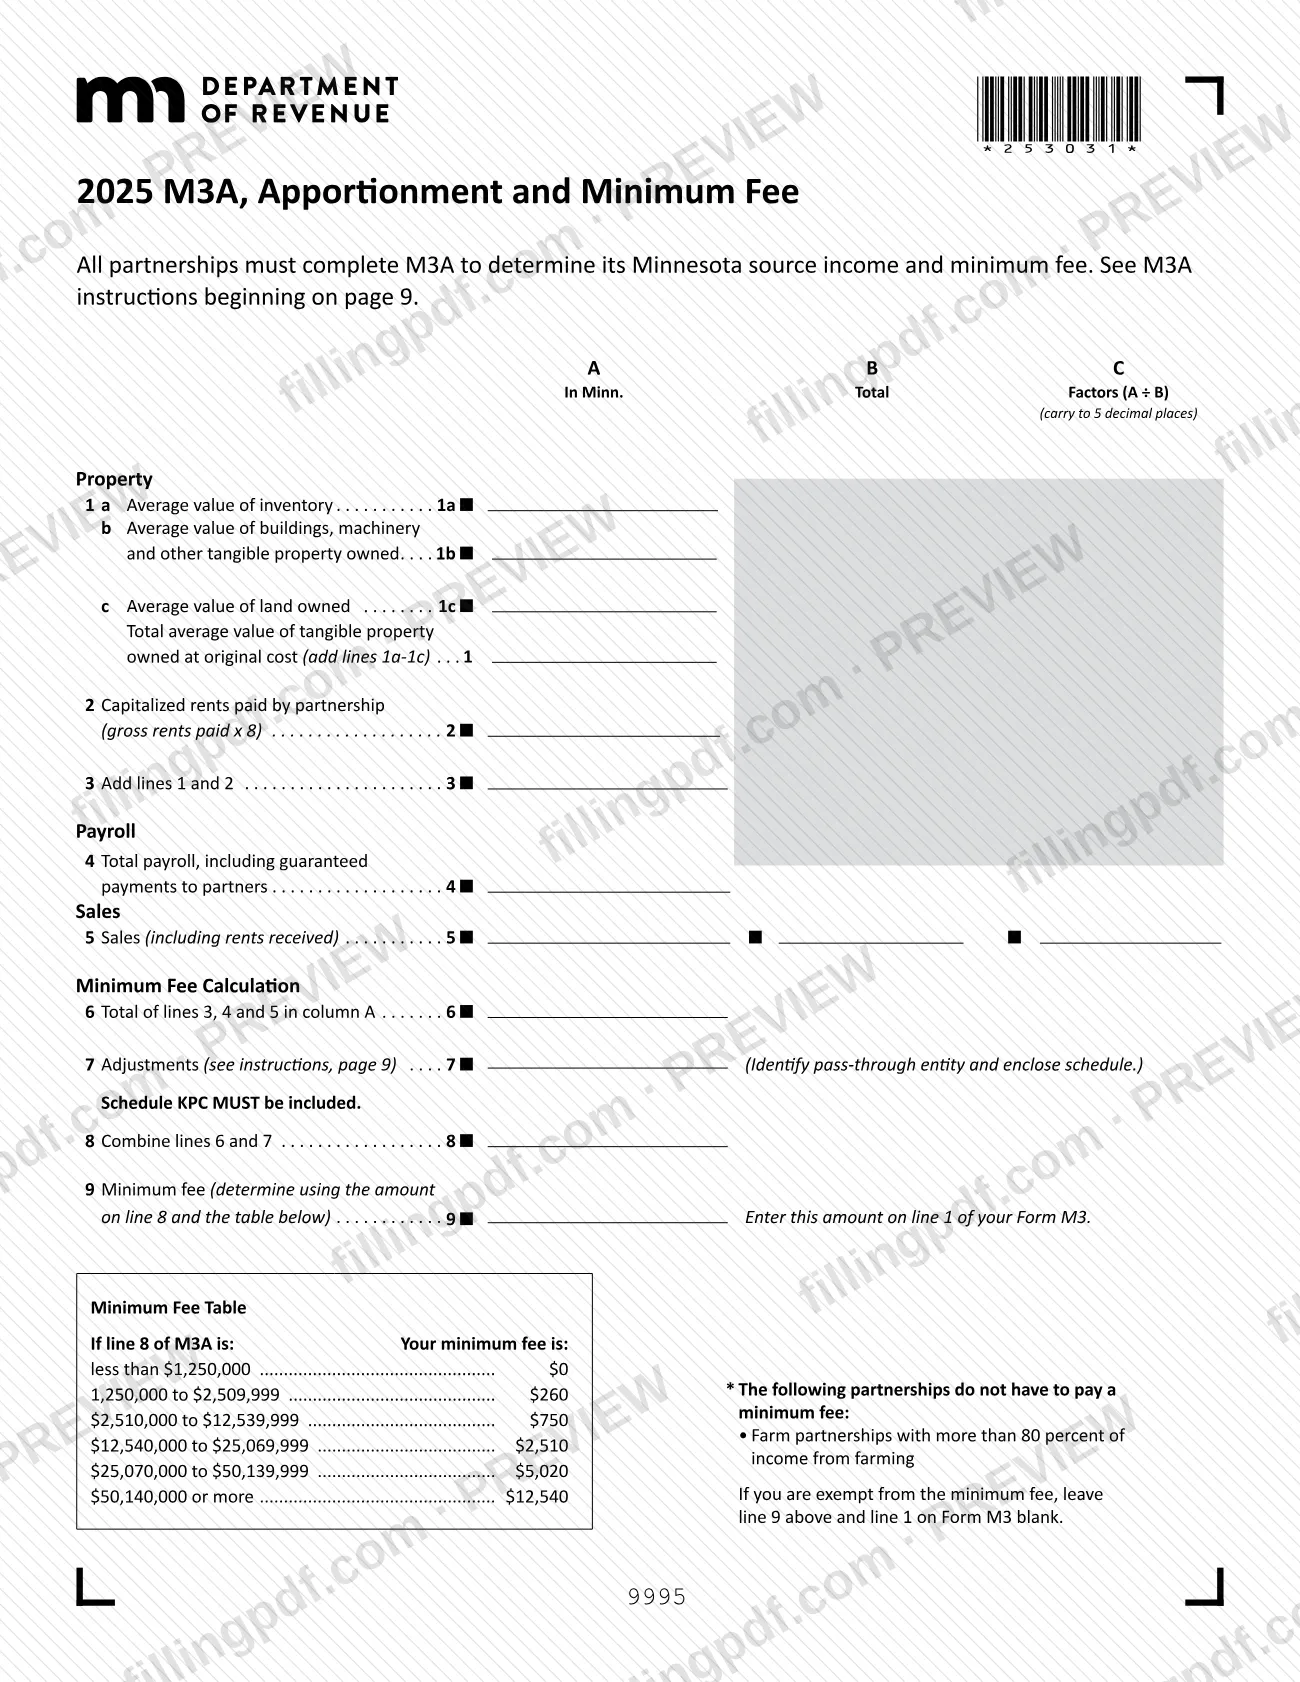
Form M3, Partnership Return, is the Minnesota Department of Revenue's partnership return for tax year 2025. Its page 3, M3A, Apportionment and Minimum Fee, is part of the same form. Partnerships and limited liability companies (LLCs) taxed as partnerships that have Minnesota gross income use it to report the minimum fee, pass-through entity tax, composite income tax and nonresident withholding. On this page you can fill out the form online on FillingPDF and download or print the completed PDF; the form and its instructions are published by the Minnesota Department of Revenue.
Last updated
What is M3?
Form M3, Partnership Return, is the Minnesota Department of Revenue form that partnerships, including LLCs taxed as partnerships, file for tax year 2025 to report entity-level amounts: the minimum fee, pass-through entity tax, composite income tax, nonresident withholding, credits, payments and any tax due or refund.
A partnership's income is taxed to its partners or members whether or not it is distributed, and each partner includes their share on their own return. The minimum fee is the part paid by the entity itself.
Page 3 of the form is M3A, Apportionment and Minimum Fee. Every partnership completes it to determine its Minnesota source income and its minimum fee, and the result goes to line 1 of Form M3. The return also travels with companion schedules: Schedule PTE (pass-through entity tax), Schedules KPI and KPC (each partner's share of income, credits and modifications), Schedule ETP, Schedule EST and Form AWC.
Form M3 is not the federal return. The instructions tell you to complete federal Form 1065, U.S. Return of Partnership Income, and its schedules first, and to include a complete copy with Form M3. An S corporation uses Form M8, S Corporation Return, instead. A partnership correcting a filed return uses Form M3X, Amended Partnership Return.
Who needs to file M3?
All entities that are required to file a federal Form 1065 and have Minnesota gross income must file Form M3, according to the Minnesota instructions.
- LLCs. An LLC that is a partnership for federal income tax purposes is a partnership for Minnesota, and its members are treated as partners. It checks the LLC box on the front of the form.
- Single-member LLCs. The form you use depends on what kind of entity the business is for federal tax purposes.
- Partnerships electing PTE tax or paying composite tax. They use the same return and check the matching box in the heading.
- Farm partnerships. A partnership with more than 80% of its income from farming is exempt from the minimum fee, but it still checks the farming box.
Do not use Form M3 if you are an S corporation: use Form M8. An entertainment entity that received compensation for performances in Minnesota and has no other Minnesota income is not required to file Form M3; it files Form ETR, Nonresident Entertainer Tax Return. A partnership protected under federal Public Law 86-272 with no Minnesota filing requirement does not need to pay a minimum fee.
A partner or LLC member signs the return. A paid preparer also signs and gives a PTIN.
When to file M3
Your Minnesota return and payment are due on the same date your federal return and payment are due. If that date falls on a weekend or legal holiday, a return or payment made electronically or postmarked the next business day is timely.
All partnerships get an automatic six-month extension to file Form M3 if the tax payable for the year is paid by the regular due date. If the IRS grants a federal extension longer than that, the Minnesota due date moves to the federal due date. An extension covers filing only: tax not paid by the regular due date is subject to penalties and interest.
A partnership must also make quarterly estimated tax payments when its estimated minimum fee, nonresident withholding, pass-through entity tax and composite income tax, less credits, reach the threshold in the instructions. It is not required to pay estimated tax in the first year it is subject to Minnesota tax.
If the IRS changes your federal return or you amend it, file Form M3X within 180 days of the IRS notice or of filing the federal amended return.
Documents you need
- A complete copy of your federal Form 1065, Schedules K and K-1, and other federal schedules; the form says to include them with the return.
- Page 3, M3A, Apportionment and Minimum Fee: every partnership completes it and encloses it with Form M3 (line 1).
- Schedule PTE and Schedule PTE-RP, if the partnership elects pass-through entity tax (line 2).
- Schedules KPI, for each partner who requires one: nonresident individual, estate or trust partners, Minnesota partners with income adjustments, and all partners if PTE tax is elected (line 3).
- Schedules KPC for each corporate or partnership partner, with copies of the schedules and attachments issued to partners.
- Form AWC, Alternative Withholding Certificate, if you received a signed and dated certificate from a partner and check the box on line 4.
- Schedule ETP if you claim the Employer Transit Pass Credit on line 6; Schedule MHP for line 11; Schedule EST if you enter an underpayment charge on line 20.
- For credits on lines 7 to 10, a statement showing certificate numbers and amounts when you have multiple credits; for line 14, the certification document from DEED.
- Federal Schedule L (Form 1065) or a copy of the partnership's balance sheet, enclosed for the M3A property factor.
- A schedule showing the computation and pass-through information for any adjustments on M3A, line 7.
- Form TPD, if you check the Tax Position Disclosure box.
- A copy of federal Form 1128 if you changed your federal accounting period, attached to the short-period Minnesota return.
How to fill out M3
Complete your federal Form 1065 first
Finish federal Form 1065 and its supporting schedules before starting Form M3, because you will refer to them. Keep a complete copy to include with the return.
Enter the tax year and entity details
Enter the tax year beginning and ending dates (MM/DD/YYYY), the partnership's name, Federal ID Number, Minnesota Tax ID Number, any doing-business-as or former name, mailing address, the number of Schedules KPI and KPC and the number of partners. Check Check if New Address when it applies.
Check the heading boxes that apply
Mark any of Initial Return, Composite Income Tax, More than 80% of Income is from Farming, Final Return, Installment Sale of Pass-through Assets or Interests, LLC, Public Law 86-272, Pass-through Entity (PTE) Tax and Tax Position Disclosure (include Form TPD). Each box is explained in the Minnesota instructions.
Complete M3A and the minimum fee
On page 3, enter property (lines 1a to 3), payroll (line 4) and sales (line 5) in columns A and B, then lines 6 to 9 to find the minimum fee from the table. Carry line 9 to line 1 of Form M3; a farm partnership with more than 80% of income from farming is exempt (the form says to leave line 9 and line 1 blank, while the instructions say to enter zero).
Enter fee and tax lines 1 to 5
Enter the minimum fee (line 1), pass-through entity tax from Schedule PTE (line 2), composite income tax (line 3, the total of line 54 on all KPI schedules) and nonresident withholding (line 4, the total of line 55 on all KPI schedules). Check the line 4 box if you received Form AWC, then add lines 1 through 4 on line 5.
Claim credits on lines 6 to 12
Enter the credits claimed directly by the partnership and not passed through: Employer Transit Pass (6), Film Production (7), Agricultural Assets (8), State Housing (9), Short Line Railroad (10) and Manufactured Home Parks (11), with certificate numbers where printed. Line 12 adds lines 6 through 11, limited to the minimum fee on line 1.
Figure tax due on lines 13 to 17
Subtract line 12 from line 5 for line 13, leaving it blank if zero or less. Enter the Enterprise Zone Credit not passed through (line 14) and estimated and extension payments for 2025 (line 15), add them on line 16, and enter tax due on line 17 if line 13 exceeds line 16.
Add penalty, interest and amount due
Enter penalty (line 18) and interest (line 19) as the instructions explain, and any Schedule EST charge on line 20. If line 17 has an amount, add lines 17 through 20 on line 21 and check Electronic or Check as the payment method.
Complete overpayment, refund and deposit
If line 16 is more than the sum of lines 13 and 18 through 20, enter the overpayment on line 22, the part to credit to 2026 estimated tax on line 23 and the refund on line 24. For direct deposit on line 25, give account type, a nine-digit routing number and the account number, from an account not associated with a foreign bank.
Prepare Schedules KPI and KPC
Complete a Schedule KPI or KPC for each partner who needs one, give each partner a copy, and enclose copies with Form M3. Enter each partner's Social Security number or Federal ID correctly.
Sign and complete the preparer section
A partner or LLC member signs, dates and prints their name, with a direct phone and optional email. A paid preparer signs with PTIN, date and phone, and you check the box if you authorize the department to discuss the return with the preparer.
Review, download and assemble the package
Check that amounts are rounded to whole dollars and all lines carry over correctly, then download or print the completed PDF from FillingPDF. Assemble it in the order described under How to submit, with no staples.
How to submit M3
You can file Form M3 electronically or on paper by mail.
- Electronic filing. The Minnesota instructions say options exist to prepare and file the partnership return electronically; see the Minnesota Department of Revenue website at www.revenue.state.mn.us.
- Paper by mail. Use the mailing label printed in the instructions, or send the return to: Minnesota Partnership Tax, Mail Station 1760, 600 N. Robert Street, St. Paul, MN 55146-1760. Assemble it in this order: Form M3, Schedule PTE, Schedules KPI, Schedules KPC, then your federal return and its schedules. Group schedules of the same type together and do not staple or tape anything.
- Large partnerships. Partnerships with more than 200 partners are asked to send federal Schedules K-1 and Minnesota Schedules KPI and KPC on CDs or flash drives; paper copies are still accepted if that is not possible.
Payment. If line 21 shows an amount due, pay electronically on the department's website, by credit or debit card (a third-party vendor charges a fee), or by check with a voucher created through the Payment Voucher System. If you must pay any Minnesota business tax electronically, you must pay all taxes that way, or an additional penalty applies.
Questions go to [email protected] or 651-556-3075. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Stapling or taping enclosures to the return; the form and instructions say not to use staples on anything you submit.
- Leaving out a complete copy of federal Form 1065, Schedules K and K-1 and the other federal schedules.
- Skipping M3A: all partnerships must complete it to find their Minnesota source income and minimum fee.
- Assuming an extension to file also extends the payment date; tax not paid by the regular due date is subject to penalties and interest.
- Paying by check when you are required to pay electronically; an additional penalty applies even if the check is sent on time.
- Entering a bank account associated with a foreign bank for electronic payment or direct deposit of the refund.
- Filing this return as an S corporation, which uses Form M8, or omitting Schedule KPI for a partner who needs one, since the department disallows nonresident withholding if the partner's Schedule KPI is not included.
- Forgetting to check the Installment Sale of Pass-through Assets or Interests box, and to complete line 7 of Schedules KPI and line 10 of Schedules KPC, when the partnership made such a sale.
- Entering cents instead of rounding amounts to the nearest whole dollar.
- Submitting the return without the signature of a partner or LLC member.
Frequently asked questions
What is the Minnesota partnership return, Form M3?
Form M3, Partnership Return, is the Minnesota Department of Revenue form used by partnerships, including LLCs taxed as partnerships, to report the minimum fee, pass-through entity tax, composite income tax, nonresident withholding, credits and payments for 2025. Page 3 is M3A, Apportionment and Minimum Fee.
Who has to file Form M3 in Minnesota?
Every entity required to file federal Form 1065 that has Minnesota gross income must file Form M3. S corporations use Form M8 instead. An entertainment entity whose only Minnesota income is compensation for performances there is not required to file Form M3; it files Form ETR.
When is Form M3 due, and can I get an extension?
The return and payment are due the same date as your federal return and payment. Partnerships get an automatic six-month extension to file if the tax is paid by the regular due date, or the federal due date if the IRS extension is longer. It does not extend the time to pay.
Where do I mail Form M3?
Mail paper returns to Minnesota Partnership Tax, Mail Station 1760, 600 N. Robert Street, St. Paul, MN 55146-1760, or use the mailing label in the instructions. Do not staple anything. Electronic filing options are described on www.revenue.state.mn.us.
What do I attach to Form M3?
Include a complete copy of federal Form 1065 with Schedules K and K-1 and other federal schedules, plus M3A. Add only the Minnesota schedules that apply, such as Schedule PTE, Schedules KPI and KPC, Form AWC, Schedule ETP or Schedule EST, as the line instructions direct.
Does my partnership have to pay the minimum fee?
A partnership owes it if the sum of its Minnesota source property, payroll and sales is at least $1,250,000. You are exempt if more than 80% of your income is from farming, and no fee is due if Public Law 86-272 protects you and you have no Minnesota filing requirement.
Who signs Form M3?
A partner or LLC member must sign the return. A paid preparer must also sign and give a PTIN. Checking the authorization box lets the department discuss the return with the preparer, but it does not let the preparer sign or represent you; that requires Form REV184b.
How do I correct a Form M3 I already filed?
Use Form M3X, Amended Partnership Return. If the IRS changes or audits your federal return, or you amend it, file Form M3X within 180 days of the notice or federal amended filing, with a copy of the IRS report or federal amended return.
Can I fill out Form M3 online on FillingPDF?
Yes. You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is independent of the Minnesota Department of Revenue and does not file the return; you submit it electronically or by mail through the department's channels.
Ready to fill out M3?
Fill out M3 now