
Nebraska Schedule I (Form 56), Tobacco Products Other Than Snuff And Consumable Material Imported or Manufactured and Exported, is the schedule that the Nebraska Department of Revenue (DOR) has you attach to Form 56 to list tobacco product imports, sales by Nebraska manufacturers and exports to other states. Wholesalers, importers and manufacturers use it to support lines 1 and 2 of Form 56. On FillingPDF you can fill out the form online and download or print the completed PDF; the DOR publishes the original PDF and receives the filing through its own channels.
Last updated
What is Schedule I (Form 56)?
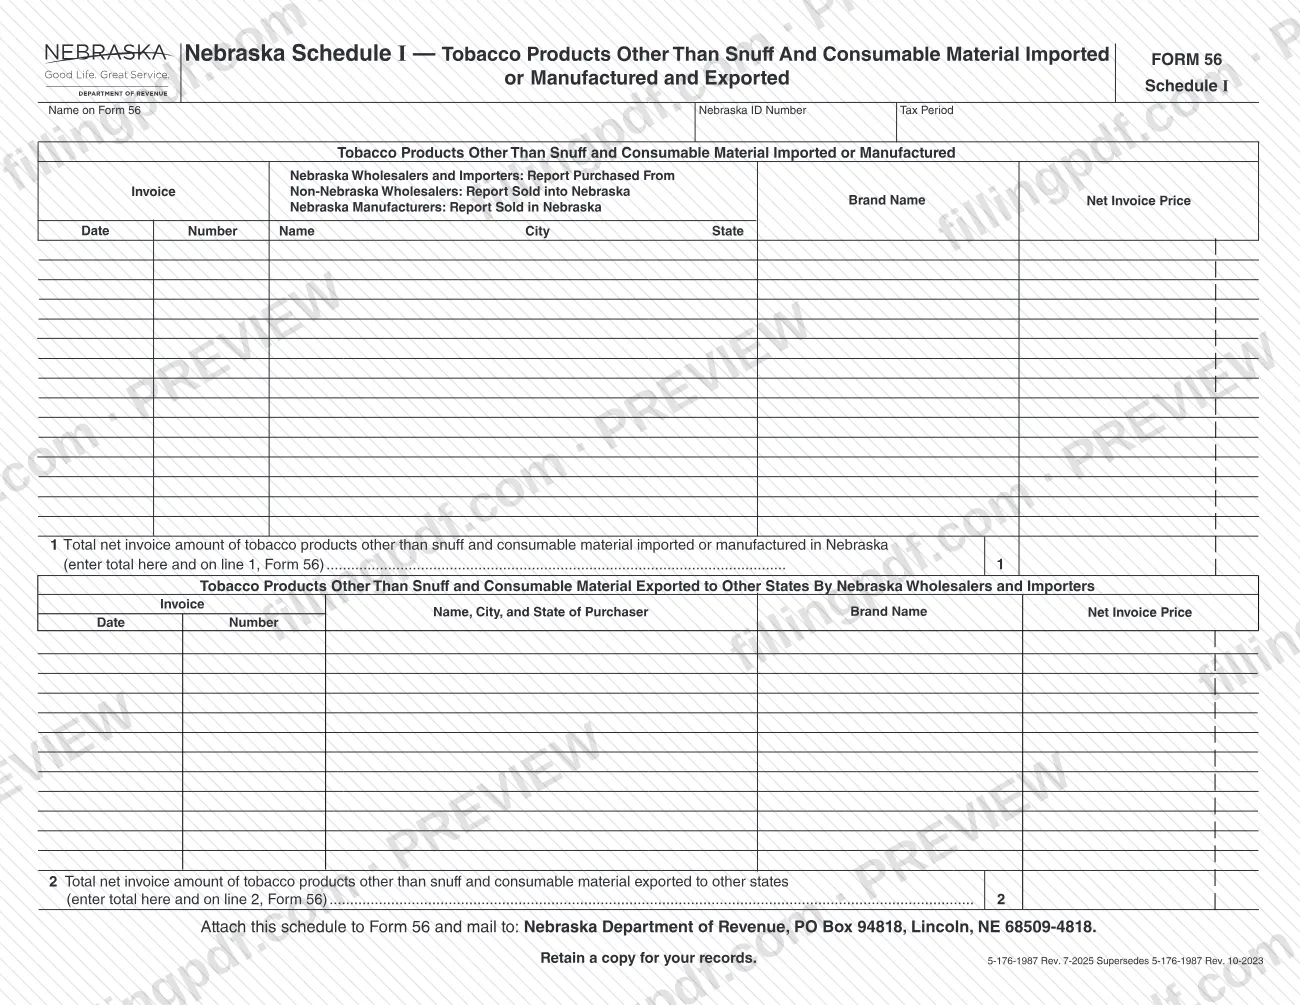
Nebraska Schedule I (Form 56) is the Nebraska Department of Revenue schedule that reports imports, Nebraska-manufactured sales and exports of tobacco products other than snuff and consumable material, and its totals carry to lines 1 and 2 of Form 56.
The schedule has two tables. The first lists tobacco products imported or manufactured: for each entry you give the invoice date and number, the name, city and state of the other party, the brand name and the net invoice price. Line 1 totals that table. The second lists exports to other states by Nebraska wholesalers and importers, with the name, city and state of the purchaser, invoice date and number, brand name and net invoice price. Line 2 totals it.
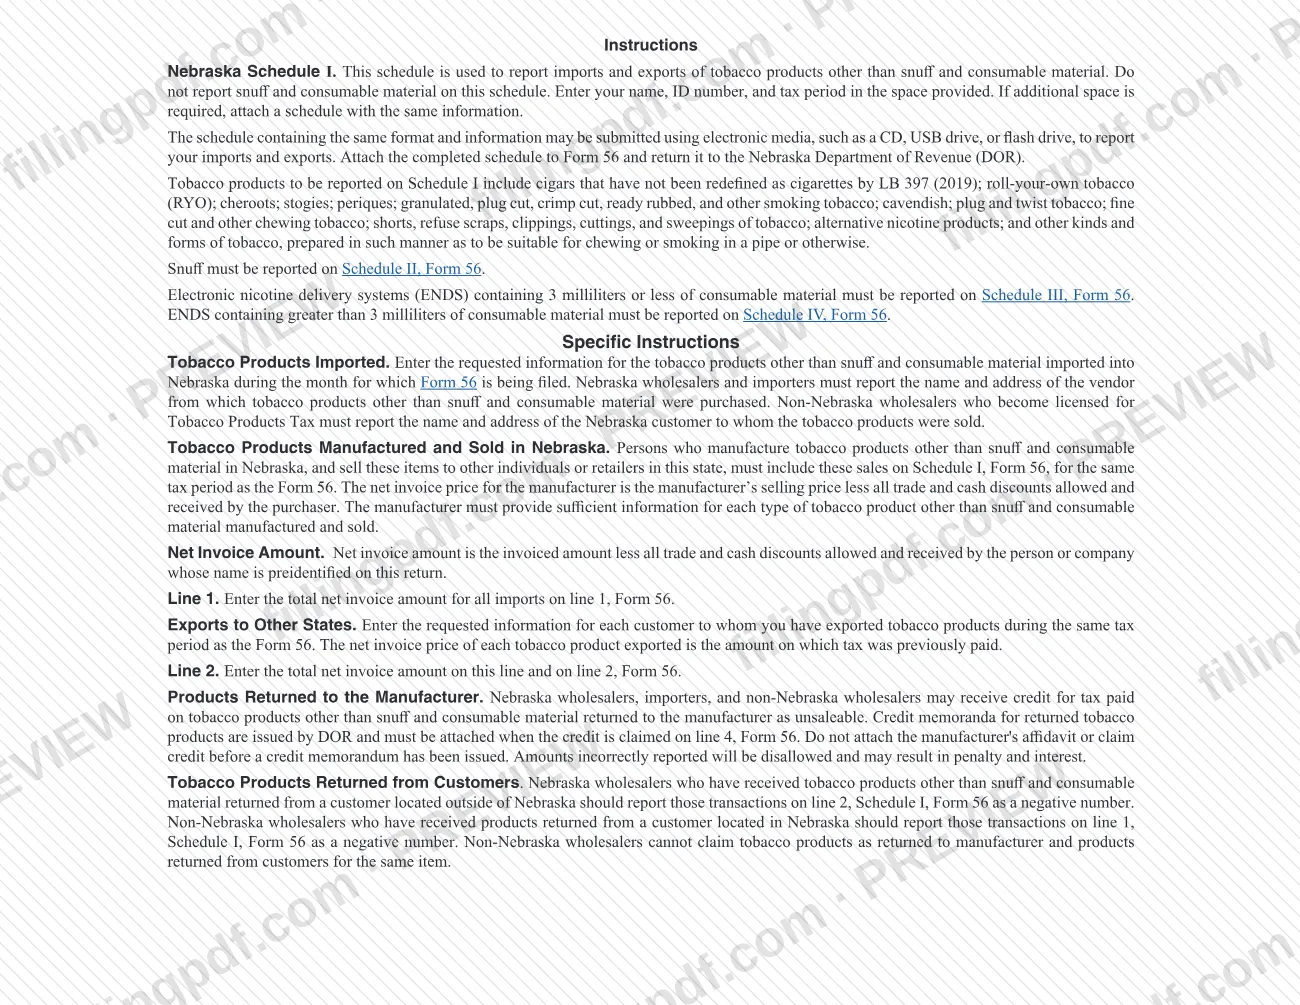
The DOR instructions say which products belong here: cigars that have not been redefined as cigarettes by LB 397 (2019); roll-your-own tobacco (RYO); cheroots; stogies; periques; smoking tobacco in its various cuts; cavendish; plug and twist tobacco; chewing tobacco; tobacco scraps and sweepings; alternative nicotine products; and other tobacco prepared for chewing or smoking in a pipe or otherwise.
It is not the schedule for every product on Form 56. Snuff goes on Schedule II, electronic nicotine delivery systems (ENDS) with 3 milliliters or less of consumable material on Schedule III, and ENDS with more than 3 milliliters on Schedule IV. The printed revision is Rev. 7-2025 (5-176-1987), which supersedes Rev. 10-2023.
Who needs to file Schedule I (Form 56)?
The main group is businesses that file Nebraska Form 56 and handle tobacco products other than snuff and consumable material. The DOR instructions name these filers:
- Nebraska wholesalers and importers report the tobacco products they imported during the month of the Form 56, with the name and address of the vendor they bought from. They also report exports to other states.
- Non-Nebraska wholesalers licensed for Tobacco Products Tax report the name and address of the Nebraska customer to whom the products were sold.
- Nebraska manufacturers who make these products in Nebraska and sell them to individuals or retailers in this state include those sales for the same tax period as the Form 56.
Do not report snuff or consumable material on this schedule. Snuff belongs on Schedule II of Form 56, ENDS with 3 milliliters or less of consumable material on Schedule III, and ENDS with more than 3 milliliters on Schedule IV.
Returned products also appear here. Nebraska wholesalers with products returned by a customer outside Nebraska report them on line 2 as a negative number. Non-Nebraska wholesalers with products returned by a Nebraska customer report them on line 1 as a negative number.
When to file Schedule I (Form 56)
Schedule I is filed with Form 56, so it covers the same tax period as that return. The instructions tell you to report products imported into Nebraska during the month for which Form 56 is filed. Exports and sales by Nebraska manufacturers are reported for the same tax period as the Form 56. The schedule prints no separate due date.
Returns and credits have a timing rule. Credit memoranda for tobacco products returned to the manufacturer as unsaleable are issued by the DOR. Do not attach the manufacturer's affidavit or claim credit on line 4 of Form 56 before a credit memorandum has been issued. Amounts reported incorrectly will be disallowed and may result in penalty and interest.
Documents you need
- Form 56, to which Schedule I must be attached; the schedule is not sent on its own.
- An attached schedule with the same information, only if you need more space than the printed tables provide.
- The credit memorandum issued by the DOR, only when you claim credit on line 4 of Form 56 for tobacco products returned to the manufacturer as unsaleable.
How to fill out Schedule I (Form 56)
Enter name, ID number and tax period
At the top, enter the name on Form 56, your Nebraska ID Number and the Tax Period. The tax period must match the Form 56 you are attaching the schedule to.
Confirm the products belong here
Report only tobacco products other than snuff and consumable material. Snuff goes on Schedule II, ENDS with 3 milliliters or less on Schedule III and ENDS with more than 3 milliliters on Schedule IV.
List imported or manufactured products
In the first table, enter for each entry the invoice date and number, the name, city and state, the brand name and the net invoice price. Nebraska wholesalers and importers give the vendor they purchased from; non-Nebraska wholesalers give the Nebraska customer; Nebraska manufacturers give the buyer in Nebraska.
Figure the net invoice price
Use the invoiced amount less all trade and cash discounts allowed and received. For a manufacturer, it is the selling price less all trade and cash discounts allowed and received by the purchaser.
Total line 1
Add the net invoice prices in the first table and enter the total on line 1 of the schedule and on line 1 of Form 56.
List exports to other states
In the second table, for each customer enter the invoice date and number, the name, city and state of the purchaser, the brand name and the net invoice price. The price is the amount on which tax was previously paid.
Total line 2
Add the net invoice prices in the export table and enter the total on line 2 of the schedule and on line 2 of Form 56.
Enter returned products as negatives
Nebraska wholesalers report products returned by customers outside Nebraska on line 2 as a negative number. Non-Nebraska wholesalers report products returned by Nebraska customers on line 1 as a negative number.
Add pages if you run out of space
If the tables are too short, attach a schedule with the same information.
Review and download the completed PDF
Check names, invoice details and both totals against Form 56. Download or print the completed PDF from FillingPDF, attach it to Form 56, keep a copy and submit it as described under How to submit.
How to submit Schedule I (Form 56)
Schedule I goes to the DOR attached to Form 56, either on paper by mail or on electronic media.
- By mail: attach the schedule to Form 56 and mail both to Nebraska Department of Revenue, PO Box 94818, Lincoln, NE 68509-4818.
- On electronic media: a schedule in the same format with the same information may be submitted on a CD, USB drive or flash drive. Attach the completed schedule to Form 56 and return it to the DOR.
If you need more space, attach a schedule with the same information. When you claim credit for products returned to the manufacturer, attach the DOR-issued credit memorandum to the filing, because the credit is claimed on line 4 of Form 56. Keep a copy of the schedule for your records; the form says to retain one. The form names no other channel or fee. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Reporting snuff or consumable material on Schedule I; snuff goes on Schedule II, and ENDS go on Schedule III or Schedule IV depending on the amount of consumable material.
- Entering the gross invoice amount instead of the net invoice amount, which is the invoiced amount less all trade and cash discounts allowed and received.
- Leaving the totals on line 1 or line 2 of Schedule I without entering them also on line 1 or line 2 of Form 56.
- Reporting products returned from customers as positive numbers; they are entered as negative numbers on line 2 (Nebraska wholesalers) or line 1 (non-Nebraska wholesalers).
- Claiming credit for returned products, or attaching the manufacturer's affidavit, before the DOR has issued a credit memorandum.
- A non-Nebraska wholesaler claiming the same item both as returned to the manufacturer and as returned from a customer; the instructions do not allow both.
- Mailing Schedule I alone instead of attaching it to Form 56 and sending both to PO Box 94818, Lincoln, NE 68509-4818.
- Reporting transactions from a different month than the tax period of the Form 56 you are filing.
- Omitting the name, Nebraska ID number or tax period at the top of the schedule.
Frequently asked questions
What is Schedule I of Nebraska Form 56?
Schedule I is the Nebraska Department of Revenue schedule attached to Form 56 that lists tobacco products other than snuff and consumable material imported into Nebraska, manufactured and sold in Nebraska, or exported to other states. Its totals go on lines 1 and 2 of Form 56.
Where do I report snuff or e-cigarette products?
Not on Schedule I. Snuff must be reported on Schedule II of Form 56. ENDS with 3 milliliters or less of consumable material go on Schedule III, and ENDS with more than 3 milliliters go on Schedule IV.
Where do I mail Nebraska Schedule I?
Attach it to Form 56 and mail both to Nebraska Department of Revenue, PO Box 94818, Lincoln, NE 68509-4818. The form tells you to keep a copy of the schedule for your records.
Can I submit Schedule I on a USB drive instead of paper?
Yes, if the schedule has the same format and information. The DOR instructions allow electronic media such as a CD, USB drive or flash drive. Attach the completed schedule to Form 56 and return it to the Department of Revenue.
What is the net invoice amount on Schedule I?
It is the invoiced amount less all trade and cash discounts allowed and received by the person or company named on the return. For a manufacturer, it is the selling price less the discounts allowed and received by the purchaser.
How do I report tobacco products that were returned?
As negative numbers. Nebraska wholesalers enter returns from customers outside Nebraska on line 2; non-Nebraska wholesalers enter returns from Nebraska customers on line 1. Credit for products returned to the manufacturer needs a DOR credit memorandum first.
Which month does Schedule I cover?
The same tax period as the Form 56 it accompanies. Imports are those brought into Nebraska during the month for which Form 56 is filed, and exports and manufacturer sales are reported for that same tax period.
Can I fill out Nebraska Schedule I online on FillingPDF?
Yes. You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the schedule with the DOR; you submit it with Form 56 by mail or on electronic media.
Ready to fill out Schedule I (Form 56)?
Fill out Schedule I (Form 56) now