
Form 306 is the New Jersey Corporation Business Tax schedule for the research and development tax credit, issued by the NJ Division of Taxation. A corporation that claims a credit for increasing research activities completes it and submits it with its tax return. On this page you can fill out the 2024 form online on FillingPDF and download or print the completed PDF; the form and its instructions are published by the Division of Taxation at nj.gov/treasury/taxation.
Last updated
What is Form 306?
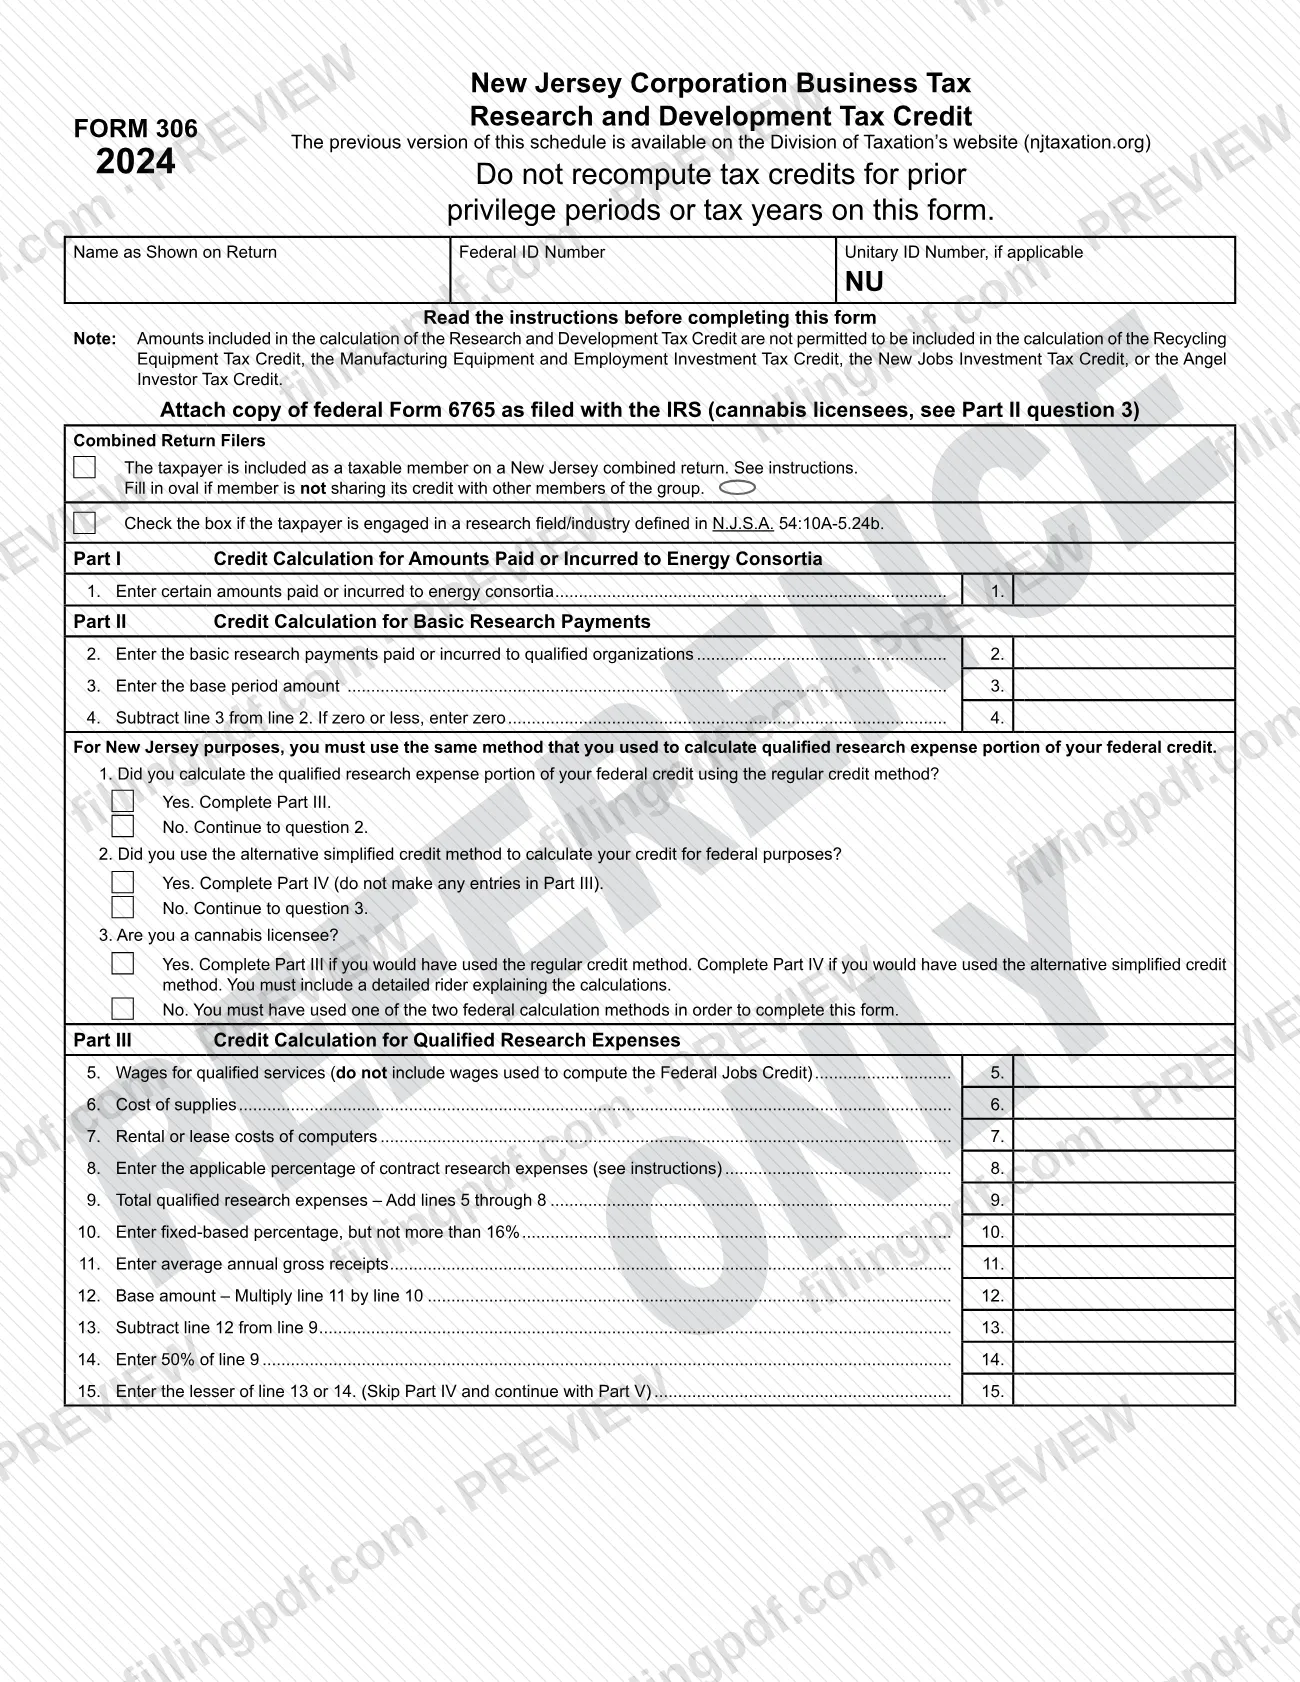
Form 306, Research and Development Tax Credit, is the New Jersey Corporation Business Tax (CBT) schedule used to calculate and claim the credit for increasing the research activities of a trade or business, and to work out the allowable credit and the carryforward.
The NJ Division of Taxation issues the form, and taxpayers must use the version that matches the tax period they are filing. This page covers the 2024 version.
New Jersey follows the federal corporate income tax R&D credit rules and methods, with differences. The New Jersey credit is fixed at 10%, and it covers only research performed in New Jersey. You must use the same calculation method you used for the federal credit, and you enclose a copy of federal Form 6765 as filed with the IRS.
The form has seven parts:
- Part I: amounts paid or incurred to energy consortia.
- Part II: basic research payments.
- Part III: qualified research expenses under the regular credit method.
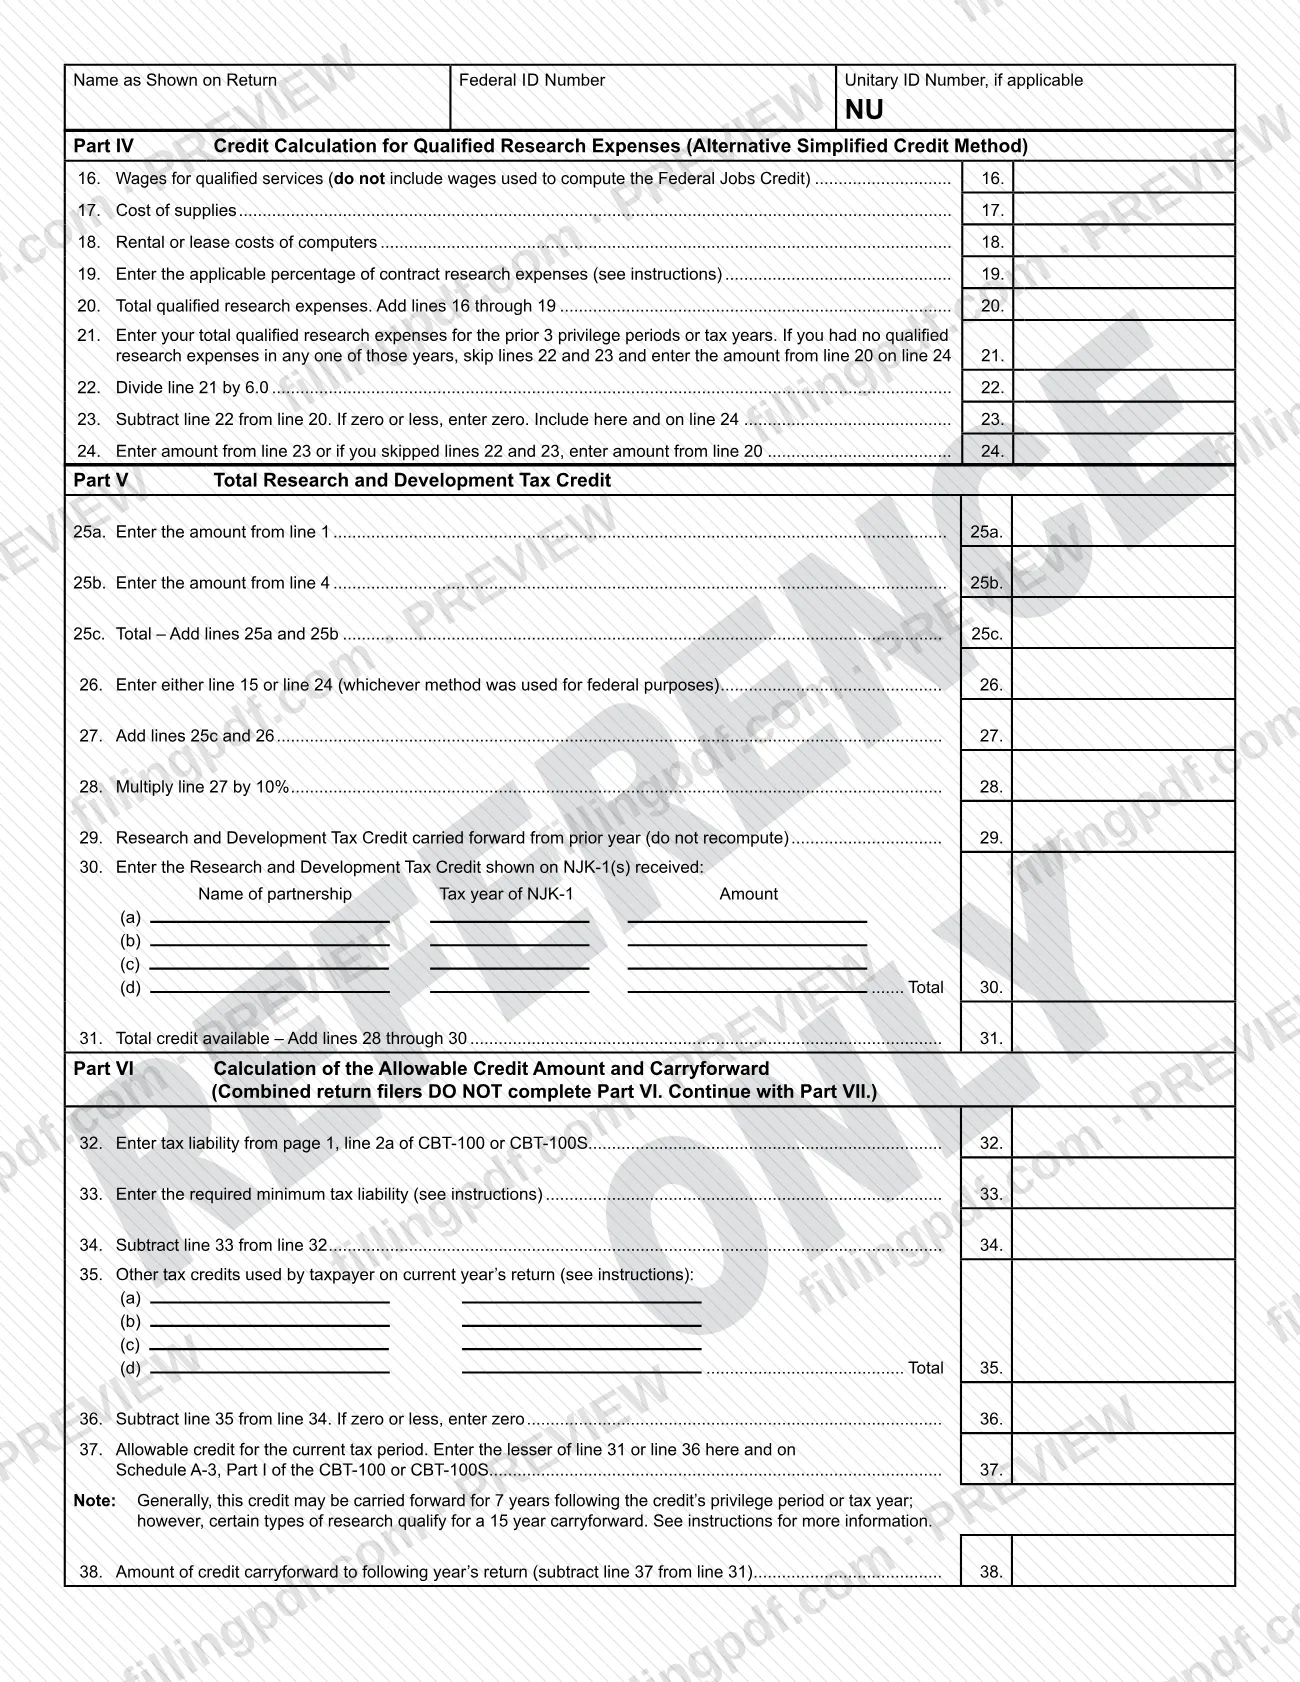
- Part IV: qualified research expenses under the alternative simplified credit method.
- Part V: the total credit.
- Part VI: allowable credit and carryforward for CBT-100 and CBT-100S filers.
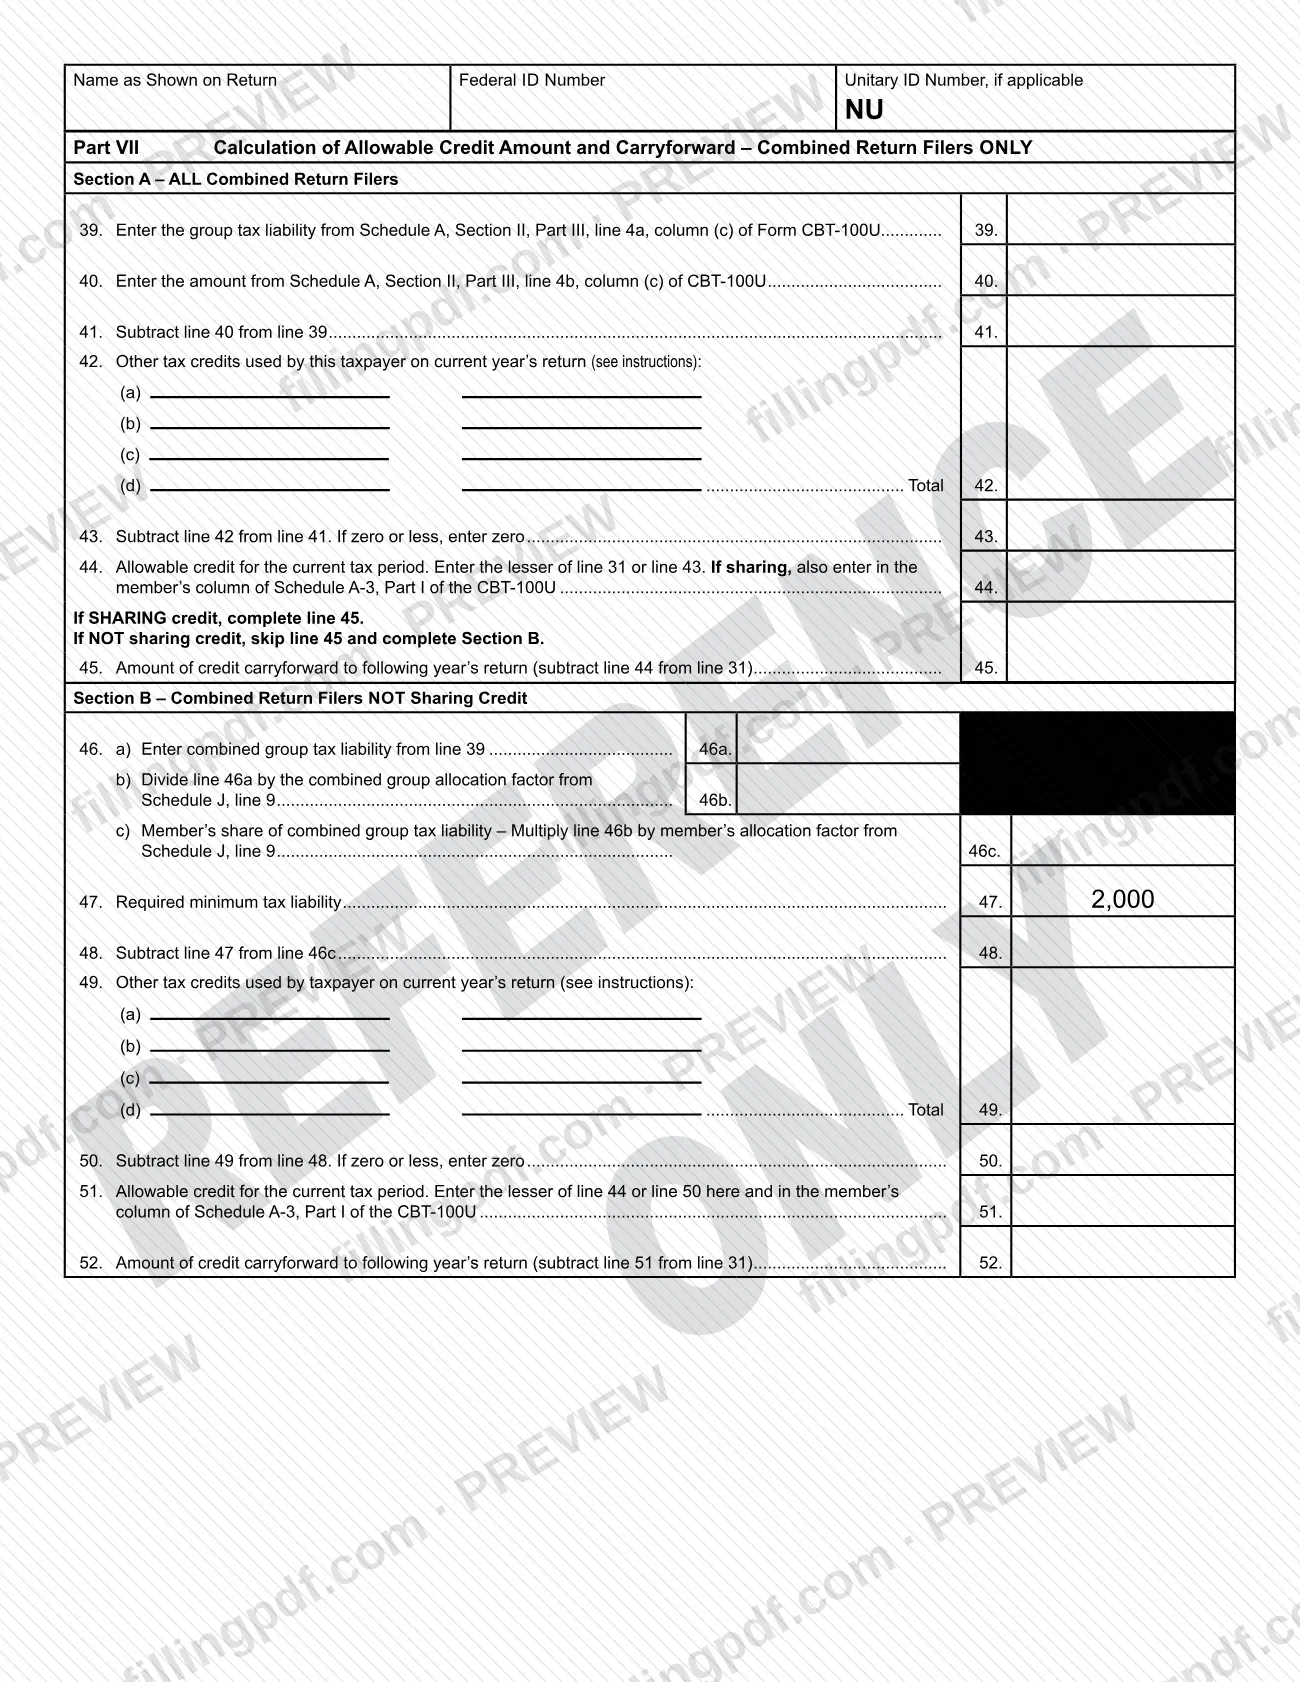
- Part VII: allowable credit and carryforward for combined return filers (CBT-100U).
Amounts used in this credit cannot also be used for the Recycling Equipment Tax Credit, the Manufacturing Equipment and Employment Investment Tax Credit, the New Jersey New Jobs Investment Tax Credit or the Angel Investor Tax Credit.
Who needs to file Form 306?
A corporation claiming a credit for increasing research activities completes Form 306 and submits it with its tax return. Which parts you complete depends on your filing type:
- CBT-100 and CBT-100S filers complete Part VI.
- Combined return (CBT-100U) filers skip Part VI and complete Part VII, Section A. The member that earned or purchased the credit completes the form, and each member completes its own schedule. A member that chooses not to share its credit also completes Section B and fills in the oval at the top.
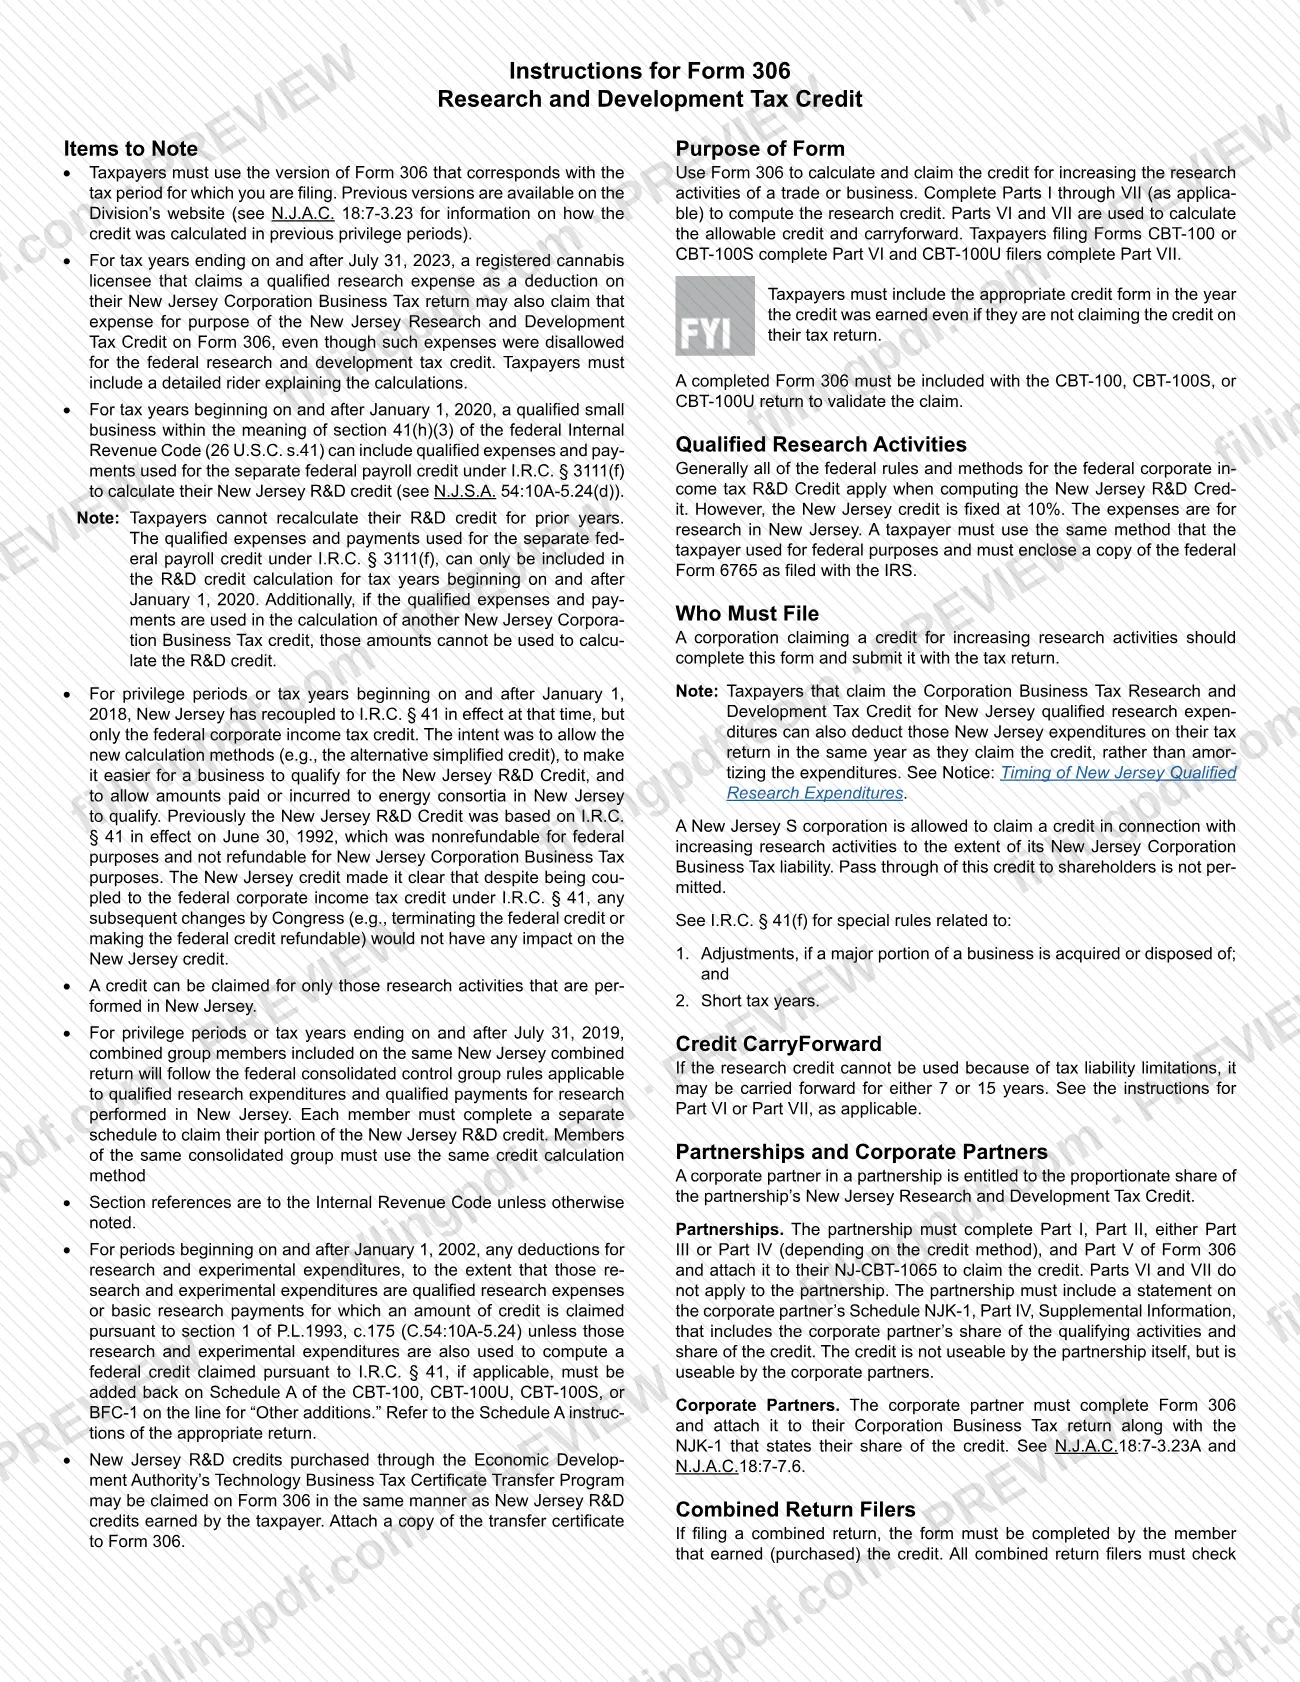
- Partnerships complete Parts I, II, either III or IV, and V, and attach the form to the NJ-CBT-1065. Parts VI and VII do not apply, and the partnership cannot use the credit itself.
- Corporate partners complete Form 306 for their proportionate share of the partnership's credit and attach the NJK-1 that states it.
- Cannabis licensees follow Part II, question 3, and attach a detailed rider.
- Purchasers of credits through the Economic Development Authority's Technology Business Tax Certificate Transfer Program claim them on Form 306 like earned credits.
A New Jersey S corporation may claim the credit up to its New Jersey CBT liability, but it cannot pass the credit through to its shareholders.
When to file Form 306
Form 306 is submitted with the CBT return for the year the credit was earned; it has no separate due date. The instructions say to include the credit form in the year the credit was earned even if you are not claiming the credit on that return. A completed Form 306 must accompany the CBT-100, CBT-100S or CBT-100U to validate the claim.
Use the version of Form 306 for the tax period you are filing. Do not recompute credits from prior privilege periods or tax years on this form; carryforwards are entered on line 29 as calculated under the law in effect for that period.
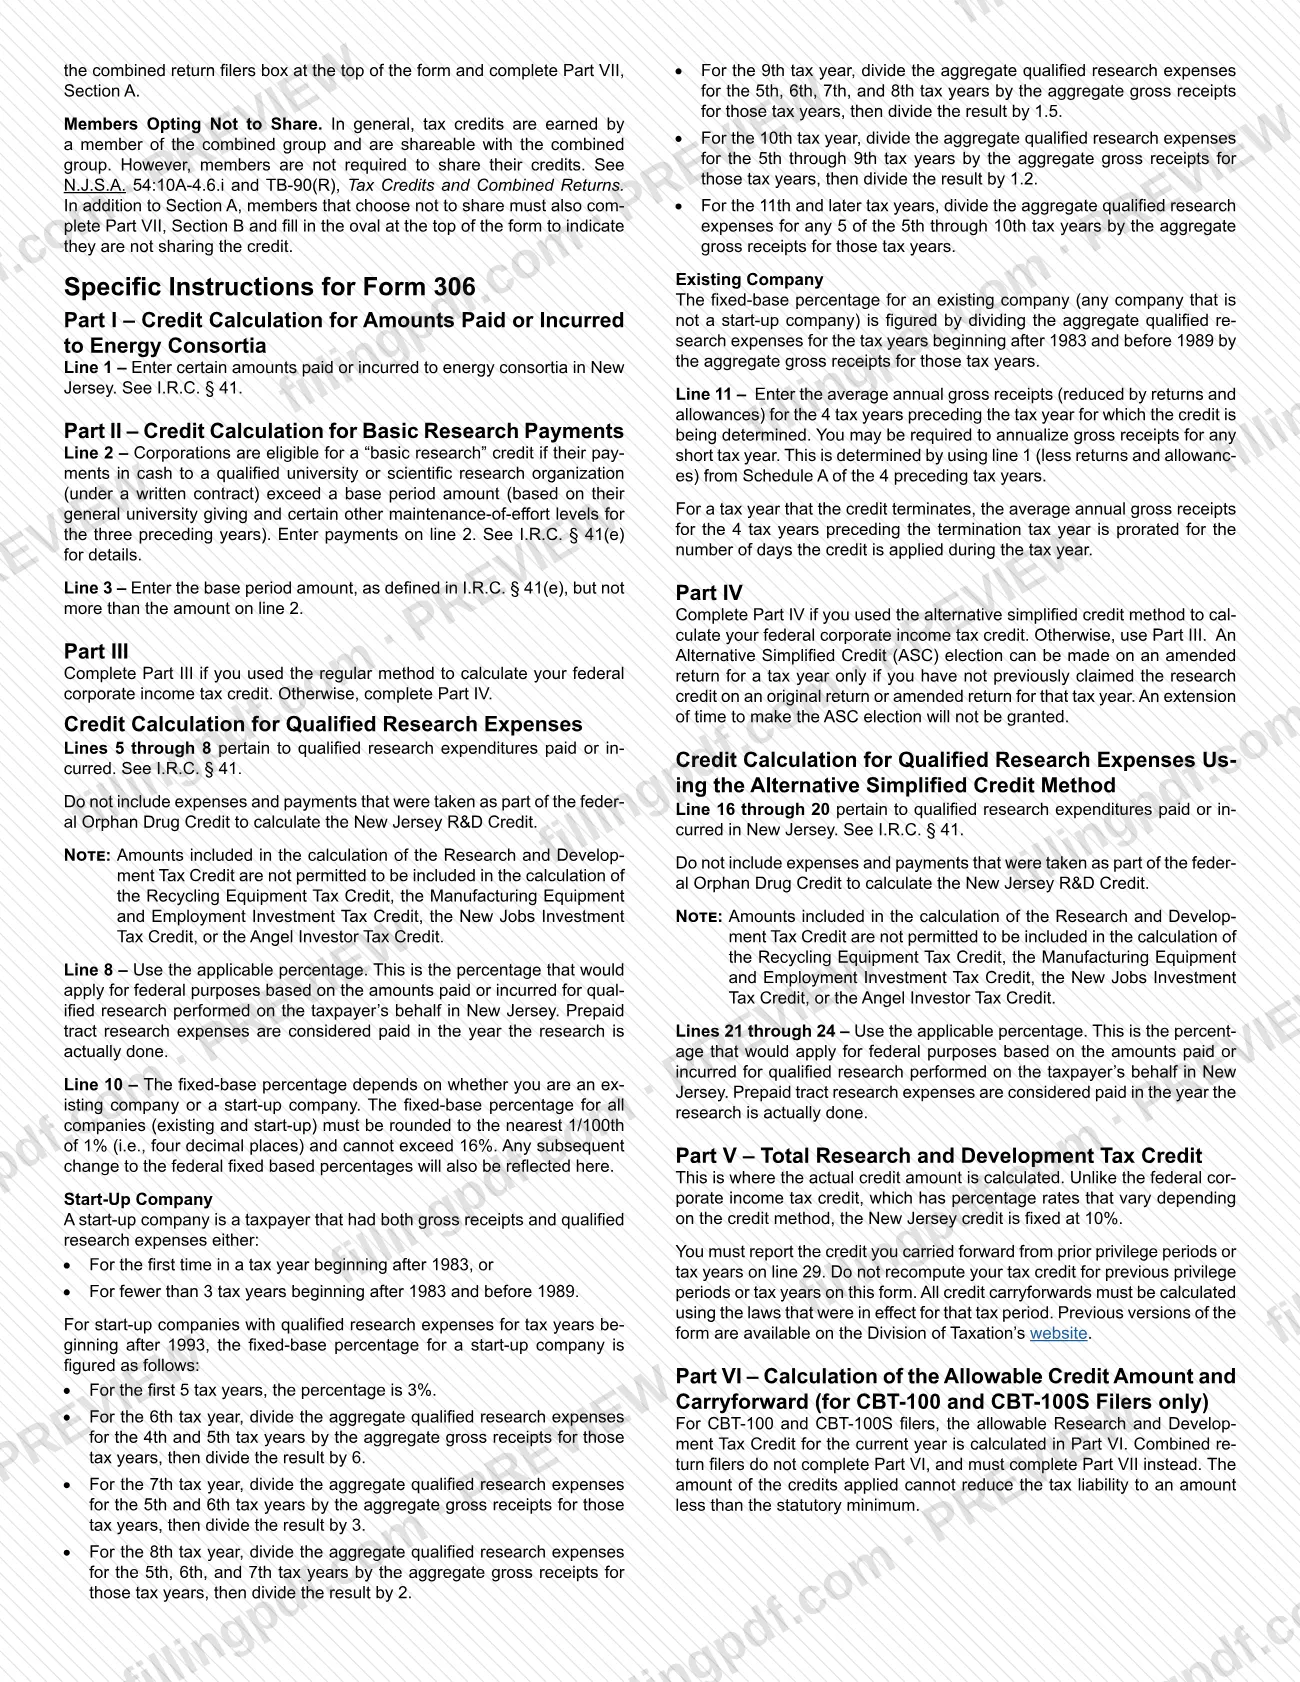
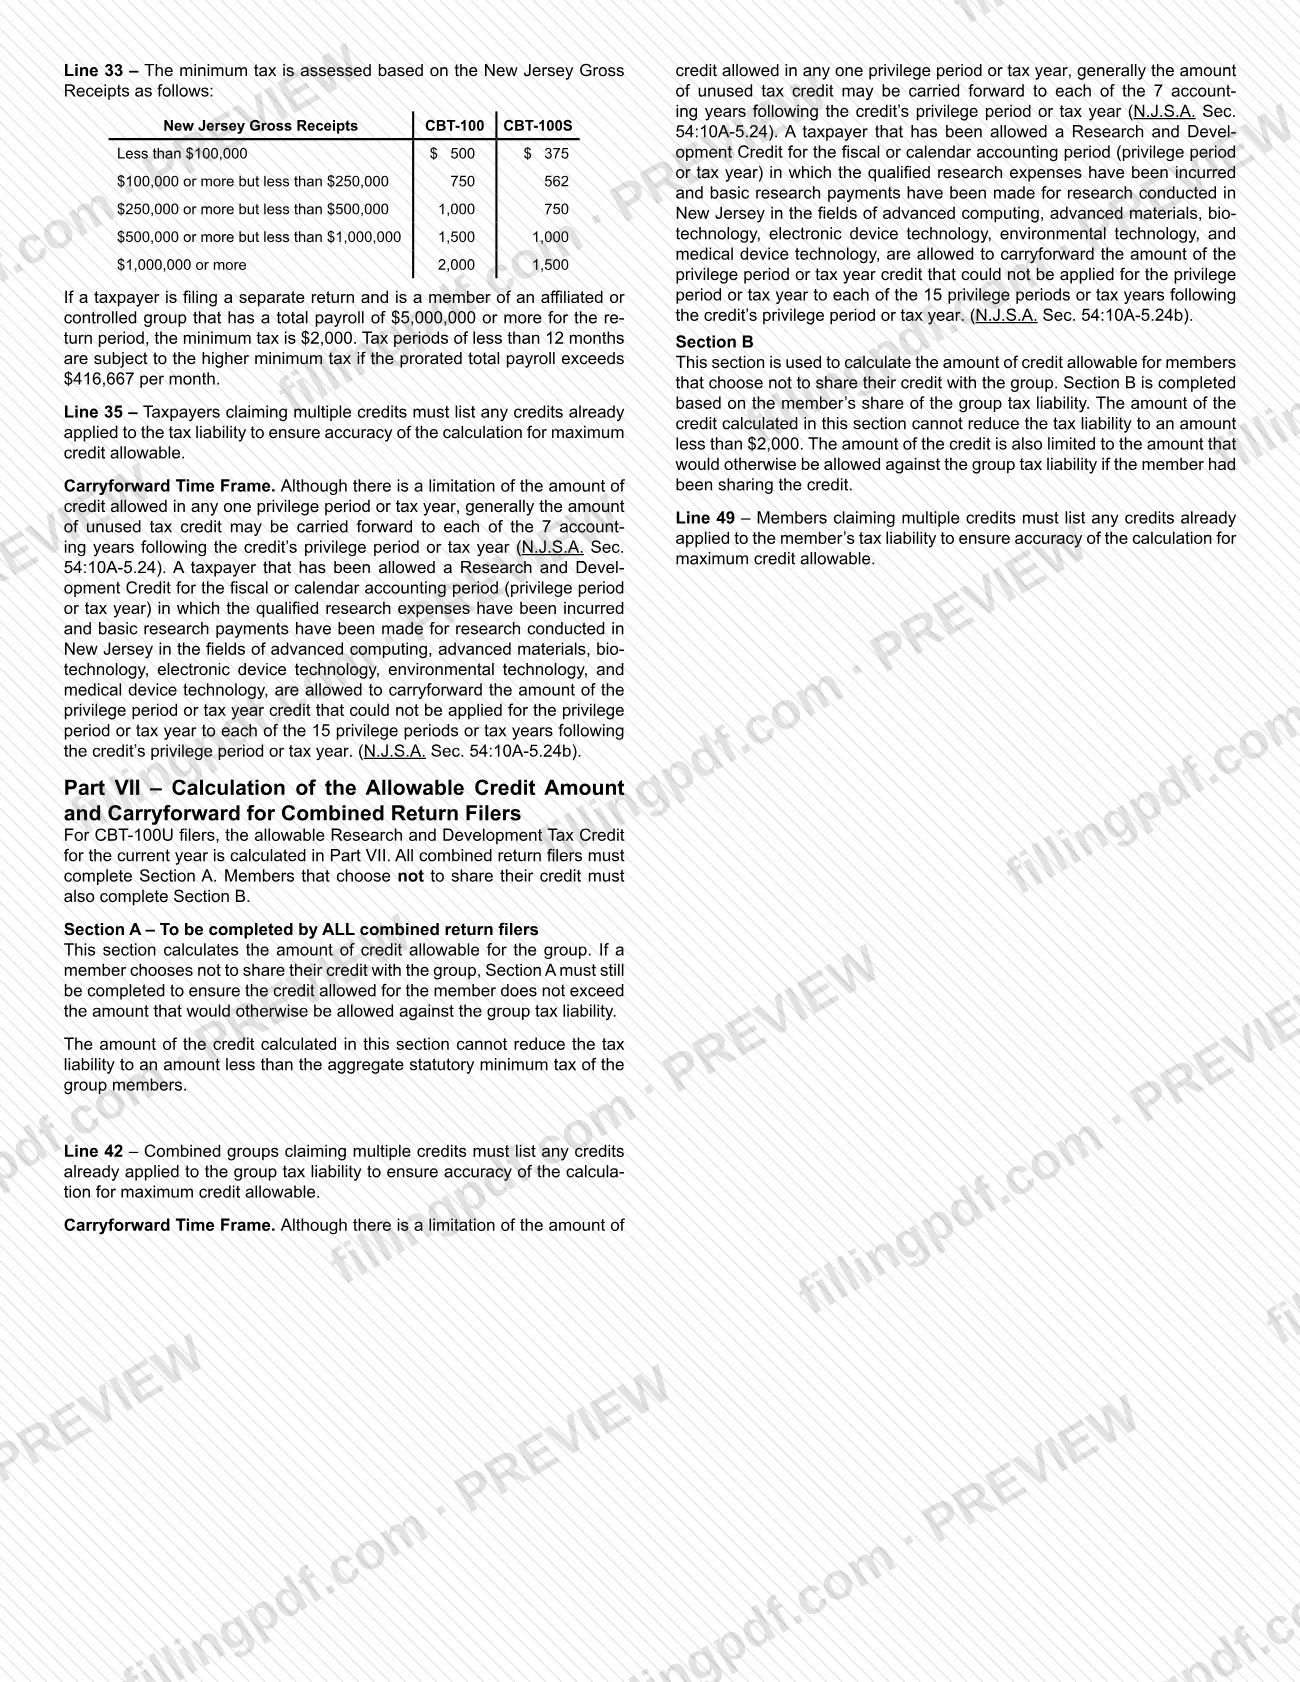
An unused credit generally carries forward for 7 years following the credit's privilege period or tax year. Credits for certain research carry forward 15 years: advanced computing, advanced materials, biotechnology, electronic device technology, environmental technology and medical device technology.
Documents you need
- Copy of federal Form 6765 as filed with the IRS, enclosed with Form 306. Cannabis licensees follow Part II, question 3 instead.
- A detailed rider explaining the calculations, required of a registered cannabis licensee claiming qualified research expenses that were disallowed for the federal credit.
- Schedule NJK-1 stating the credit share, attached by a corporate partner claiming a credit from a partnership.
- A statement on the corporate partner's Schedule NJK-1, Part IV, Supplemental Information, with that partner's share of the qualifying activities and credit, included by a partnership.
- A copy of the transfer certificate, if you claim credits purchased through the Economic Development Authority's Technology Business Tax Certificate Transfer Program.
How to fill out Form 306
Enter taxpayer identification
At the top, enter the name as shown on your return, your Federal ID Number and the Unitary ID Number, if applicable. Check the combined return filer box if you are a taxable member of a combined return, and fill in the oval if you are not sharing your credit.
Check the research field box
Check the box if you are engaged in a research field or industry defined in N.J.S.A. 54:10A-5.24b.
Complete Part I for energy consortia
On line 1, enter certain amounts paid or incurred to energy consortia in New Jersey. See I.R.C. § 41.
Complete Part II for basic research
Enter basic research payments to qualified organizations on line 2 and the base period amount on line 3 (not more than line 2). Subtract line 3 from line 2 on line 4, entering zero if the result is zero or less.
Answer the method questions
Answer questions 1 to 3 in Part II to choose Part III (regular credit method) or Part IV (alternative simplified credit method), matching your federal method. Cannabis licensees answering Yes to question 3 follow the rule for the method they would have used.
Complete Part III if regular method
Enter wages, supplies, computer rental costs and contract research on lines 5 to 8, and total them on line 9. Complete lines 10 to 15, with the fixed-base percentage on line 10 not above 16% and average annual gross receipts on line 11, then skip Part IV.
Complete Part IV if ASC method
Enter lines 16 to 19 and total them on line 20. Enter prior 3 years' qualified research expenses on line 21, divide by 6.0 on line 22, subtract on line 23, and enter the result on line 24.
Calculate the total credit in Part V
Enter lines 1 and 4 on lines 25a and 25b, total them on 25c, and enter line 15 or line 24 on line 26. Add lines 25c and 26 on line 27, and multiply by 10% on line 28.
Add carryforwards and partnership credits
On line 29, enter the credit carried forward from prior years without recomputing it. On line 30, list credits shown on NJK-1(s) received, then add lines 28 through 30 on line 31.
Complete Part VI if CBT-100 or CBT-100S
Enter tax liability on line 32, the required minimum tax liability on line 33, other credits used on line 35, and the allowable credit on line 37 (the lesser of line 31 or line 36). Line 38 is the carryforward.
Complete Part VII if combined filer
Combined return filers skip Part VI. Complete Section A, lines 39 to 45, and if not sharing the credit, Section B, lines 46 to 52.
Review and download the completed PDF
Check that the method matches your federal calculation and that every line carries over correctly. Download or print the completed PDF from FillingPDF and assemble it with the return and the federal Form 6765 copy as described under How to submit.
How to submit Form 306
Form 306 is not filed on its own: you submit it with your New Jersey Corporation Business Tax return. The form prints no separate address or portal.
- With a CBT-100, CBT-100S or CBT-100U: include the completed Form 306 with the return, together with a copy of federal Form 6765 as filed with the IRS.
- Partnerships: attach Form 306 to the NJ-CBT-1065, and include on each corporate partner's Schedule NJK-1, Part IV, Supplemental Information, a statement of that partner's share of the qualifying activities and credit.
- Corporate partners: attach Form 306 to the CBT return along with the NJK-1 that states your share of the credit.
- Purchased credits: attach a copy of the transfer certificate.
Follow the filing method and address in the instructions for the return you are submitting. FillingPDF lets you fill out and download the PDF; submission follows the Division of Taxation's channels for that return.
Common mistakes to avoid
- Recomputing credits for prior privilege periods or tax years on this form; the form says not to, and line 29 is carried forward without recomputation.
- Using a different calculation method than the one used for the federal credit, such as completing Part III when you used the alternative simplified credit method federally.
- Making entries in both Part III and Part IV; if you used the alternative simplified credit method, make no entries in Part III.
- Leaving out the copy of federal Form 6765 as filed with the IRS, except where a cannabis licensee follows Part II, question 3.
- Including wages used to compute the Federal Jobs Credit on lines 5 or 16, or expenses taken for the federal Orphan Drug Credit.
- Including amounts also used for the Recycling Equipment, Manufacturing Equipment and Employment Investment, New Jobs Investment or Angel Investor tax credits.
- Entering a fixed-base percentage above 16% on line 10.
- Completing Part VI as a combined return filer; combined filers continue with Part VII instead.
- Counting research performed outside New Jersey; the credit applies only to research performed in New Jersey.
- Using a prior-year version of Form 306 for the tax period being filed.
Frequently asked questions
What is the research and development tax credit on Form 306?
It is the New Jersey Corporation Business Tax credit for increasing research activities, calculated on Form 306. It follows the federal corporate R&D credit methods but is fixed at 10% and applies only to research performed in New Jersey.
Who has to file Form 306?
A corporation claiming a credit for increasing research activities completes Form 306 and submits it with its tax return. Partnerships complete Parts I, II, III or IV, and V; corporate partners complete the form for their share of the credit.
Do I need to attach federal Form 6765 to Form 306?
Yes. Enclose a copy of federal Form 6765 as filed with the IRS, and use the same method you used federally. Cannabis licensees are the exception: they follow Part II, question 3 and attach a detailed rider.
Where do I file Form 306?
Form 306 is submitted with your CBT-100, CBT-100S or CBT-100U return, and with the NJ-CBT-1065 for a partnership. The form prints no separate address or portal, so follow the filing instructions for the return it accompanies.
How long can I carry forward an unused New Jersey R&D credit?
Generally 7 years after the credit's privilege period or tax year. Credits for research in advanced computing, advanced materials, biotechnology, electronic device, environmental or medical device technology carry forward 15 years.
Can I claim the credit if I do not use it this year?
The instructions say to include the credit form in the year the credit was earned even if you are not claiming the credit on that return. A completed Form 306 must accompany the return to validate the claim.
Can an S corporation pass this credit to its shareholders?
No. A New Jersey S corporation may claim the credit up to its New Jersey Corporation Business Tax liability, but pass-through of the credit to shareholders is not permitted.
Can I fill out Form 306 online on FillingPDF?
Yes. You can fill out the 2024 PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the form; you submit it with your return through the Division of Taxation's channels.
Ready to fill out Form 306?
Fill out Form 306 now