
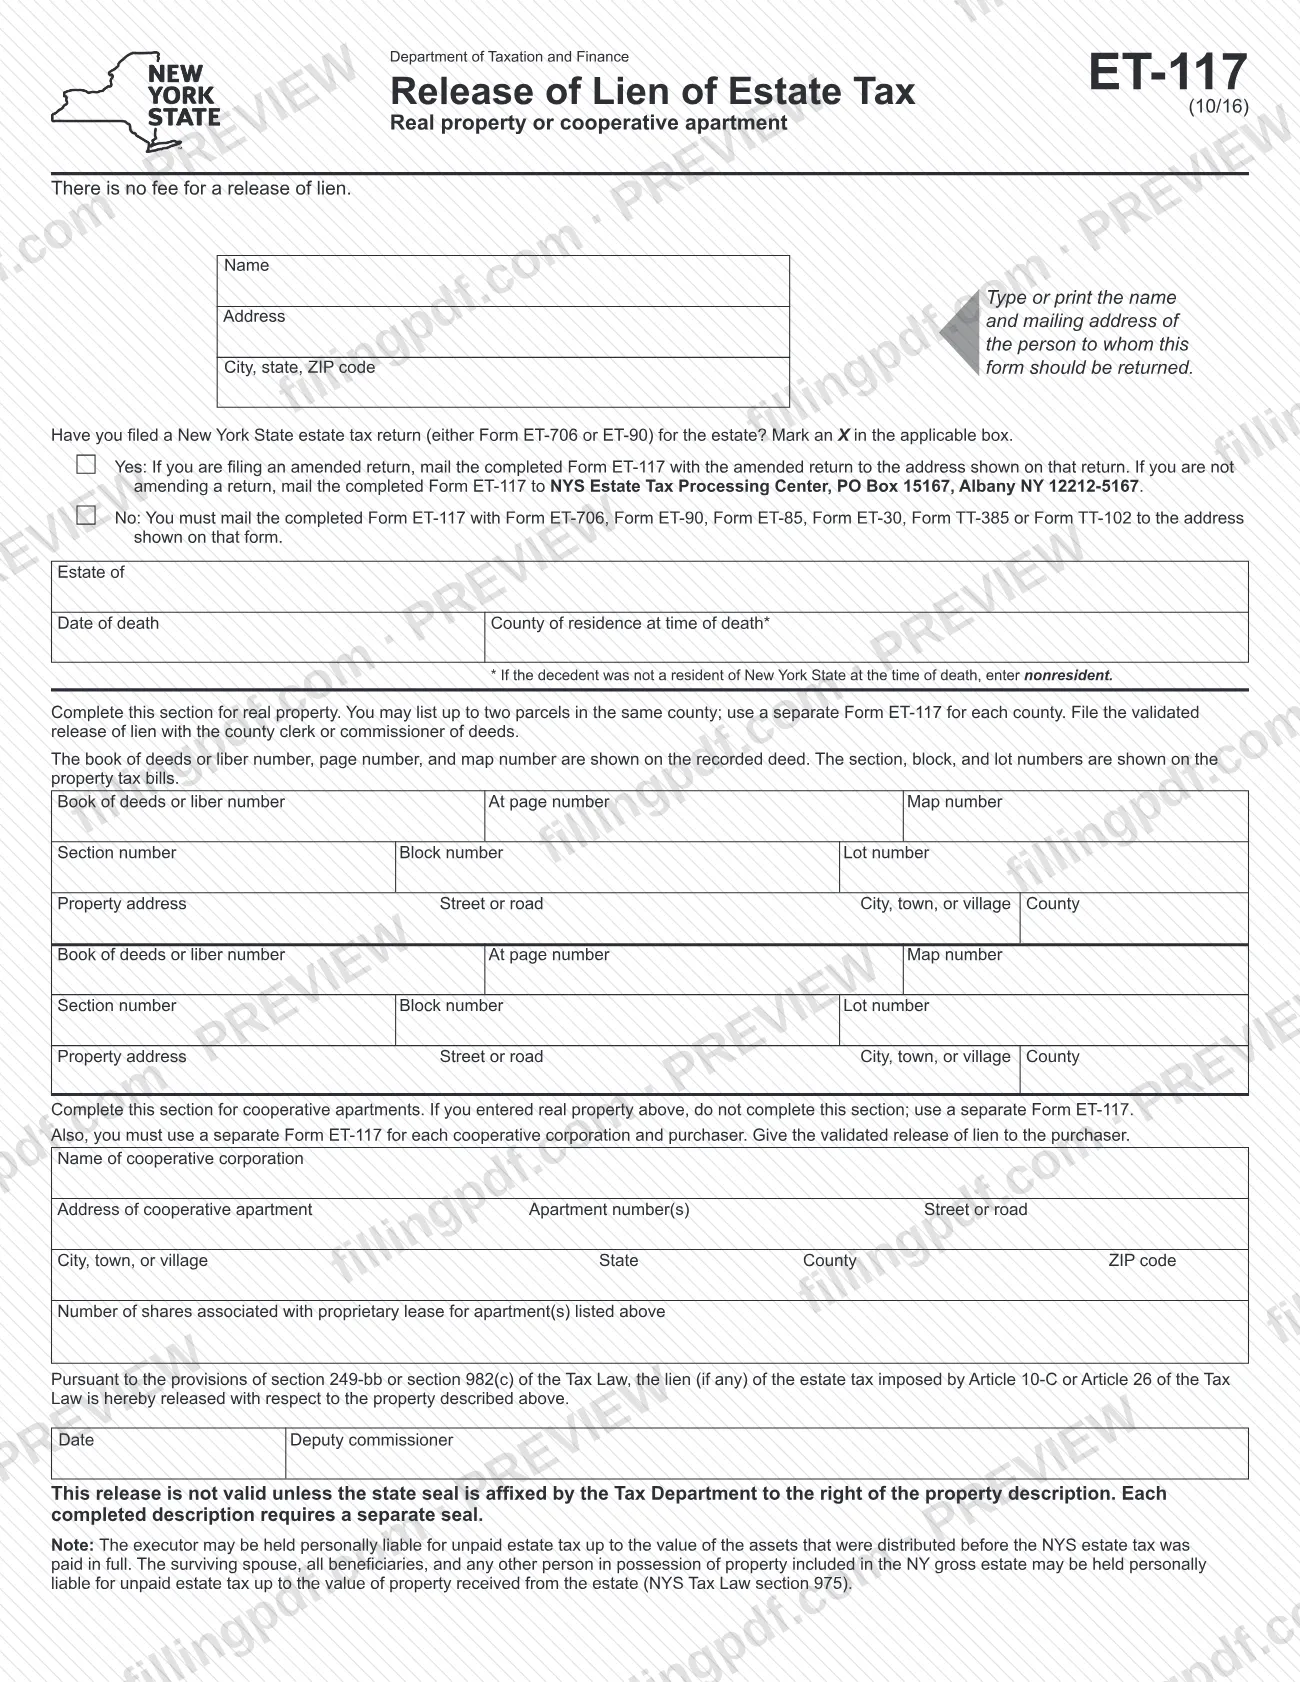
ET-117 is the New York State Department of Taxation and Finance form used to request the release of the estate tax lien, if any, on real property or a cooperative apartment of an estate. It is mailed with the estate tax return or with the other estate tax form it accompanies, and the Tax Department returns a validated release bearing its state seal. On this page you can fill out the form online on FillingPDF and download or print the completed PDF; the official PDF is published by the department at tax.ny.gov.
Last updated
What is ET-117?
Form ET-117, Release of Lien of Estate Tax, is the New York State Department of Taxation and Finance form that identifies real property or a cooperative apartment of an estate so the Tax Department can release the estate tax lien, if any, on that property.
The release rests on section 249-bb or section 982(c) of the Tax Law and covers the lien of the estate tax imposed by Article 10-C or Article 26 of the Tax Law. The form is titled "Real property or cooperative apartment" because it has two alternative sections: one for real property (up to two parcels in the same county) and one for a cooperative apartment.
The form is not valid as a release until the Tax Department affixes its state seal to the right of the property description. Each completed description requires a separate seal. The Tax Department signs through a deputy commissioner and returns the validated release to the person whose name and address you enter at the top.
There is no fee for a release of lien. The form also carries a warning: the executor may be held personally liable for unpaid estate tax up to the value of assets distributed before the New York State estate tax was paid in full, and the surviving spouse, beneficiaries and anyone in possession of property in the New York gross estate may be liable up to the value of property received (Tax Law section 975).
Who needs to file ET-117?
Anyone handling the estate of a decedent who needs a release of the New York estate tax lien on real property or on a cooperative apartment uses Form ET-117. The form asks for the name of the estate, the date of death and the county of residence at death, which is entered as "nonresident" if the decedent did not live in New York State.
- Real property: list up to two parcels in the same county. Use a separate Form ET-117 for each county.
- Cooperative apartment: use a separate Form ET-117 for each cooperative corporation and each purchaser. If you entered real property on the form, do not complete the cooperative section; use another Form ET-117.
The form does not name who must sign a request or who may act for the estate. It does say the person to whom the form should be returned is the one you list in the name and address block at the top.
When to file ET-117
Form ET-117 is sent together with an estate tax filing, so the trigger is the estate tax return or form it travels with. The form prints no separate due date.
- If you have already filed a New York State estate tax return (Form ET-706 or ET-90) and are not amending it, mail the completed ET-117 on its own to the NYS Estate Tax Processing Center.
- If you are filing an amended return, mail the ET-117 with the amended return.
- If you have not filed, mail the ET-117 with Form ET-706, Form ET-90, Form ET-85, Form ET-30, Form TT-385 or Form TT-102.
Once the Tax Department returns the validated release, file it as the form directs (see How to submit). The form gives no processing time.
Documents you need
- Form ET-706 or Form ET-90 (the New York State estate tax return), if you have not yet filed one: mail the ET-117 with it to the address shown on that form.
- An amended estate tax return, if you are amending a return you already filed: mail the ET-117 with it to the address shown on that return.
- Form ET-85, Form ET-30, Form TT-385 or Form TT-102, when you have not filed an estate tax return and one of these is the form you are filing: the ET-117 goes with it.
- The recorded deed, for real property: it shows the book of deeds or liber number, page number and map number to enter.
- The property tax bills, for real property: they show the section, block and lot numbers to enter.
How to fill out ET-117
Enter the return address
At the top, type or print the name and the address and mailing address (city, state, ZIP code) of the person to whom the form should be returned.
Mark the estate tax return box
Mark an X in Yes if you have filed a New York State estate tax return (Form ET-706 or ET-90) for the estate, or No if you have not. The box you mark decides where the form is mailed.
Identify the estate
Enter the Estate of name, the date of death and the county of residence at time of death. If the decedent was not a New York State resident, enter nonresident.
Describe the first real property parcel
Enter the book of deeds or liber number, page number and map number from the recorded deed, and the section, block and lot numbers from the property tax bills. Then give the property address: street or road, city, town or village, and county.
Add a second parcel if needed
You may list one more parcel in the same county with the same fields. Use a separate Form ET-117 for each county.
Complete the cooperative section instead
Use this section only if you entered no real property. Enter the name of the cooperative corporation, the address of the apartment with apartment number(s), city, state, county and ZIP code, and the number of shares associated with the proprietary lease.
Leave the release block to the Tax Department
The release statement, date and deputy commissioner line belong to the Tax Department, which must affix the state seal to the right of the property description for the release to be valid.
Review and download the completed PDF
Check the parcel or apartment details and the box you marked. Download or print the completed PDF from FillingPDF and mail it as described under How to submit.
How to submit ET-117
Form ET-117 is submitted by mail to the Tax Department, and the destination depends on the box you mark for the question about the estate tax return.
- Yes (return already filed), not amending: mail the completed Form ET-117 to NYS Estate Tax Processing Center, PO Box 15167, Albany NY 12212-5167.
- Yes, filing an amended return: mail the completed Form ET-117 with the amended return to the address shown on that return.
- No (return not yet filed): mail the completed Form ET-117 with Form ET-706, Form ET-90, Form ET-85, Form ET-30, Form TT-385 or Form TT-102 to the address shown on that form.
There is no fee for a release of lien. After the Tax Department validates the release with its state seal, file the validated release of lien for real property with the county clerk or commissioner of deeds. For a cooperative apartment, give the validated release to the purchaser. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Listing more than two parcels, or parcels in different counties, on one form; the form allows up to two parcels in the same county and a separate ET-117 for each county.
- Completing the cooperative apartment section after entering real property; the form says to use a separate ET-117 instead.
- Using one ET-117 for more than one cooperative corporation or purchaser; each cooperative corporation and purchaser needs its own form.
- Mailing the form to the wrong place: the Albany P.O. box is only for an unamended return already filed; an amended return or an unfiled return changes the address.
- Treating an unsealed form as a release; it is not valid unless the Tax Department affixes the state seal, and each completed description requires a separate seal.
- Giving the validated cooperative release to someone other than the purchaser, or filing a real property release somewhere other than with the county clerk or commissioner of deeds.
- Entering a New York county for a decedent who was not a New York resident; the form says to enter nonresident.
- Leaving out the name and mailing address of the person who should receive the returned form.
Frequently asked questions
What is Form ET-117 used for?
Form ET-117 is the New York State Tax Department form for requesting a release of the estate tax lien, if any, on real property or a cooperative apartment of an estate. The lien is the one imposed under Article 10-C or Article 26 of the Tax Law.
Is there a fee for the ET-117 release of lien?
No. The form states that there is no fee for a release of lien.
Where do I mail Form ET-117?
It depends on your estate tax return. If you filed one and are not amending it, mail the ET-117 to NYS Estate Tax Processing Center, PO Box 15167, Albany NY 12212-5167. With an amended return or an unfiled return, mail it with that return or form.
How many properties can I list on one ET-117?
Up to two parcels of real property in the same county. Use a separate Form ET-117 for each county. A cooperative apartment cannot share a form with real property, and each cooperative corporation and purchaser needs its own form.
What do I do with the release after the Tax Department validates it?
For real property, file the validated release of lien with the county clerk or commissioner of deeds. For a cooperative apartment, give the validated release to the purchaser.
Is an ET-117 valid without the state seal?
No. The release is not valid unless the Tax Department affixes the state seal to the right of the property description, and each completed description requires a separate seal.
What do I enter for county if the decedent lived outside New York?
Enter nonresident in the county of residence at time of death. The form says to do this when the decedent was not a New York State resident at the time of death.
Can I fill out ET-117 online?
You can fill out the ET-117 PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not submit the form; you mail it to the Tax Department as the form directs.
Ready to fill out ET-117?
Fill out ET-117 now