
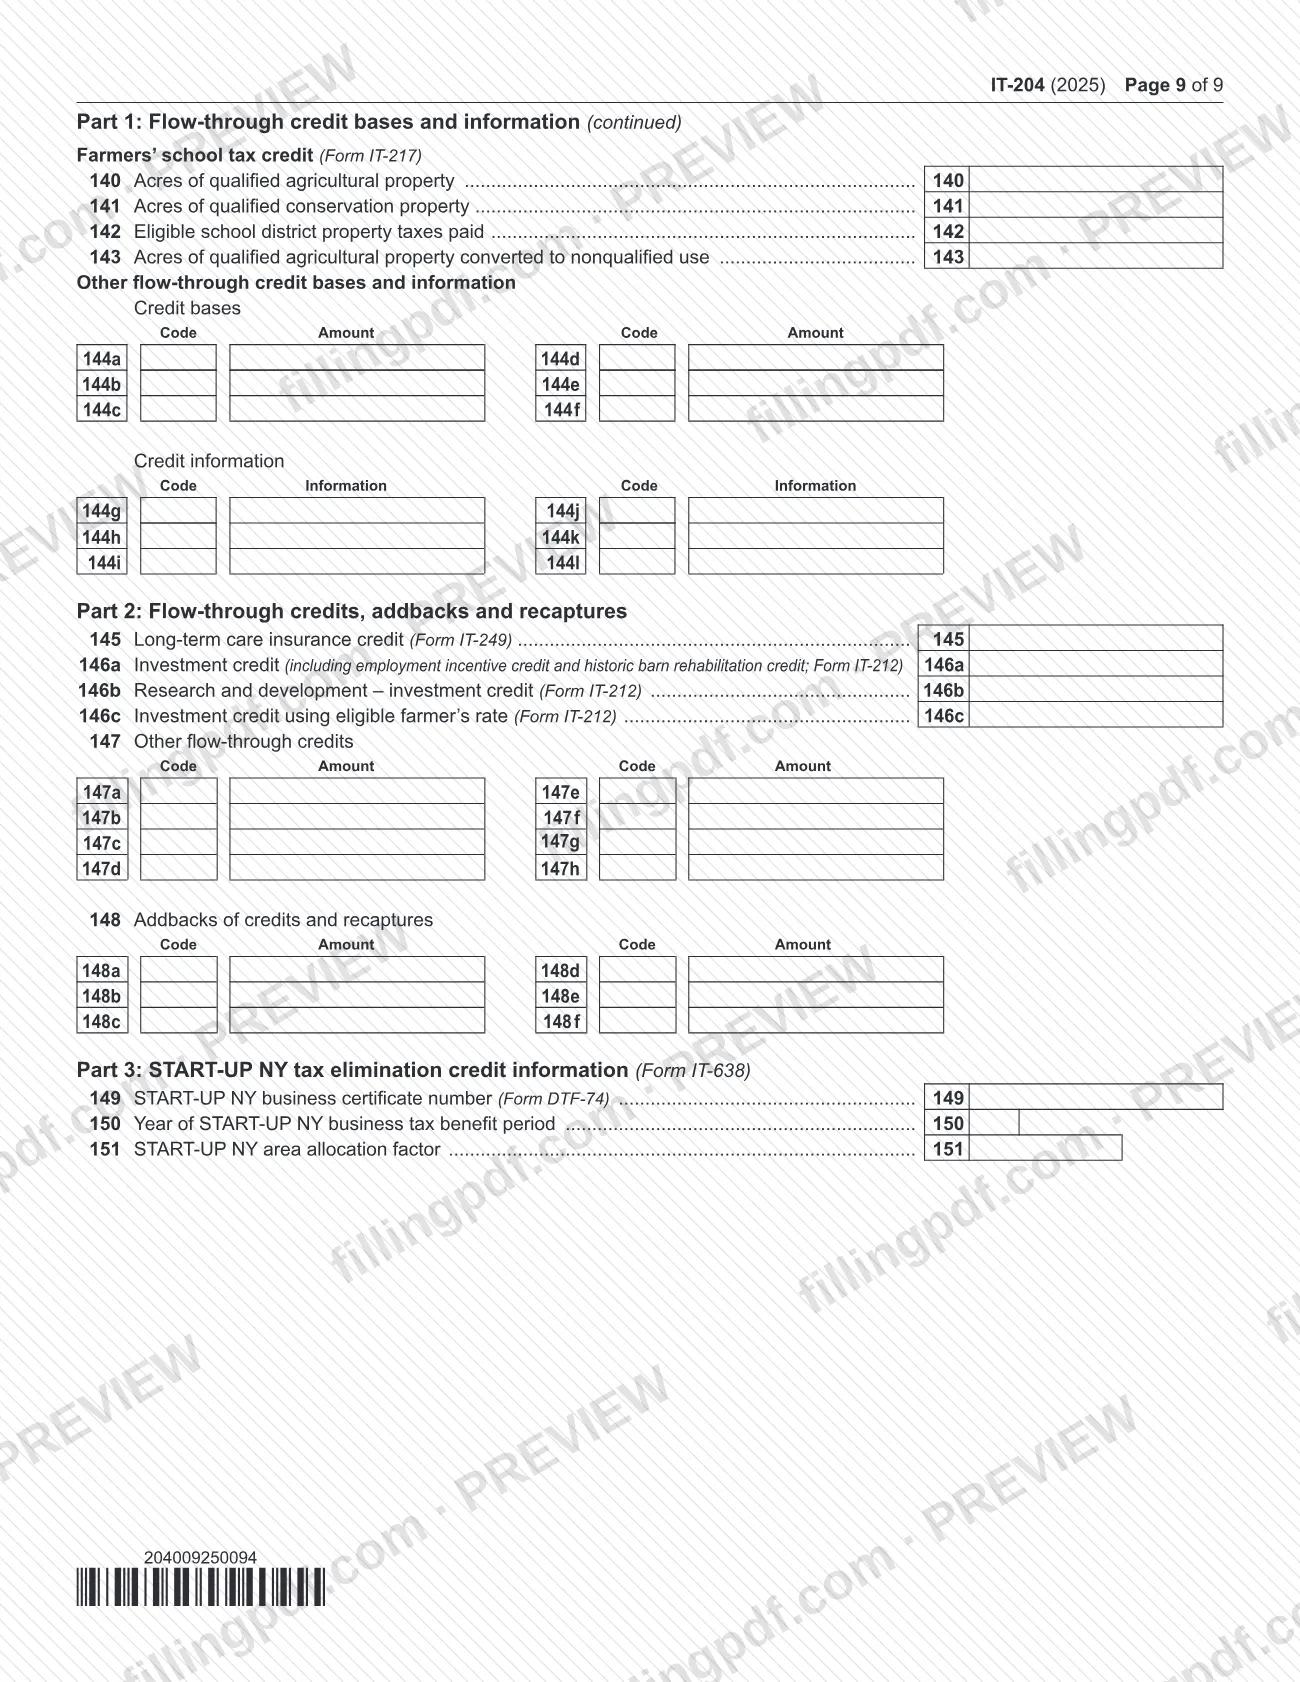
IT-204 is the Partnership Return that the New York State Department of Taxation and Finance requires from partnerships with New York source income or with a New York resident individual, estate or trust partner. It reports the partnership's income, deductions, gains, losses and credits for calendar year 2025 or another tax year beginning in 2025, and it is completed alongside the partner schedules described in Form IT-204-I. On FillingPDF you can fill out the form online and download or print the completed PDF; the Tax Department publishes the official PDF and instructions, and the return is submitted through its channels.
Last updated
What is IT-204?
Form IT-204, Partnership Return, is the New York State form on which a partnership reports income, deductions, gains, losses and credits from the operation of the partnership for calendar year 2025, or another tax year beginning in 2025, to the Department of Taxation and Finance.
Partnerships are not subject to personal income tax, so the return is an information return: it supports the New York returns of the partners. All items reported on the form, or on documents included with it, are subject to verification, audit and revision by the Tax Department. You use the same accounting period and method as on federal Form 1065, U.S. Return of Partnership Income, and most sections transfer amounts from the federal return.
The form has eleven sections:
- Section 1: partnership information and filing questions (items A to Q).
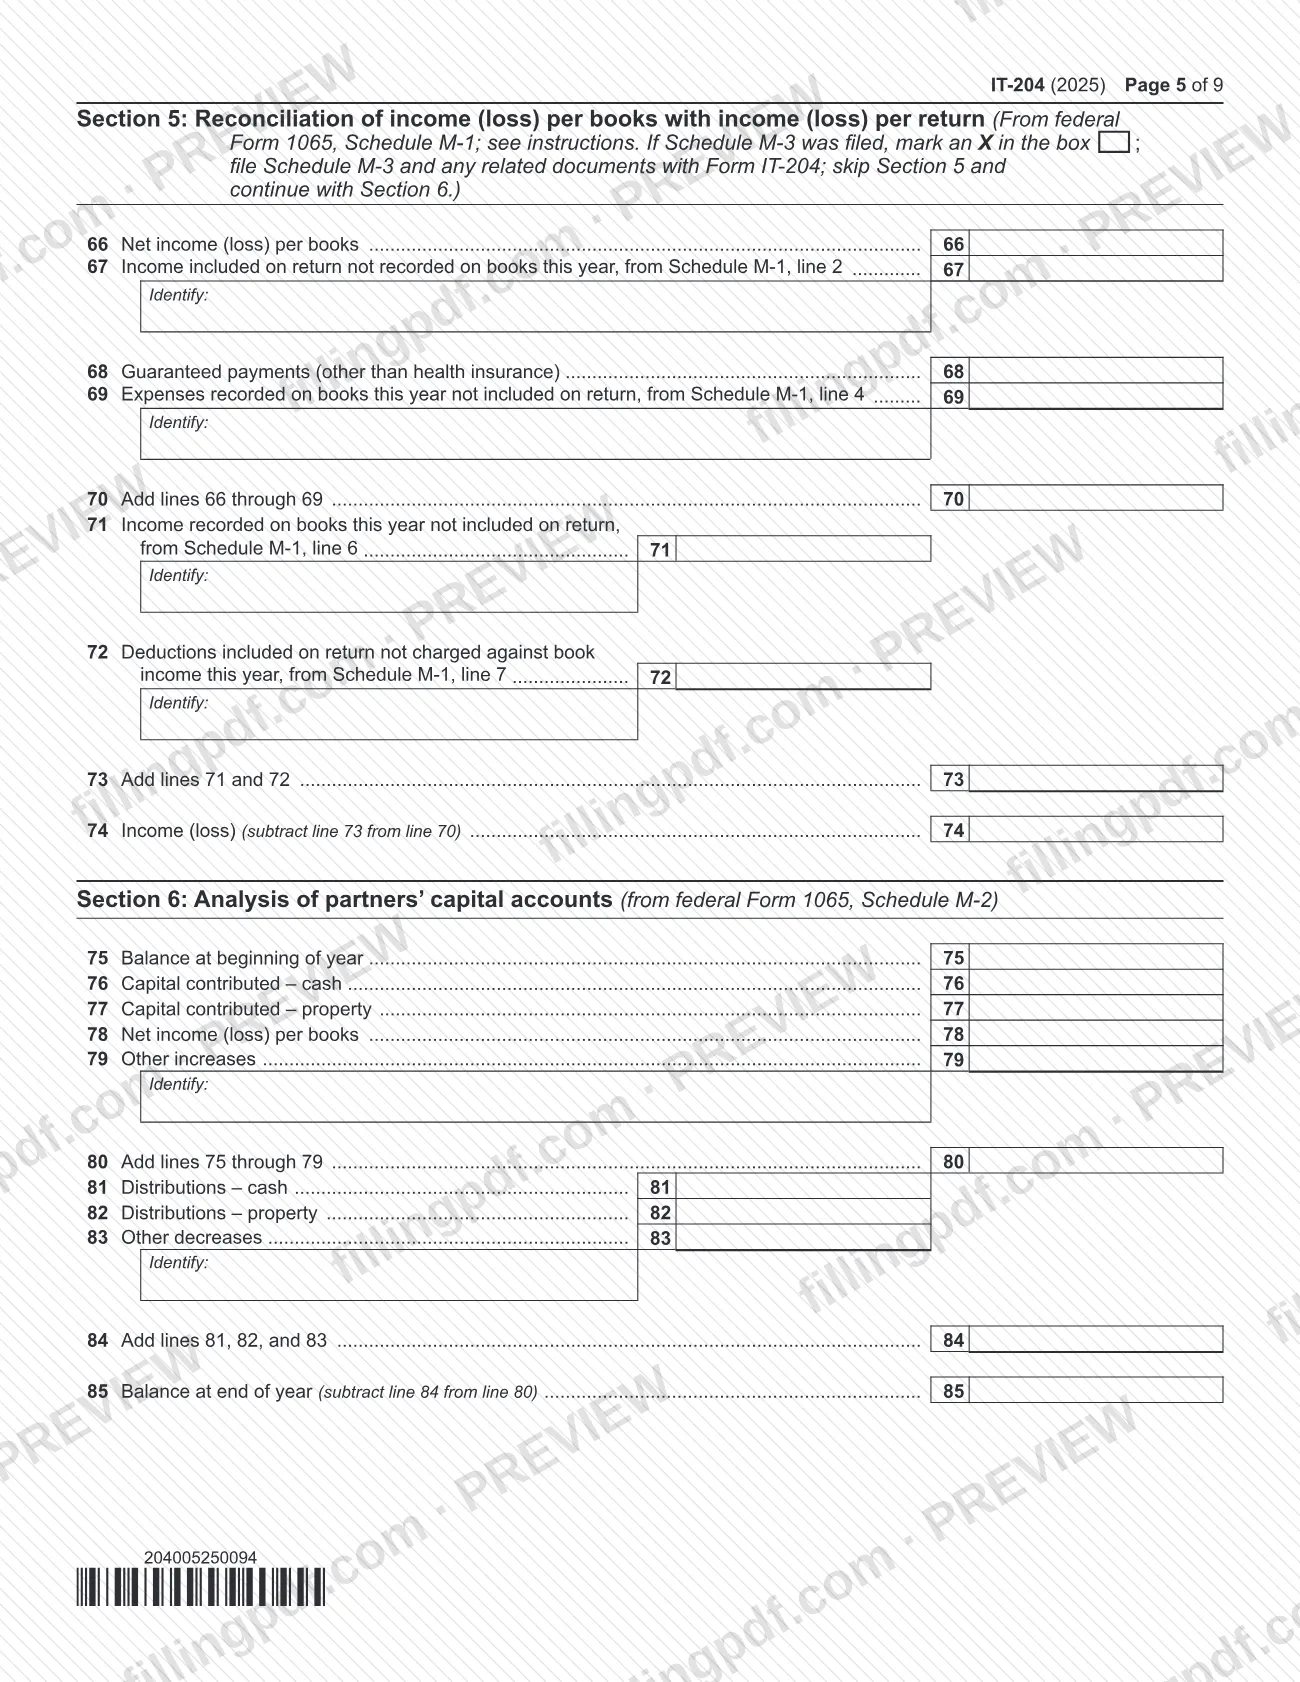
- Sections 2 to 6: federal ordinary business income, cost of goods sold, balance sheets, reconciliation of income and partners' capital accounts (lines 1 to 85).
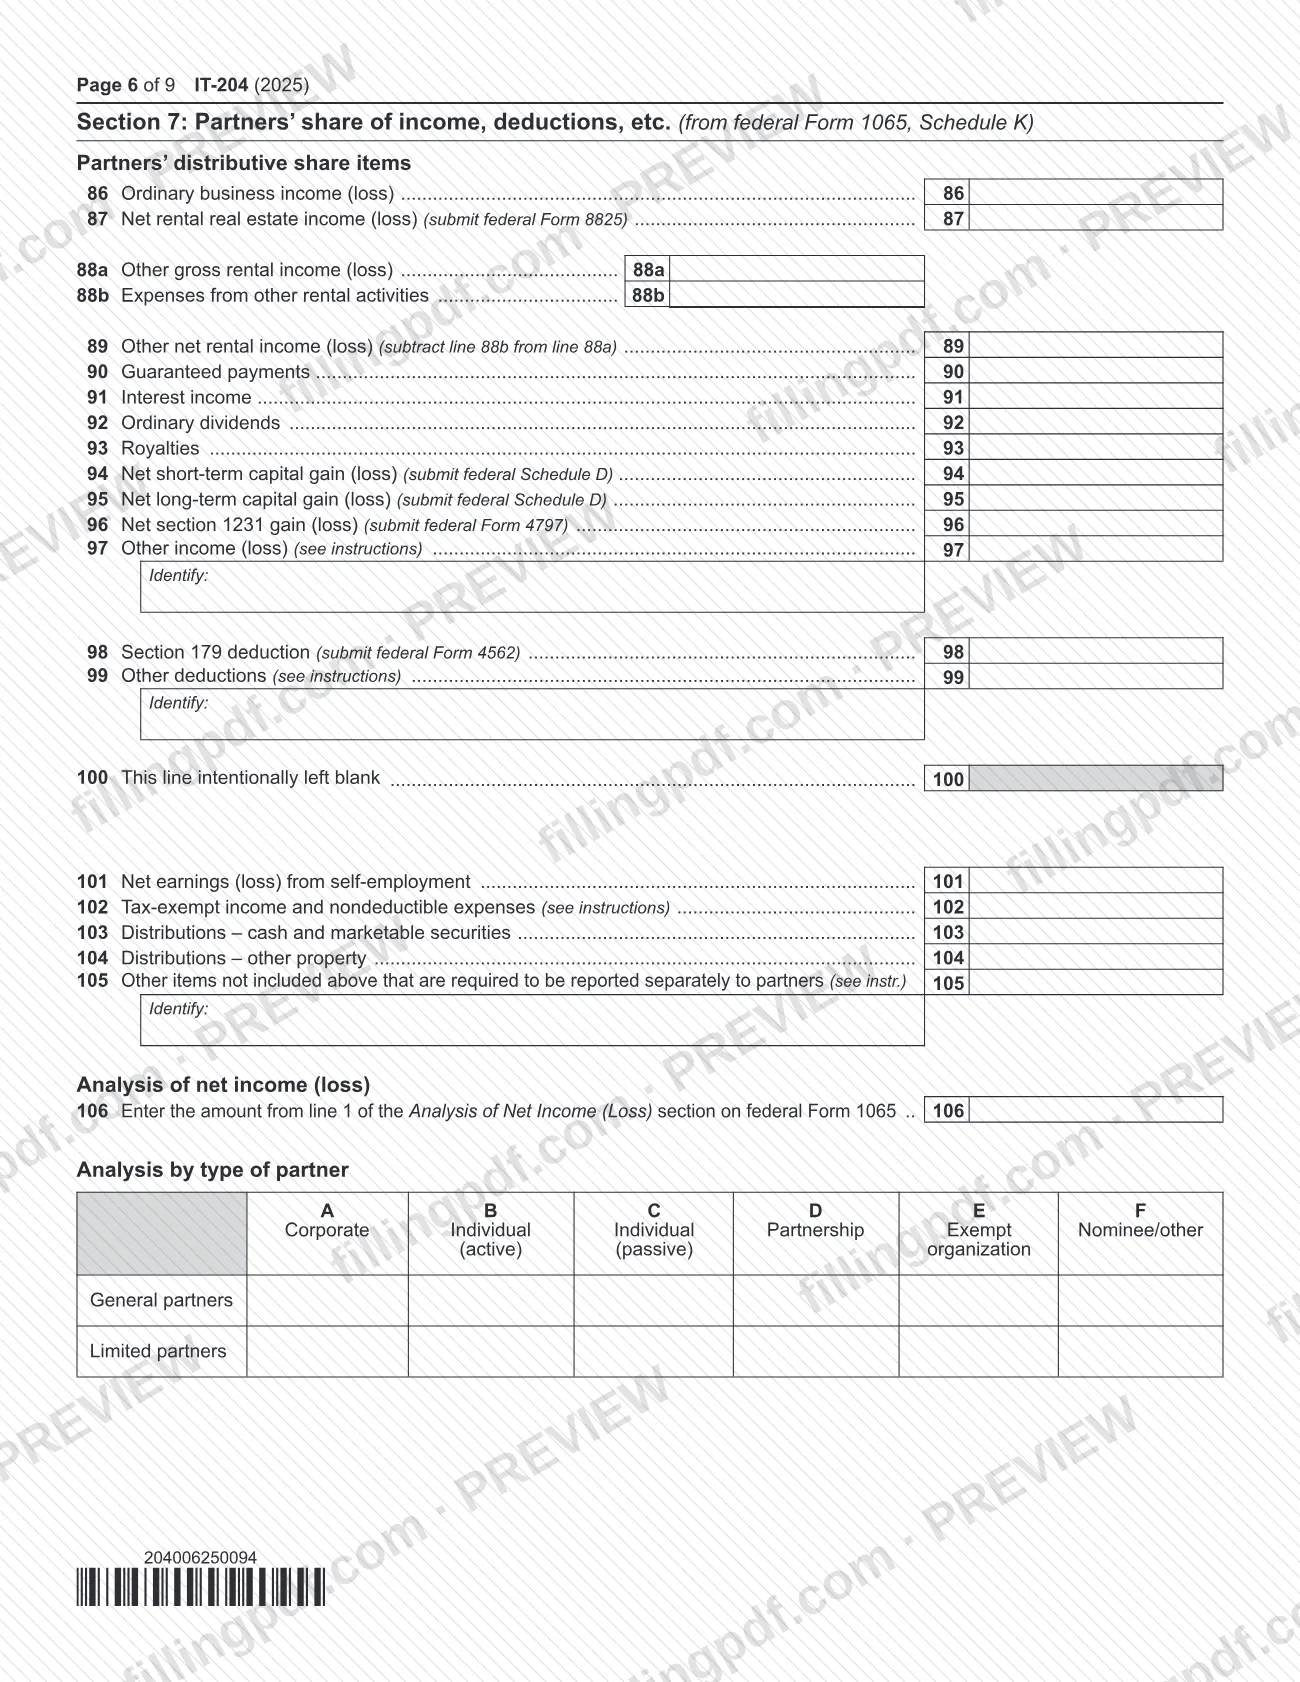
- Section 7: partners' share of income, deductions and other items (lines 86 to 106).
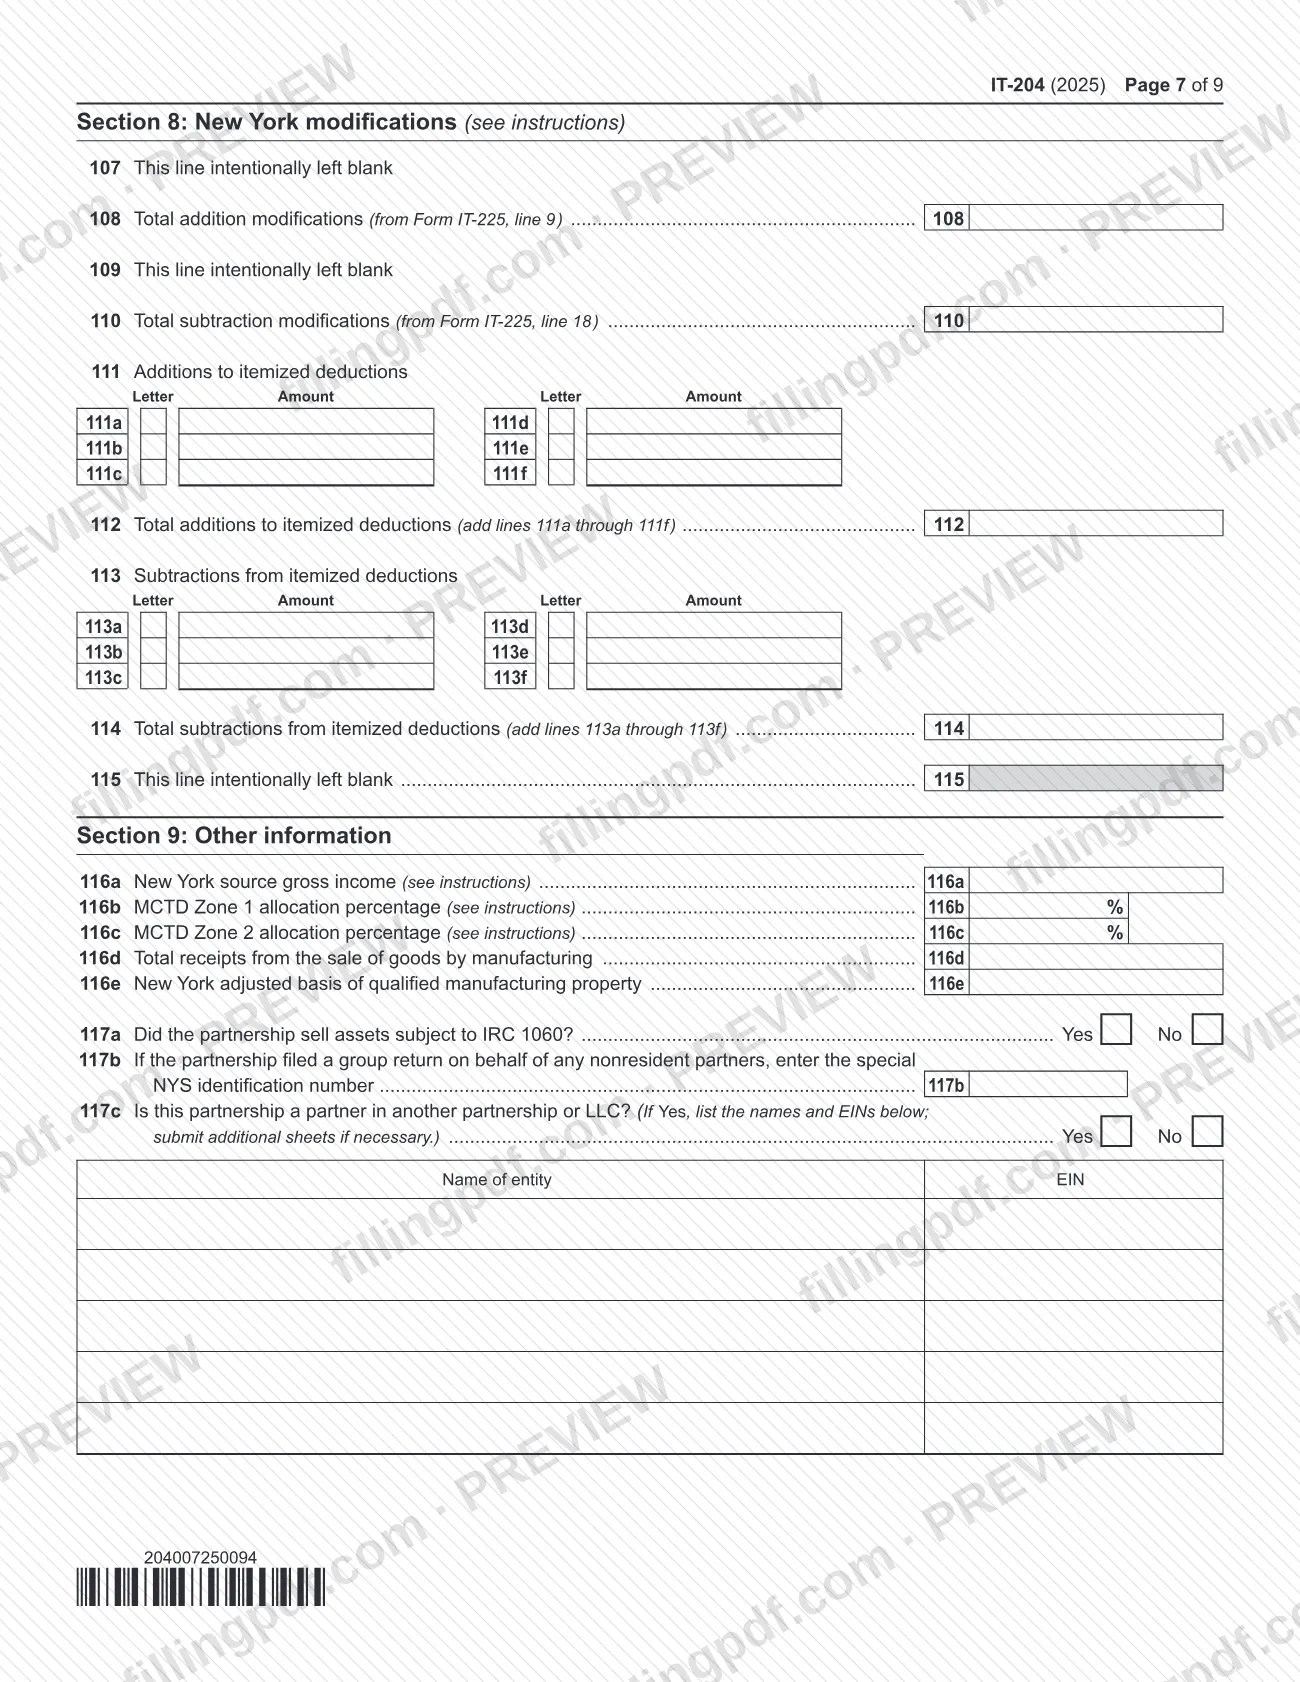
- Sections 8 and 9: New York modifications and other information (lines 107 to 117c).
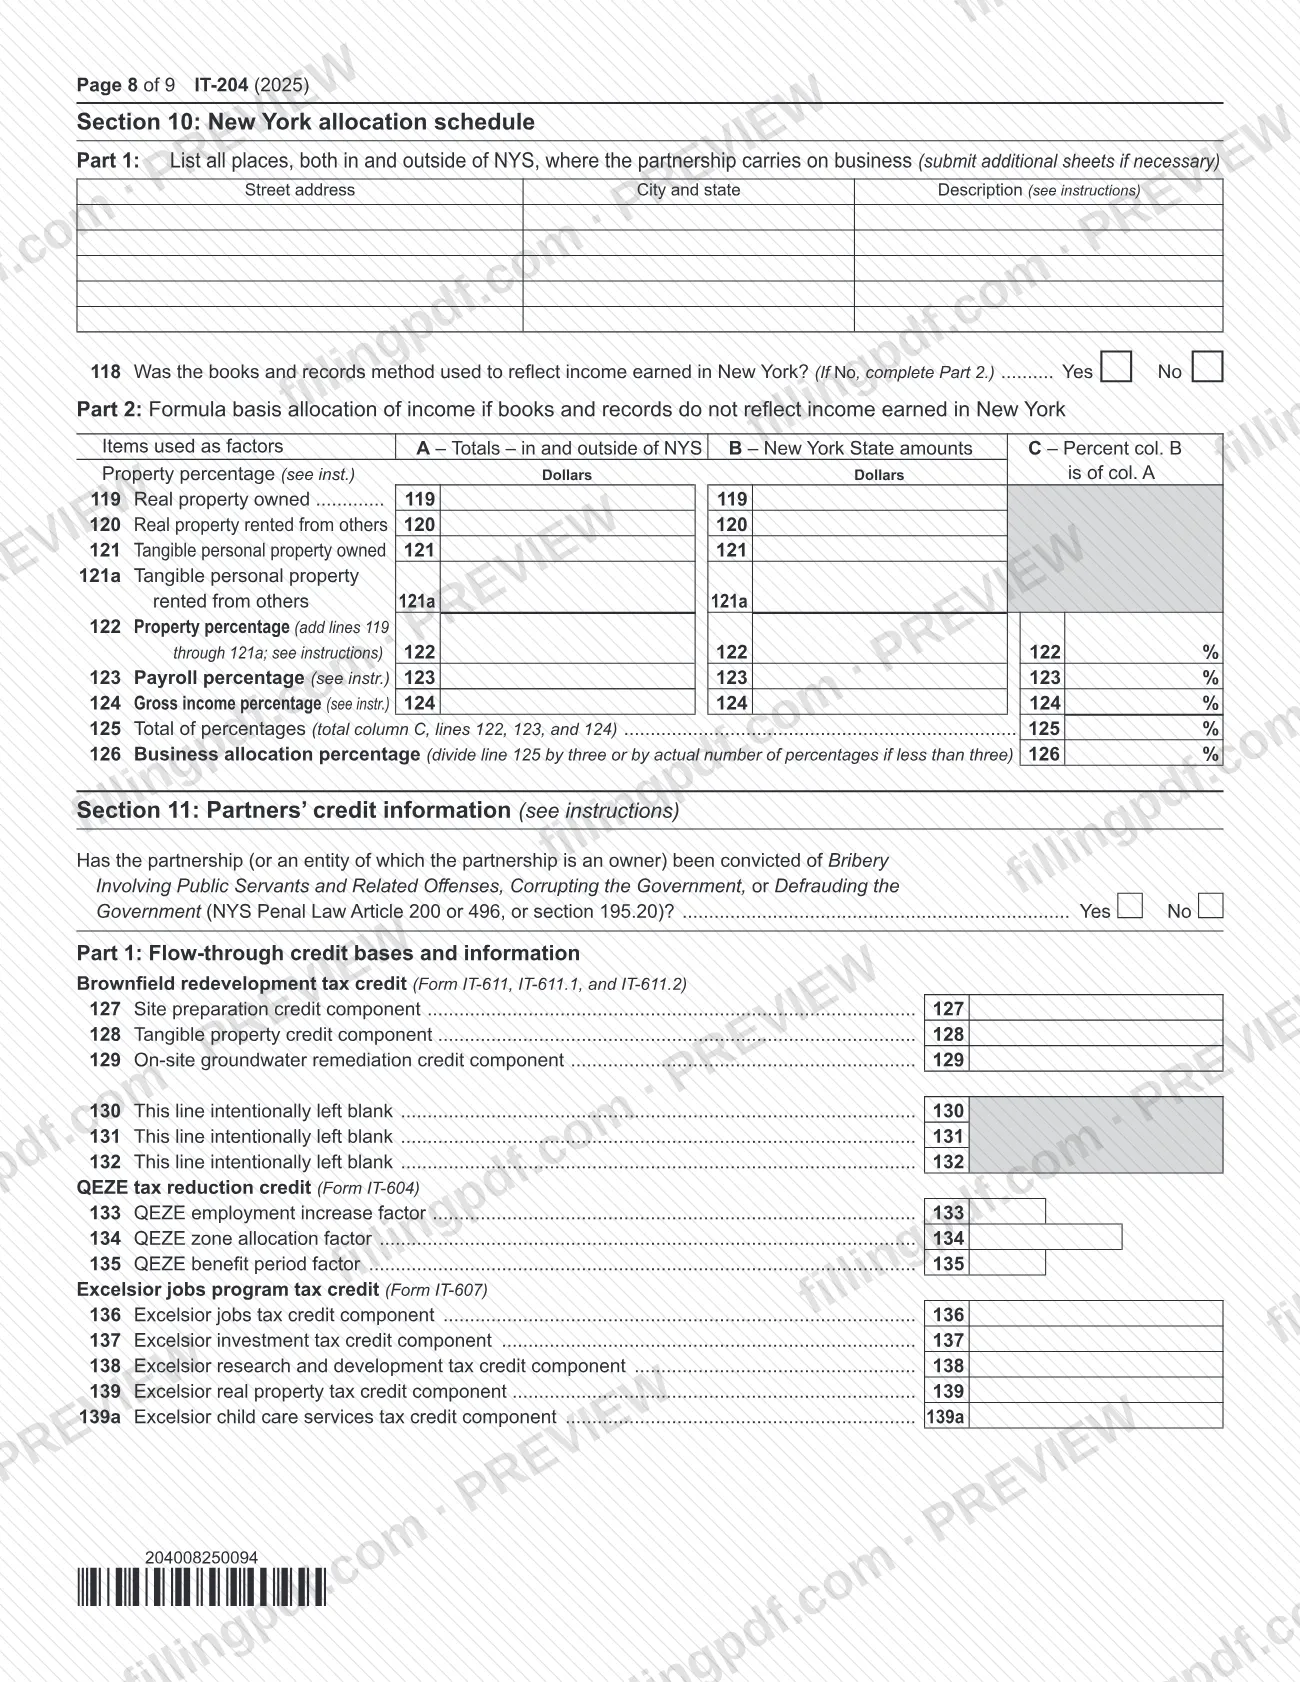
- Section 10: New York allocation schedule (lines 118 to 126).
- Section 11: partners' credit information (lines 127 to 151).
IT-204 comes with partner-level forms: IT-204-IP (New York Partner's Schedule K-1), IT-204-CP (New York Corporate Partner's Schedule K-1) and IT-204.1 (New York Corporate Partners' Schedule K). It is not the New York City unincorporated business tax return, which is Form NYC-204 and is administered by the New York City Department of Finance.
Who needs to file IT-204?
A partnership must file Form IT-204, regardless of the amount of its income, if it has either of the following:
- at least one partner who is an individual, estate or trust that is a resident of New York State; or
- any income, gain, loss or deduction from New York State sources.
A partnership with New York source income completes the entire form. A partnership with no New York source income that files only because of a resident partner completes the whole form except Section 10, and submits a statement saying it has no New York source income, that all other Article 22 partners are nonresidents, and the total number of nonresident partners.
New York law does not require a partnership to file solely because one of its partners is a partnership or corporation formed under New York law; that partner may still have its own return to file.
Additional forms depend on the partner type. Individuals, estates and trusts receive Form IT-204-IP. Partners that are partnerships or LLCs treated as partnerships receive both IT-204-IP and IT-204-CP, and only IT-204-IP goes with the return. Corporate partners taxable under Article 9-A need IT-204-CP, and Form IT-204.1 is required when there is a corporate partner or a partner that is a partnership or LLC.
A general partner signs the return. If you pay someone to prepare it, the paid preparer also signs.
When to file IT-204
File calendar year 2025 returns on or before March 16, 2026. Fiscal-year returns are due on or before the 15th day of the third month after the end of the tax year. If the partnership is terminated and completely liquidated during its normal tax year, producing an accounting period shorter than 12 months for federal purposes, the return is due the 15th day of the third month after that period ends.
You may request an automatic extension of time to file by the due date; the instructions send you to www.tax.ny.gov (search: extension).
Amended returns have their own clock. If federal changes result from an amended or superseding federal partnership return, a federal audit or an administrative adjustment request, file the amended New York return within 90 days of filing the federal amended return or of the final determination. A penalty applies if a required return is late, incomplete or an amended return is not filed within 90 days, unless the failure is due to reasonable cause and not willful neglect.
The 2025 form may also be used for a tax year of less than 12 months beginning and ending in 2026 if the 2026 form is not yet available.
Documents you need
- Form IT-204-IP, New York Partner's Schedule K-1, for each Article 22 resident partner, and for each partner that is a partnership or LLC; not required for nonresident partners unless the Tax Department requests it in an audit.
- Form IT-204-CP, New York Corporate Partner's Schedule K-1, for each corporate partner taxable under Article 9-A.
- Form IT-204.1, New York Corporate Partners' Schedule K, when the partnership has a corporate partner or a partner that is a partnership or LLC.
- Form IT-225 results for lines 108 and 110, which take the addition and subtraction modification totals from that form.
- A copy of federal Schedule M-3 and related documents, if it was filed with Form 1065; mark the box in Section 5 and skip Section 5.
- Statements and federal forms named on specific lines, such as Form 1040 Schedule F (line 7), Form 4797 (lines 8 and 96), Form 4562 (lines 18 and 98), Form 8825 (line 87) and Schedule D (lines 94 and 95).
- Forms DTF-686 and DTF-686-ATT, and any applicable federal forms, if you answer Yes to item O.
- Credit claim forms for credits reported in Section 11, such as IT-611, IT-604, IT-607, IT-217 or IT-638; submit all credit forms with Form IT-204.
- A statement of no New York source income, with resident-partner details, when you file only because of a resident partner.
- An explanation of the changes, plus the original credit forms, when you file an amended return; an explanation also goes with a final return.
- For federal audit changes: a copy of the federal report of examination changes and a signed statement conceding them, or a signed statement explaining why you do not concede.
- A detailed explanation of any authorized alternate allocation method used in Section 10.
How to fill out IT-204
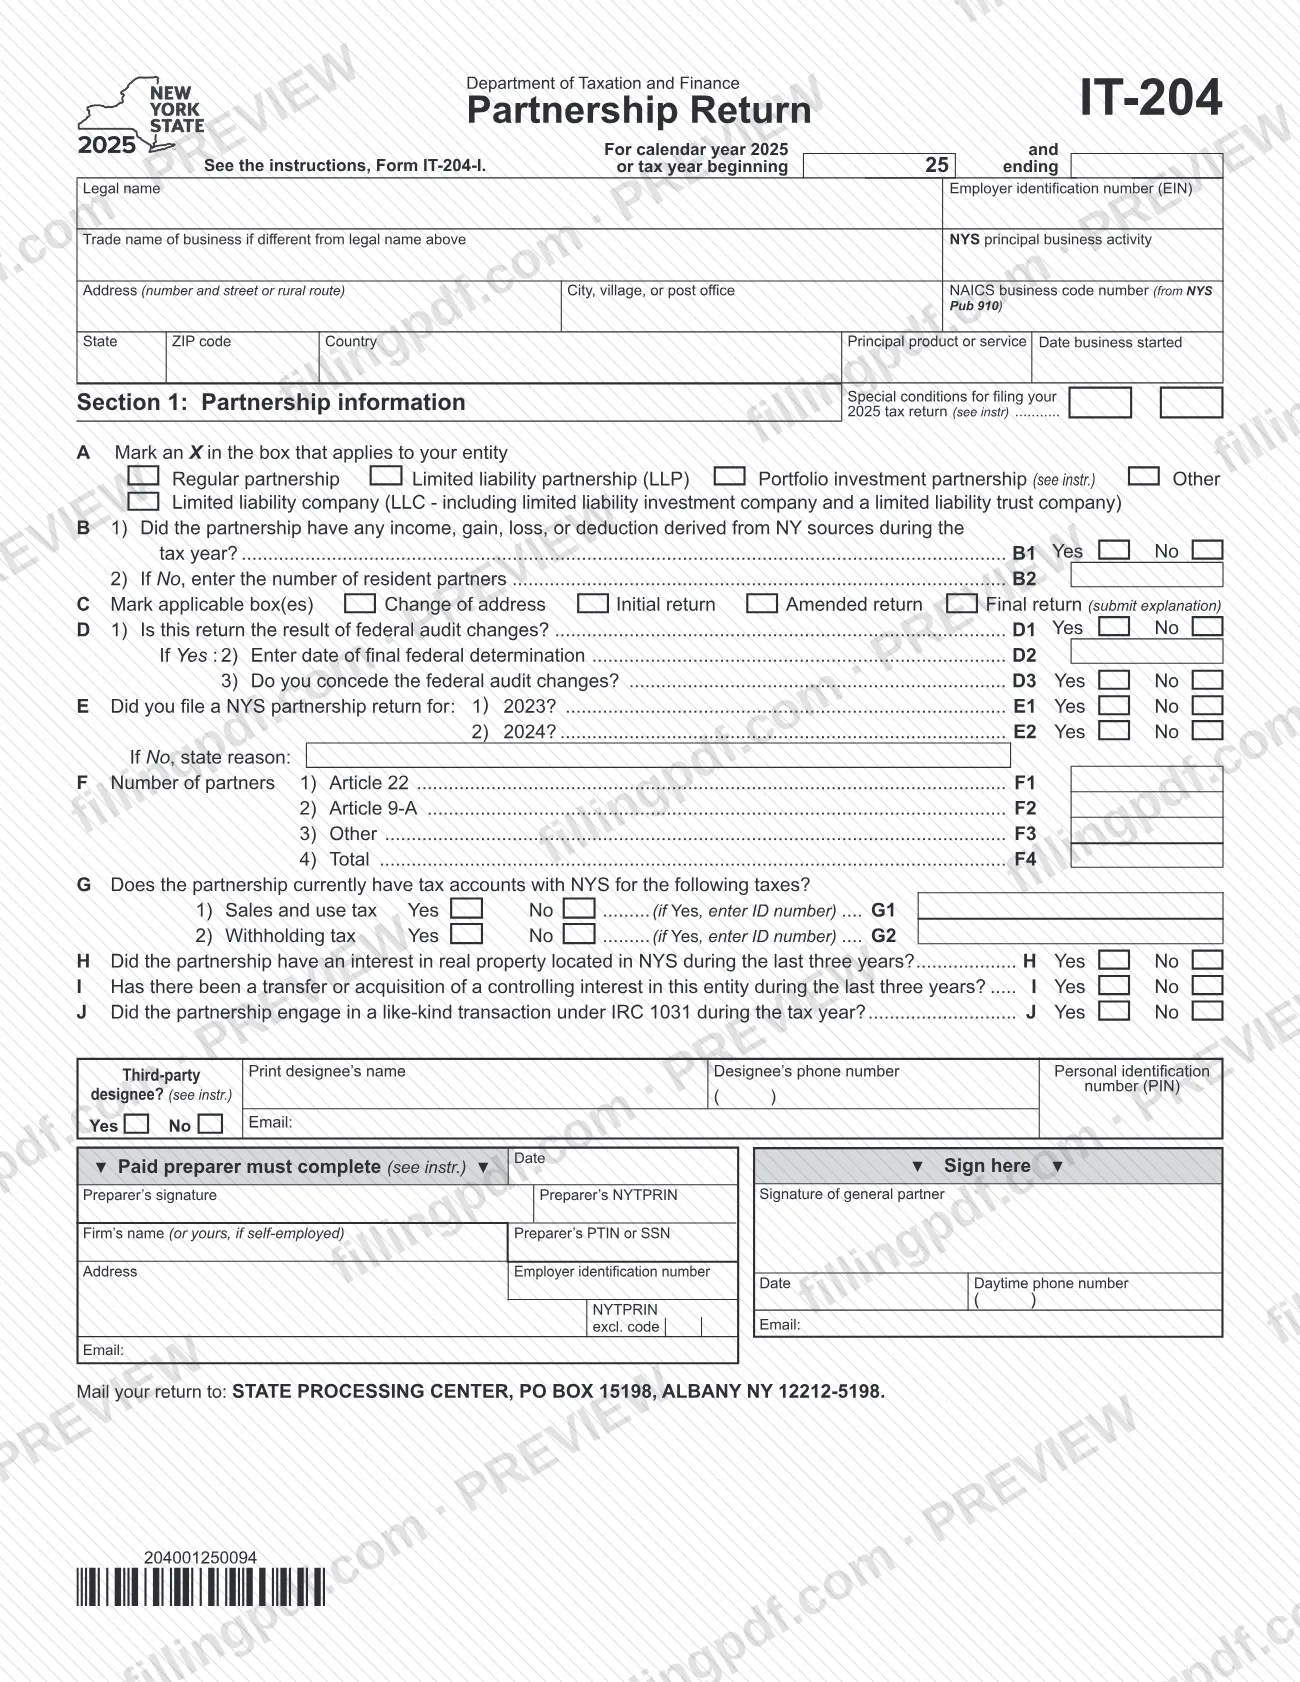
Enter partnership identification at the top
Enter the tax year (the month and day it began and ended if not a calendar year), legal name, trade name if different, address, EIN, NYS principal business activity, six-digit NAICS code, principal product or service and date the business started. If a special condition applies, enter code A6 (Build America Bond interest) or E3 (out of the country) in the special conditions box.
Answer items A through C
At item A mark the entity type; mark Portfolio investment partnership only if you meet the instructions' definition. At B1 say whether the partnership had New York source income, gain, loss or deduction and, if No, enter the number of resident partners at B2. At item C mark change of address, initial, amended or final return.
Complete items D through G
Answer D1 on federal audit changes and, if Yes, give the final determination date (D2) and whether you concede (D3). Answer E1 and E2 on 2023 and 2024 filings, with a reason if No. In F1 to F4 count all partners during the year; partners that are partnerships or LLCs go only in F1. At G1 and G2 enter sales tax and withholding ID numbers if you have those accounts.
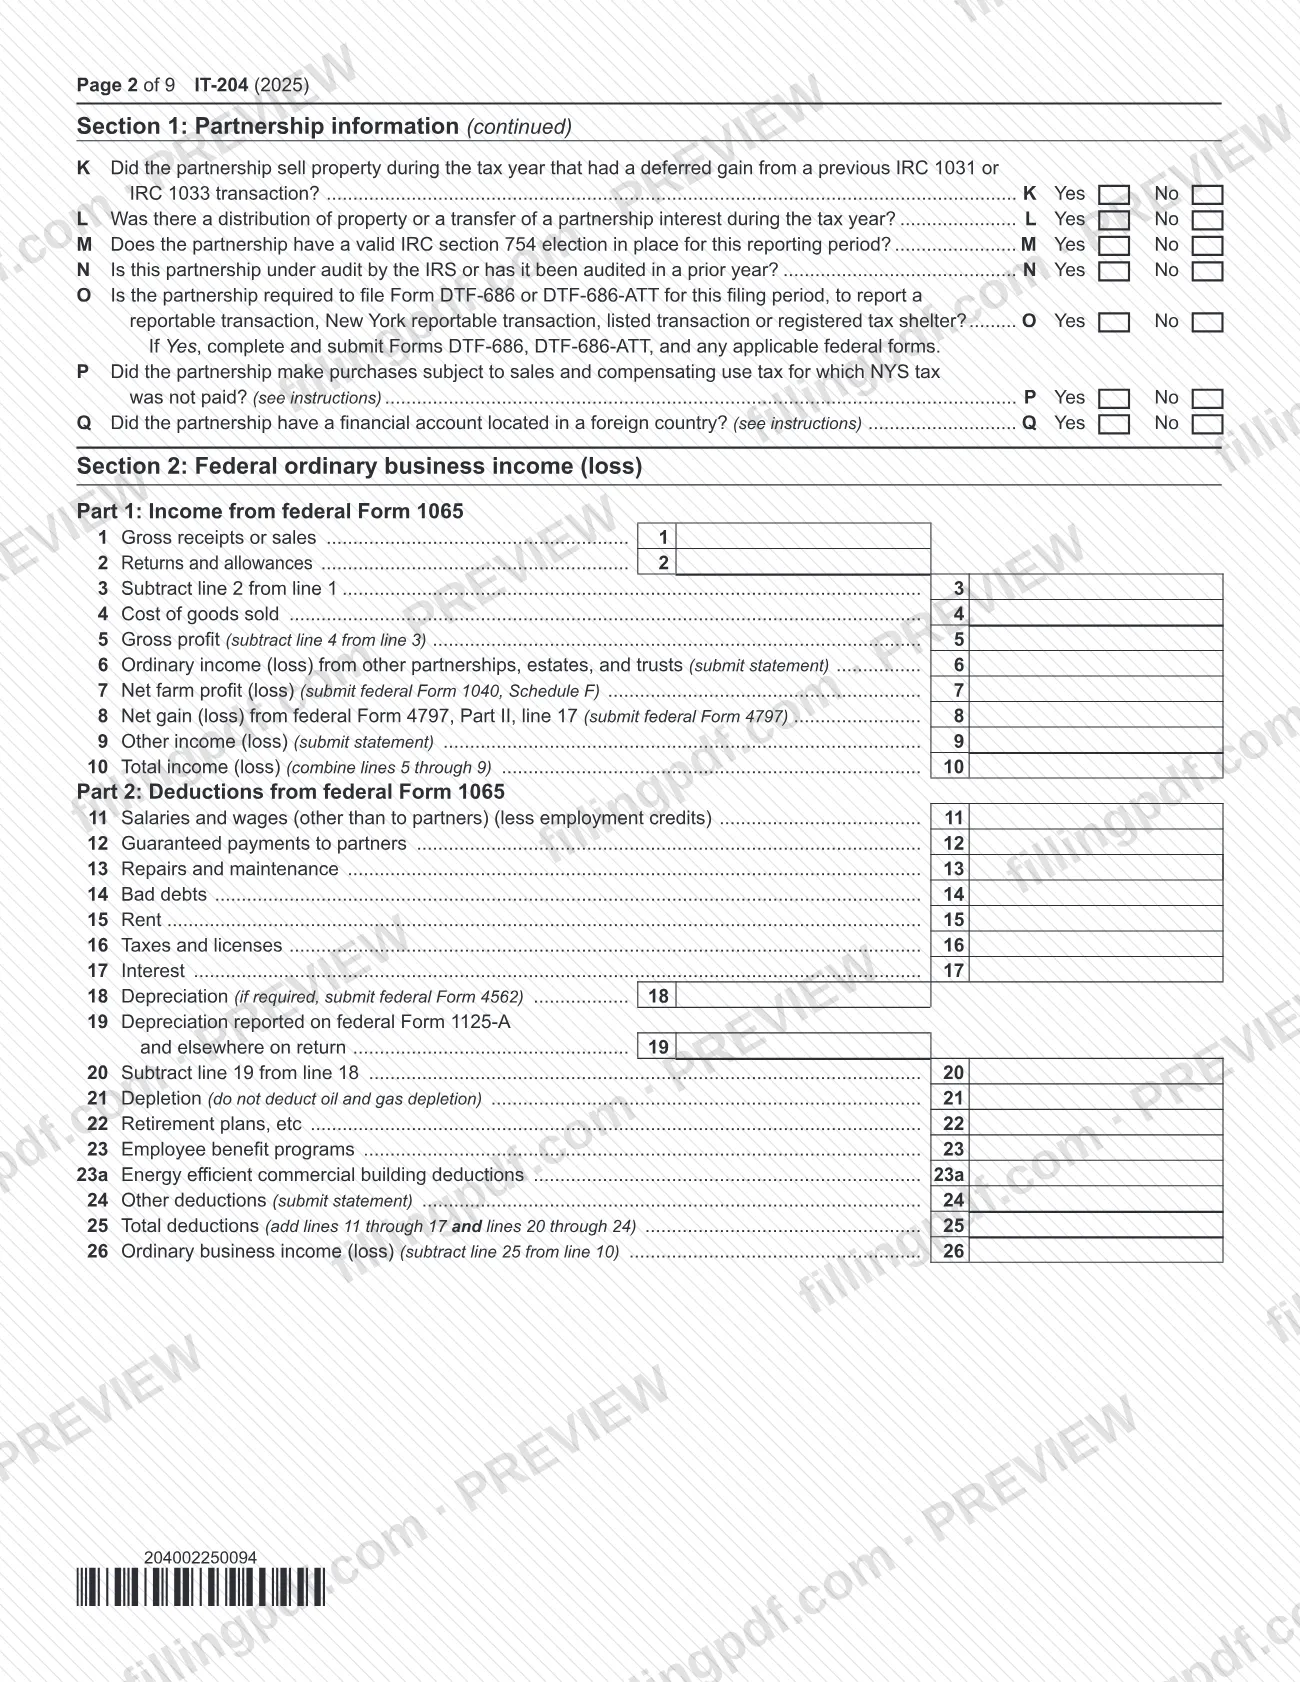
Answer items H through Q
Answer Yes or No to items H through J on page 1 and K through Q on page 2, including the 1031 and 1033 questions, the section 754 election, IRS audits and the foreign financial account at item Q. If you answer Yes to item O, complete and submit Forms DTF-686, DTF-686-ATT and any applicable federal forms.
Complete the designee and signature areas
Mark Yes or No for the third-party designee; a Yes needs the designee's name, phone number, email and a five-digit PIN of their choice. A general partner signs, dates and gives a daytime phone number, and a paid preparer completes the preparer area with an NYTPRIN or exclusion code and a PTIN or SSN.
Transfer Section 2 income and deductions
Copy page 1 of federal Form 1065 to lines 1 through 26 of Section 2: income on lines 1 to 10, deductions on lines 11 to 25 and ordinary business income (loss) on line 26. Attach the statements and federal forms named on lines 6 through 9, 18 and 24.
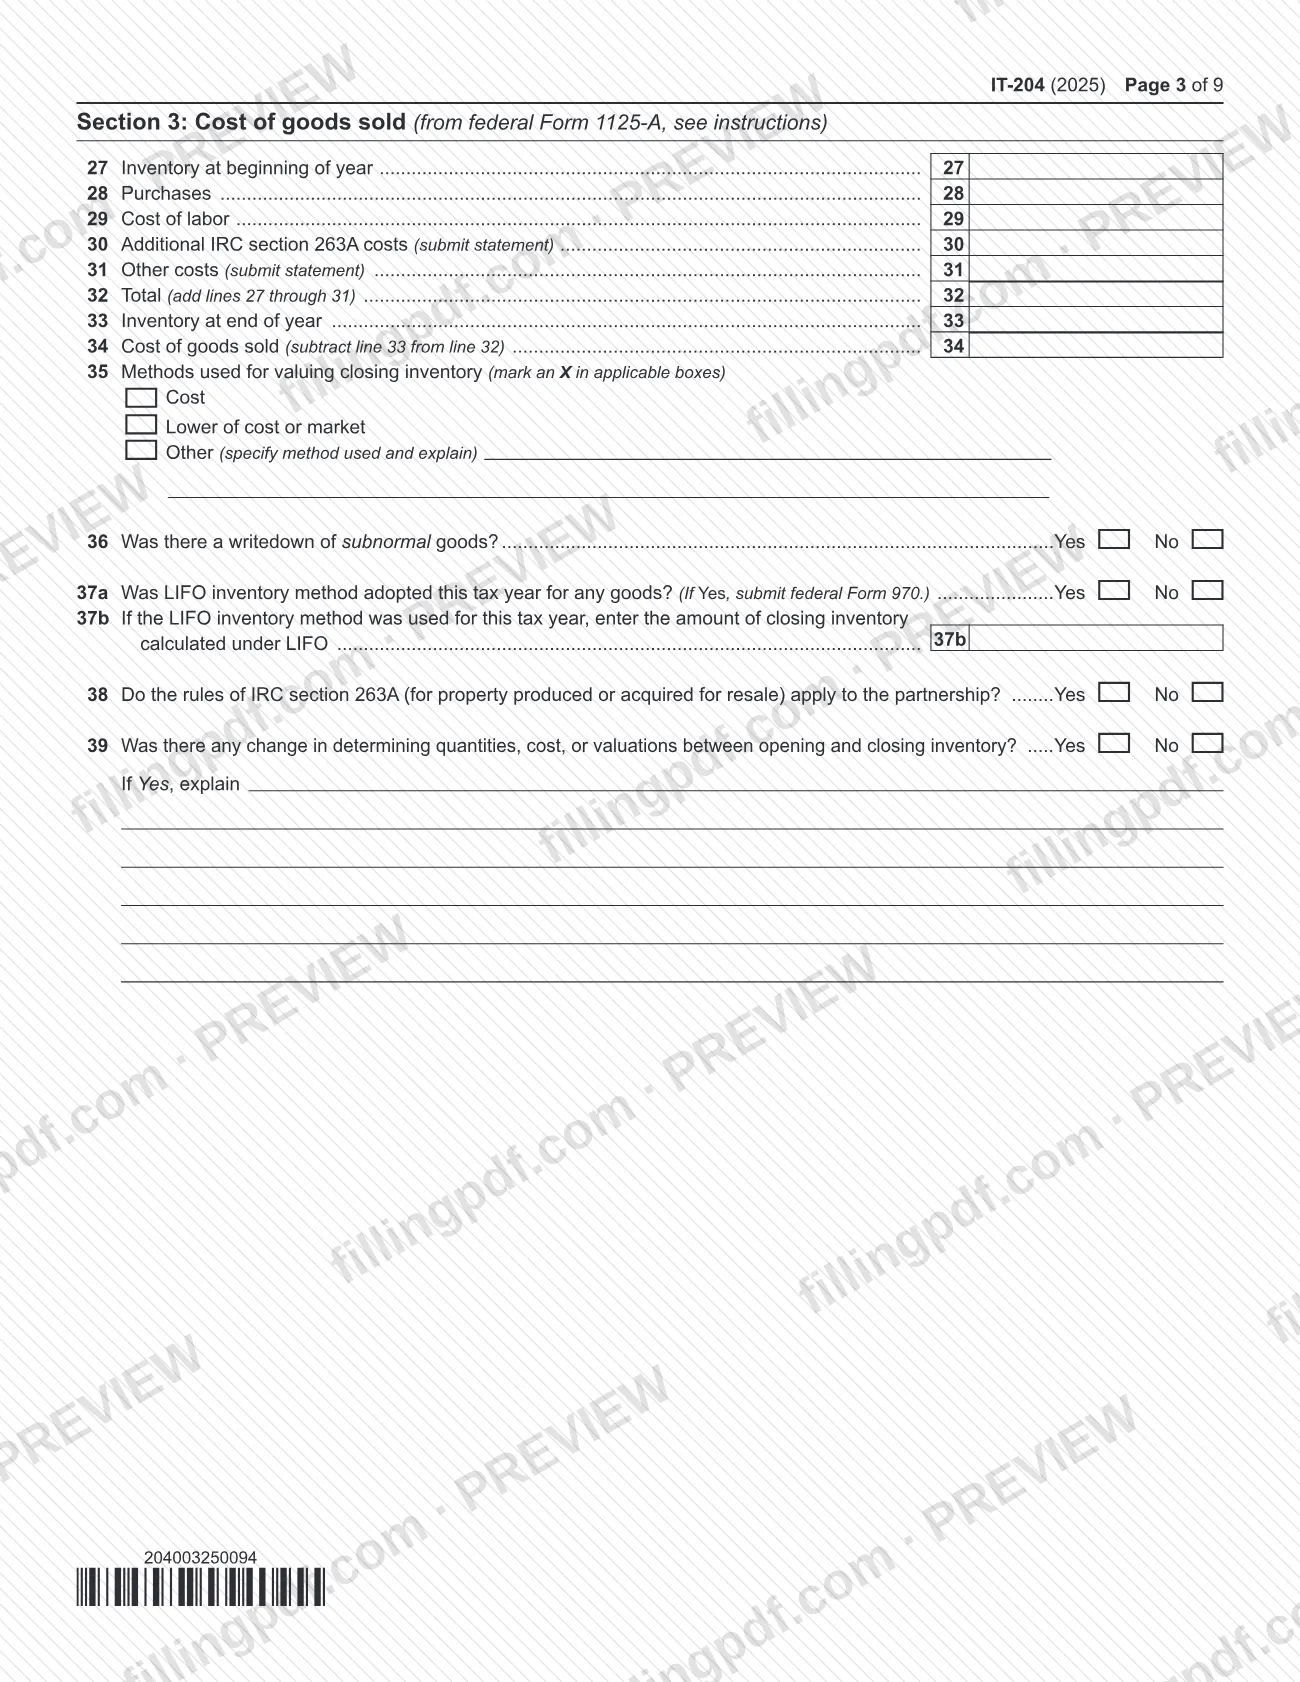
Complete Section 3 cost of goods sold
Transfer federal Form 1125-A to lines 27 through 34. Then mark the inventory valuation method on line 35 and answer lines 36 through 39, giving an explanation if you answer Yes to line 39.
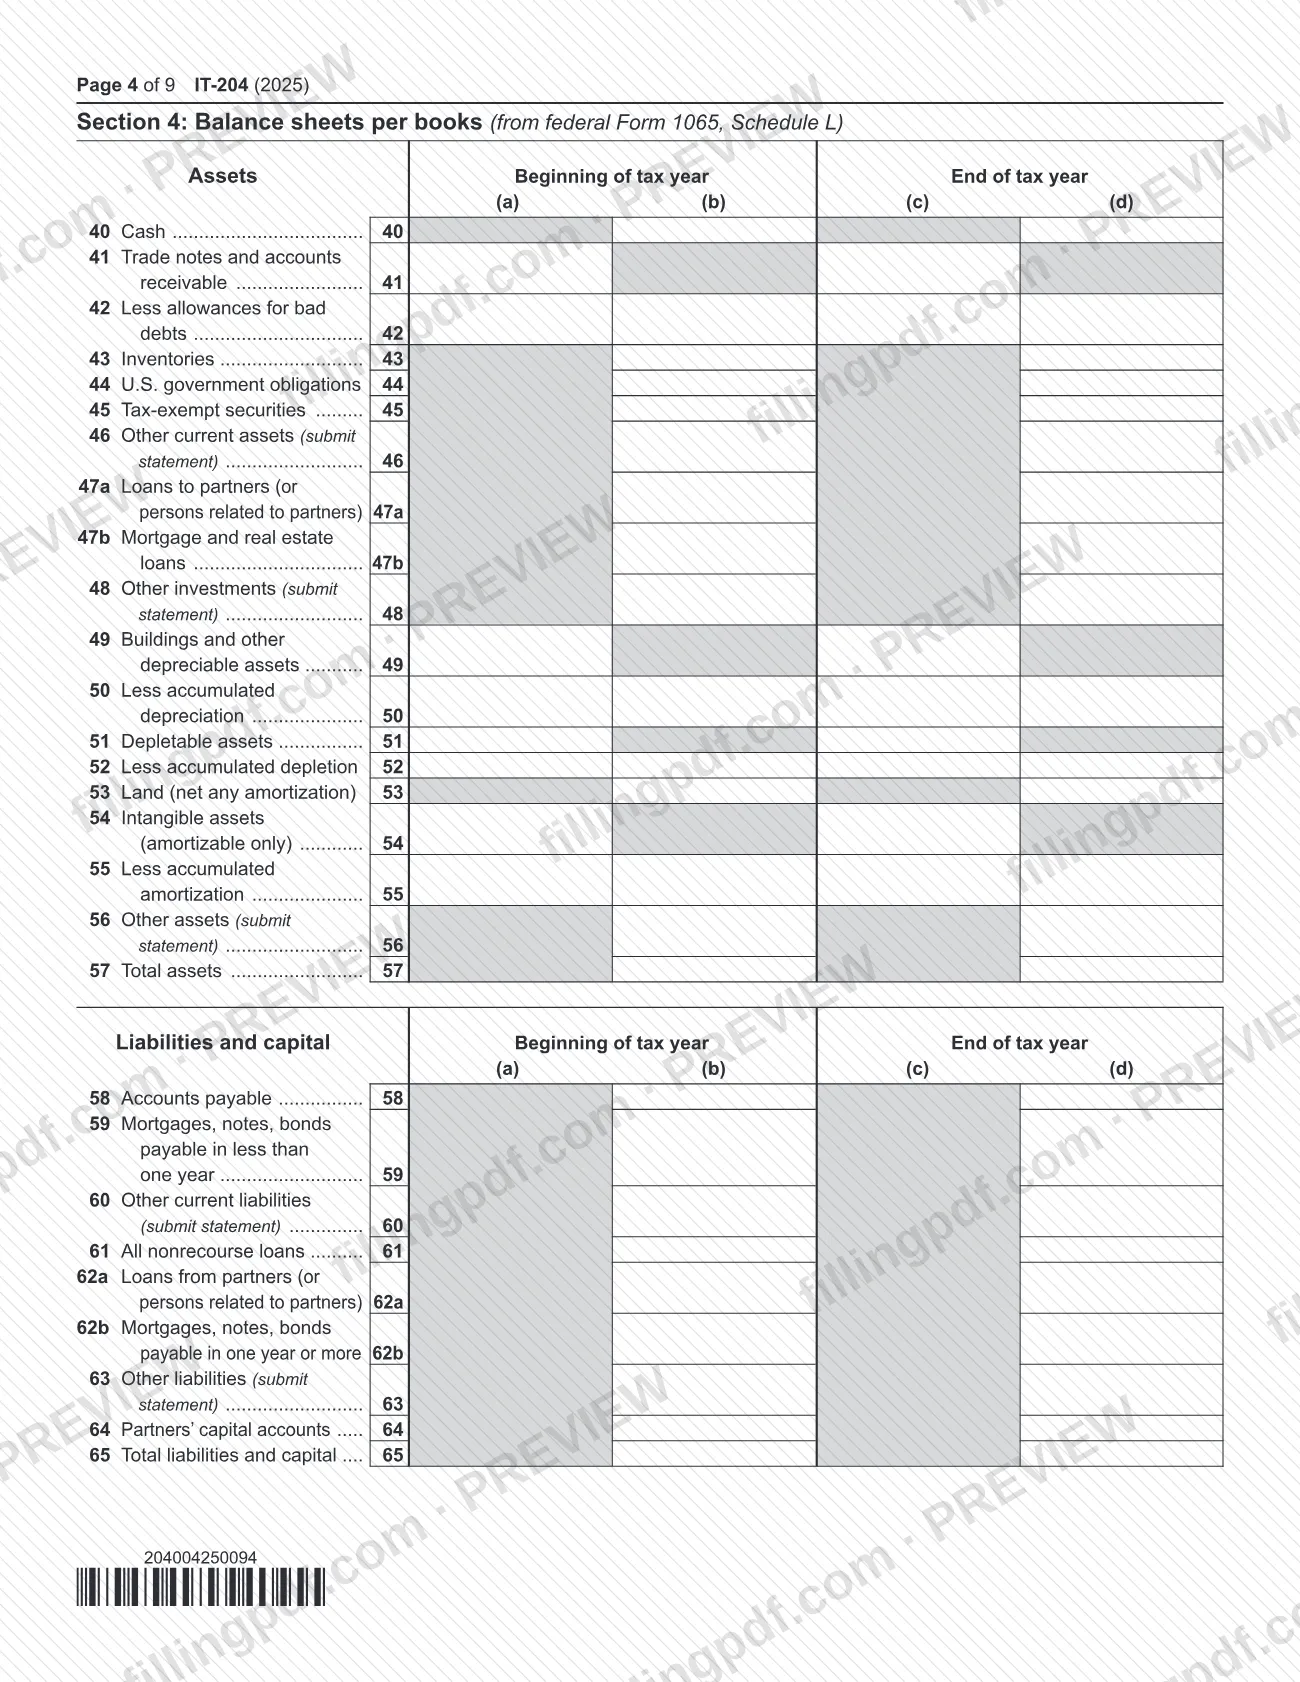
Transfer the Section 4 balance sheets
Copy federal Form 1065, Schedule L, to lines 40 through 65 in columns (a) through (d), for the beginning and end of the tax year. Submit statements where the line says to.
Complete Sections 5 and 6
Copy Schedule M-1 to lines 66 through 74 and Schedule M-2 to lines 75 through 85, writing the types and amounts in the Identify boxes. If you filed federal Schedule M-3, mark the box in Section 5, submit the Schedule M-3 and skip Section 5.
Transfer Section 7 partners' shares
Copy federal Schedule K to lines 86 through 105. Line 97 comes from Schedule K line 11, line 99 from lines 13a through 13e, line 102 from lines 18a through 18c and line 105 from lines 20a through 20c. Enter line 106 and the analysis by type of partner.
Enter New York modifications and other information
Take line 108 from Form IT-225 line 9 and line 110 from IT-225 line 18. Use lines 111 through 114 only for itemized-deduction modifications, with the letter and amount. In Section 9 complete lines 116a through 117c, listing names and EINs at 117c if you answer Yes.
Complete the Section 10 allocation schedule
If the partnership does business both in and out of New York, list each business location in Part 1 and answer line 118. If books and records do not reflect New York income, complete lines 119 through 126 in Part 2 and enter the business allocation percentage on line 126.
Enter Section 11 credit information
Answer the conviction question, then enter flow-through credit bases and information on lines 127 through 144l and credits, addbacks and recaptures on lines 145 through 148, using the 3-digit codes from the instructions. Enter START-UP NY information on lines 149 through 151.
Review, sign and download the PDF
Check that blank inapplicable lines are left empty, that amounts are whole dollars and that required forms and statements are ready. Download or print the completed PDF from FillingPDF, have a general partner sign it and prepare the package for the channels under How to submit.
How to submit IT-204
You can submit Form IT-204 by e-file or by mail.
- E-file: you must e-file if your software allows you to e-file the return, or if you are a tax preparer subject to the e-file mandate. For details, see www.tax.ny.gov (search: mandate).
- Mail: send the return to STATE PROCESSING CENTER, PO BOX 15198, ALBANY NY 12212-5198.
- Private delivery services: see Publication 55, Designated Private Delivery Services.
Include the partner and supporting forms the instructions require with the return: Form IT-204-IP for the partners described in the instructions, Form IT-204.1 where it applies, the credit claim forms behind lines 127 to 151, and the federal forms and statements named on the lines you complete. The Tax Department can request Forms IT-204-IP for nonresident partners during an audit. Give each partner their IT-204-IP or IT-204-CP on or before the due date of the partnership return.
Form IT-204-LL, the filing fee payment form, is separate and applies only to certain LLCs, LLPs and regular partnerships; see Form IT-204-LL-I for the amount and how to pay. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Using colored ink, dollar signs, commas or decimal points; the instructions require black ink, whole dollars and no punctuation in amounts.
- Showing a loss in brackets or parentheses instead of placing a minus sign immediately to the left of the amount.
- Using a check mark in a box instead of an X, or letting Xs and numerals touch the box lines.
- Completing Section 10 when the partnership files only because of a New York resident partner and has no New York source income.
- Counting partners that are partnerships or LLCs in item F2 instead of only in F1, the Article 22 count.
- Completing line 116a when the only reason for filing is a resident partner.
- Completing Section 5 after filing federal Schedule M-3 instead of marking the box and attaching the Schedule M-3.
- Leaving the paid preparer area incomplete: the preparer must give an NYTPRIN or an exclusion code, and a PTIN or Social Security number.
- Missing the 90-day deadline to file an amended return after an amended federal return or a final federal determination.
- Using the IT-204 instructions to prepare the New York City unincorporated business tax return, which is a separate form (NYC-204).
Frequently asked questions
What is IT-204 used for?
IT-204 is the New York State Partnership Return. A partnership uses it to report income, deductions, gains, losses and credits from operating the partnership for calendar year 2025 or another tax year beginning in 2025. Partnerships are not subject to personal income tax, so the return supports the partners' own New York returns.
Who has to file Form IT-204?
A partnership must file if it has at least one partner who is an individual, estate or trust resident in New York State, or any income, gain, loss or deduction from New York sources, regardless of the amount of income. A partner that is a New York-formed partnership or corporation does not, by itself, trigger the requirement.
When is the IT-204 due for 2025?
Calendar year 2025 returns are due on or before March 16, 2026. Fiscal-year returns are due on the 15th day of the third month after the tax year ends. You can request an automatic extension of time to file by the due date through the Tax Department's website.
Where do I mail Form IT-204?
Mail it to STATE PROCESSING CENTER, PO BOX 15198, ALBANY NY 12212-5198. You must e-file instead if your software allows it or you are a tax preparer subject to the e-file mandate. Private delivery services are covered in Publication 55.
What forms must go with the IT-204?
It depends on your partners. Individuals, estates and trusts get Form IT-204-IP; partners that are partnerships or LLCs get IT-204-IP and IT-204-CP; corporate partners taxable under Article 9-A need IT-204-CP. Form IT-204.1 is required when a corporate partner or a partnership or LLC partner exists. Add credit forms and any forms the lines name.
How do I amend an IT-204 or correct a partner schedule?
Mark the Amended return box at item C on a blank IT-204, complete the entire form with corrected lines, and submit an explanation and the credit forms you used. File within 90 days of a federal amended return or final federal determination. Amended IT-204-IP or IT-204-CP forms are marked Amended K-1.
Does IT-204 cover the New York City unincorporated business tax?
No. The IT-204 instructions apply to the New York State partnership return only. The New York City unincorporated business tax is administered by the New York City Department of Finance and uses Form NYC-204.
Can I fill out Form IT-204 online?
Yes. You can fill out the IT-204 PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the return; you e-file or mail it through the Tax Department's channels.
What is the penalty for filing IT-204 late?
The Tax Department imposes a penalty for each month or fraction of a month, up to five months, if the return is late, incomplete, or an amended return is not filed within 90 days. It is based on the number of partners subject to Article 22 tax, unless reasonable cause applies.
Ready to fill out IT-204?
Fill out IT-204 now