
ST-120 is the New York State and Local Sales and Use Tax Resale Certificate, a sales tax exemption certificate issued by the New York State Department of Taxation and Finance. A purchaser completes it and gives it to the seller when buying tangible personal property or services that will be resold. It covers registered New York vendors in Part 1 and purchasers who are not New York vendors in Part 2. On this page you can fill out the form online on FillingPDF and download or print the completed PDF; the form and its instructions are published by the Tax Department at tax.ny.gov.
Last updated
What is ST-120?
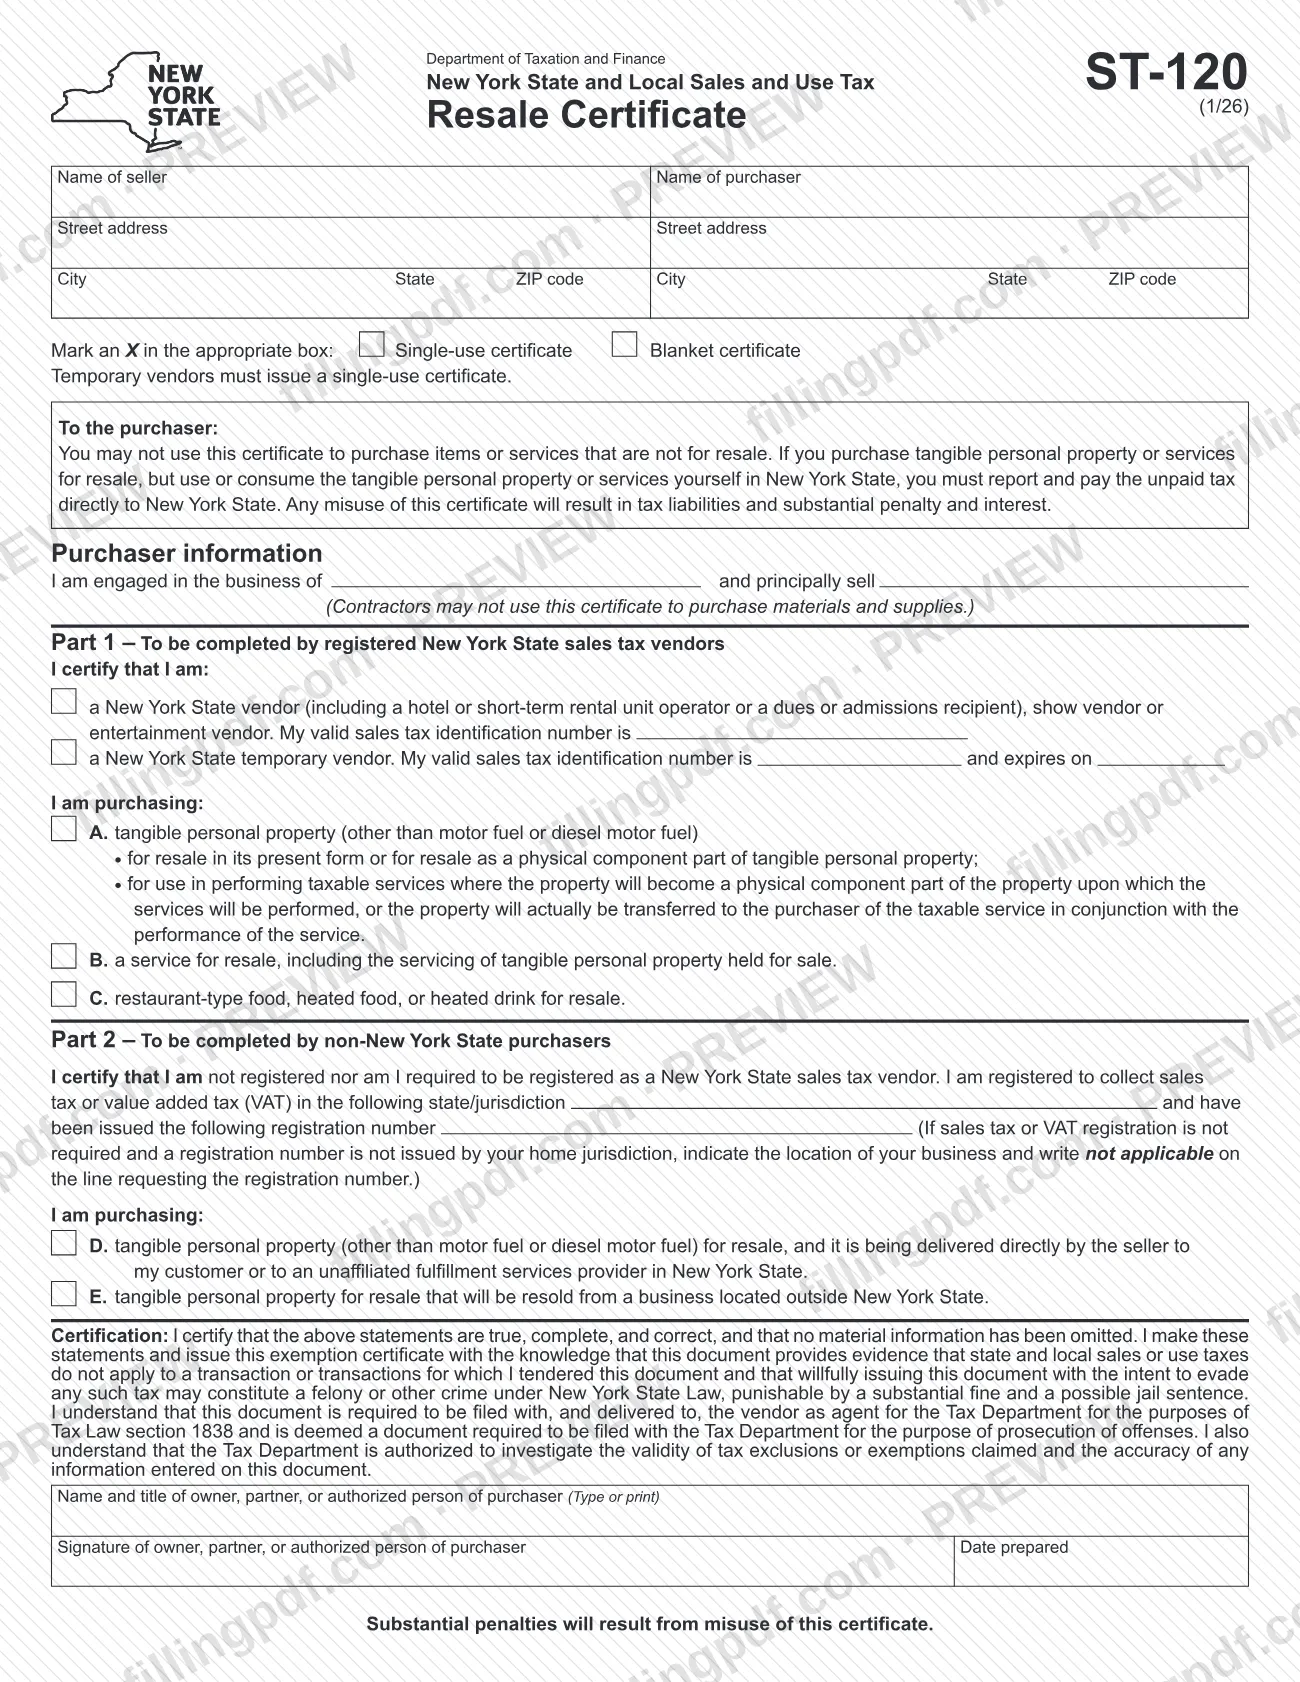
Form ST-120, Resale Certificate, is the New York State Department of Taxation and Finance exemption certificate that a purchaser gives to a seller to document that tangible personal property or services are being bought for resale, so sales tax is not collected on that purchase.
The certificate is headed "New York State and Local Sales and Use Tax" and has two parts. Part 1 is completed by registered New York State sales tax vendors, including hotel or short-term rental unit operators, dues or admissions recipients, show vendors, entertainment vendors and temporary vendors. Part 2 is completed by purchasers who are not registered, and not required to be registered, as New York State sales tax vendors.
The purchaser marks one of five purchase categories: A (tangible personal property for resale or as a component part, or for use in taxable services), B (a service for resale), C (restaurant-type or heated food or drink for resale), D (property delivered directly by the seller to the purchaser's customer or to an unaffiliated fulfillment services provider in New York State) or E (property resold from a business located outside New York State).
The certificate is delivered to the seller, who acts as agent for the Tax Department. It cannot be used to buy items that are not for resale, to buy motor fuel or diesel motor fuel, or to avoid prepaid sales tax on cigarettes. Contractors cannot use it; the instructions point them to Form ST-120.1, Contractor Exempt Purchase Certificate, or Form AU-297, Direct Payment Permit.
Who needs to file ST-120?
Purchasers who buy items or services for resale use Form ST-120. The instructions describe two groups:
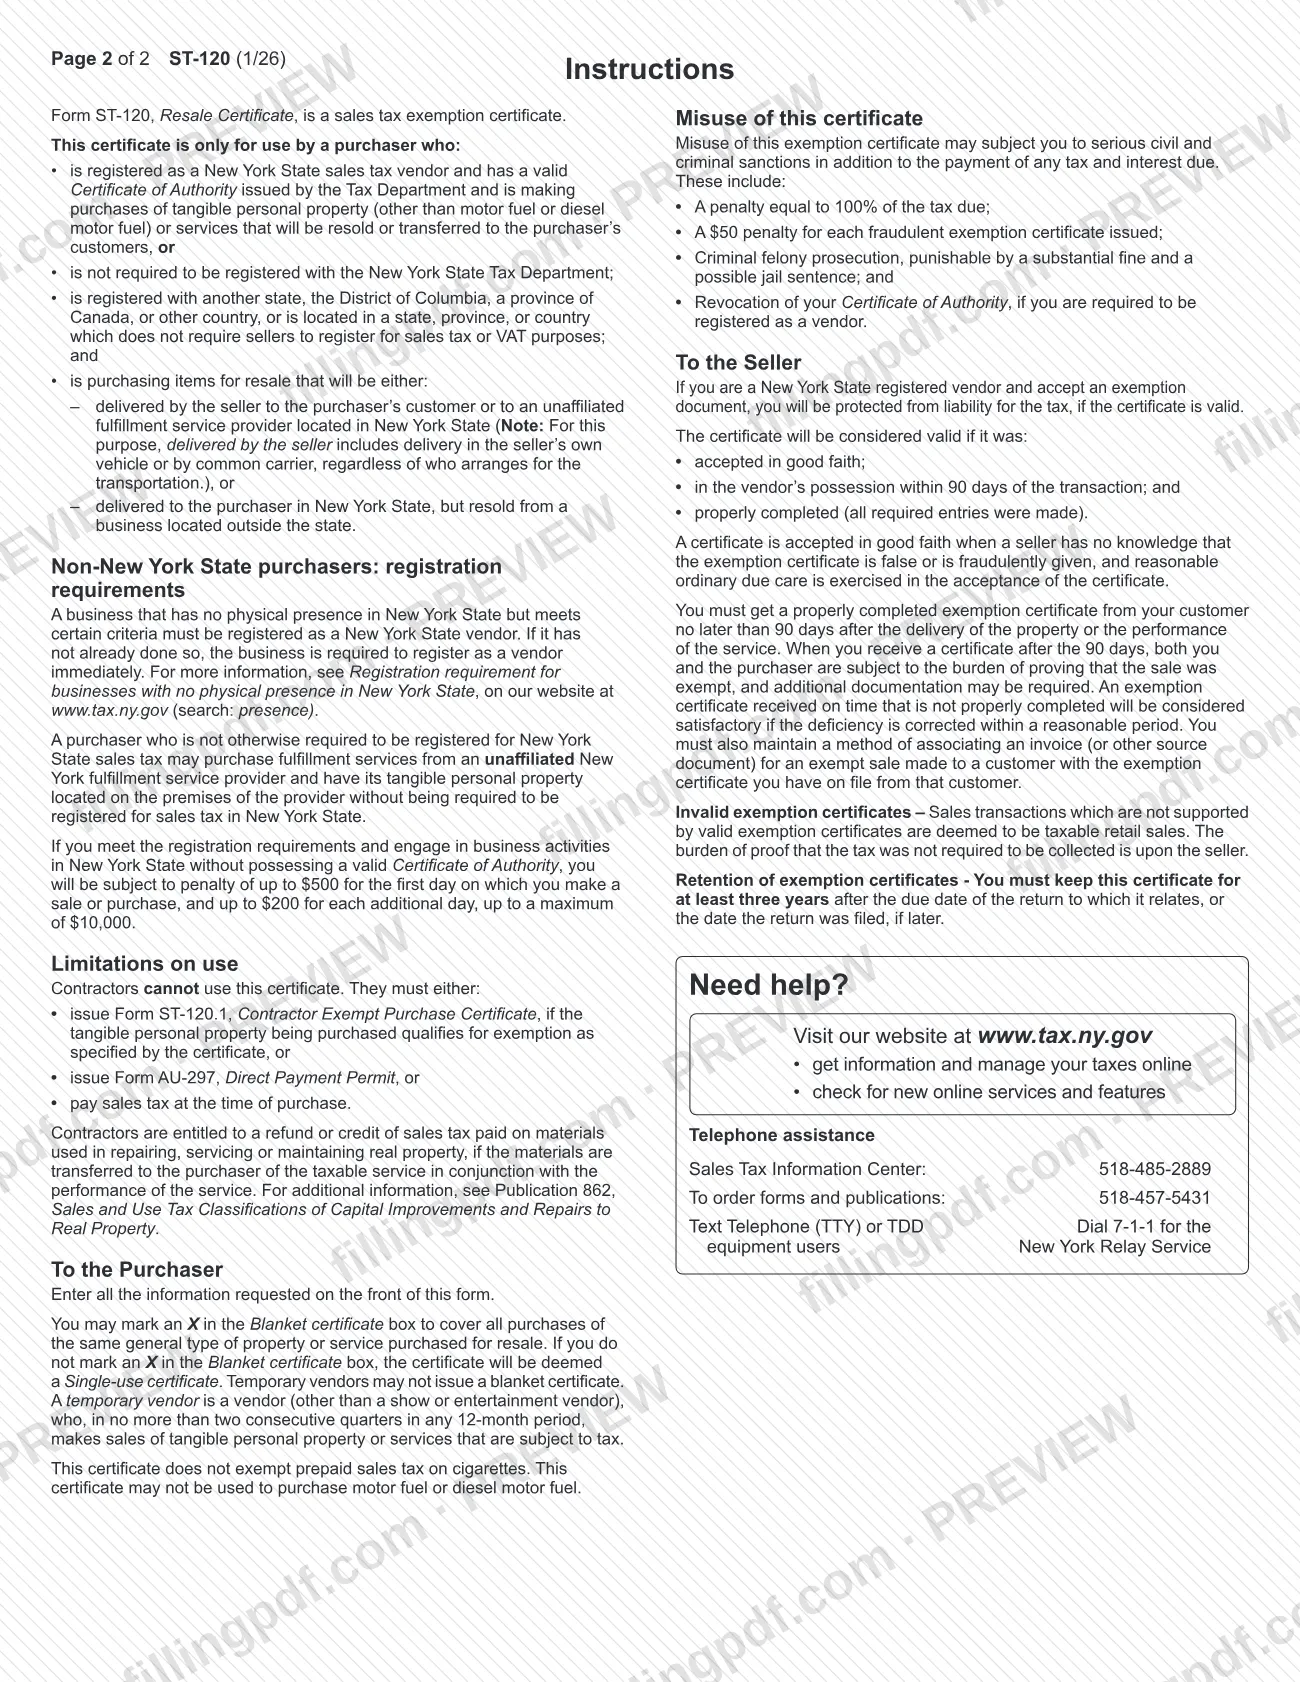
- Registered New York State sales tax vendors with a valid Certificate of Authority issued by the Tax Department, buying tangible personal property (other than motor fuel or diesel motor fuel) or services that will be resold or transferred to their customers. They complete Part 1.
- Purchasers not required to be registered in New York, such as businesses registered with another state, the District of Columbia, a province of Canada or another country, or located where sellers are not required to register for sales tax or VAT. Their purchase must be delivered by the seller to the purchaser's customer or to an unaffiliated fulfillment service provider in New York State, or delivered in New York State but resold from a business located outside the state. They complete Part 2.
Temporary vendors must issue a single-use certificate. A temporary vendor is a vendor, other than a show or entertainment vendor, who makes taxable sales in no more than two consecutive quarters in any 12-month period.
Do not use this form if you are a contractor buying materials and supplies, or if the purchase is not for resale. The owner, partner or authorized person of the purchaser signs.
Sellers who accept the certificate do not complete it; they keep it on file.
When to file ST-120
Complete Form ST-120 when you buy items or services for resale and the seller needs an exemption document for that purchase. The seller must get a properly completed certificate no later than 90 days after delivery of the property or performance of the service. A certificate received after the 90 days leaves both seller and purchaser with the burden of proving the sale was exempt, and additional documentation may be required.
A single-use certificate covers one purchase. A blanket certificate covers all purchases of the same general type of property or service bought for resale; if you do not mark the Blanket certificate box, the certificate is treated as single-use. Temporary vendors may not issue a blanket certificate.
The seller must keep the certificate for at least three years after the due date of the return to which it relates, or the date the return was filed, if later. The form prints no expiration date for the certificate itself, other than the expiration date of a temporary vendor's sales tax identification number.
How to fill out ST-120
Enter seller and purchaser details
At the top, enter the name and street address, city, state and ZIP code of the seller and of the purchaser.
Mark the certificate type
Mark an X in the Single-use certificate or Blanket certificate box. A temporary vendor must mark Single-use; an unmarked certificate is treated as single-use.
Describe your business
Under Purchaser information, complete "I am engaged in the business of and principally sell". Contractors may not use this certificate to purchase materials and supplies.
Complete Part 1 if you are a vendor
Registered New York State vendors check the vendor box (or the temporary vendor box) and enter their valid sales tax identification number. A temporary vendor also enters the date it expires.
Choose purchase A, B or C
In Part 1, check A for tangible personal property for resale or for use in taxable services, B for a service for resale, or C for restaurant-type food, heated food or heated drink for resale.
Complete Part 2 if not a New York vendor
Non-New York State purchasers enter the state or jurisdiction where they are registered to collect sales tax or VAT and the registration number. If none is issued, indicate the business location and write not applicable on the registration number line.
Choose purchase D or E
In Part 2, check D if the property is delivered by the seller directly to your customer or to an unaffiliated fulfillment services provider in New York State, or E if it will be resold from a business located outside New York State.
Enter name and title
In the Certification block, type or print the name and title of the owner, partner or authorized person of the purchaser.
Sign and date the certificate
The owner, partner or authorized person signs and enters the date prepared. By signing you certify the statements are true, complete and correct.
Review and download the completed PDF
Check that only the part that applies to you is completed and that the IDs and category match your purchase. Download or print the completed PDF from FillingPDF and give it to the seller as described under How to submit.
How to submit ST-120
Form ST-120 is delivered to the seller, not mailed to the Tax Department. The certificate states that it is required to be filed with, and delivered to, the vendor as agent for the Tax Department.
- To the seller: give the completed and signed certificate to the seller from whom you are buying for resale, no later than 90 days after delivery of the property or performance of the service.
- Seller's records: the seller keeps the certificate for at least three years after the due date of the related return, or the filing date if later, and must keep a way to match each exempt invoice or source document with the certificate on file for that customer.
- Questions: the Tax Department lists its website at www.tax.ny.gov, the Sales Tax Information Center at 518-485-2889, and 518-457-5431 to order forms and publications. TTY or TDD users dial 7-1-1 for the New York Relay Service.
FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Using the certificate to buy items or services that are not for resale; the form warns that misuse results in tax liabilities and substantial penalty and interest.
- Buying and then using or consuming the property or services yourself in New York State without reporting and paying the unpaid tax directly to New York State.
- Contractors using Form ST-120 to buy materials and supplies; they must use Form ST-120.1 or Form AU-297, or pay sales tax at purchase.
- A temporary vendor marking the Blanket certificate box; temporary vendors must issue a single-use certificate.
- Using the certificate to buy motor fuel or diesel motor fuel, or expecting it to exempt prepaid sales tax on cigarettes.
- Completing both Part 1 and Part 2; Part 1 is for registered New York State sales tax vendors and Part 2 is for non-New York State purchasers.
- Leaving the sales tax identification number blank in Part 1, or omitting the expiration date for a temporary vendor.
- Sending the certificate to the seller more than 90 days after delivery, which shifts the burden of proving the sale was exempt to seller and purchaser.
Frequently asked questions
What is Form ST-120 used for?
Form ST-120 is the New York State resale certificate. A purchaser gives it to a seller to document that tangible personal property or services are being bought for resale, so the seller does not collect sales tax on that purchase. It is a sales tax exemption certificate issued by the Tax Department.
Who can use the ST-120 resale certificate?
Registered New York State sales tax vendors with a valid Certificate of Authority, and non-New York purchasers who are not required to register, can use it for items bought for resale. Contractors cannot use it for materials and supplies; they use Form ST-120.1, Form AU-297, or pay tax at purchase.
What is the difference between a single-use and a blanket ST-120?
A single-use certificate covers one purchase, while a blanket certificate covers all purchases of the same general type of property or service bought for resale. If you do not mark the Blanket box, the certificate is deemed single-use. Temporary vendors may not issue a blanket certificate.
Do I send Form ST-120 to the Tax Department?
No. You deliver the completed certificate to the seller, who holds it as agent for the Tax Department. The seller must keep it for at least three years after the due date of the related return, or the date the return was filed, if later.
How long does the seller have to get the resale certificate?
The seller must have a properly completed certificate no later than 90 days after delivery of the property or performance of the service. If it arrives later, seller and purchaser must prove the sale was exempt, and additional documentation may be required.
Which part of ST-120 do I complete: Part 1 or Part 2?
Complete Part 1 if you are a registered New York State sales tax vendor, including a temporary vendor. Complete Part 2 if you are not registered and not required to be registered in New York, and give your home state or jurisdiction registration information.
What happens if I misuse the ST-120?
Misuse can bring serious civil and criminal sanctions in addition to the tax and interest due, including penalties, felony prosecution and, for vendors required to be registered, revocation of the Certificate of Authority. Ask the Tax Department for the current penalty amounts.
Can I fill out Form ST-120 online?
Yes. You can fill out the ST-120 PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not send the certificate to anyone; you deliver it to the seller yourself.
Ready to fill out ST-120?
Fill out ST-120 now