
ST-121 is the New York State Department of Taxation and Finance's exempt use certificate, which a purchaser with a valid Certificate of Authority gives to a seller to buy, rent or lease qualifying property or services without state and local sales and use tax. It covers production, exempt services and a list of other exemptions, and it can be used for one purchase or as a blanket certificate. On FillingPDF you can fill out the form online and download or print the completed PDF; the original form and its instructions are published by the Tax Department.
Last updated
What is ST-121?
Form ST-121, New York State and Local Sales and Use Tax Exempt Use Certificate, is the certificate a purchaser gives a seller to buy, rent or lease qualifying property or services exempt from state and local sales and use taxes.
The New York State Department of Taxation and Finance (Tax Department) issues the form. By signing the certification on page 2, the purchaser states that the purchase is exempt because the property or services will be used for the exempt purpose marked on the form, as explained in the instructions on pages 3 and 4. The seller keeps the certificate as evidence of why no tax was collected.
The exemptions are grouped in three parts:
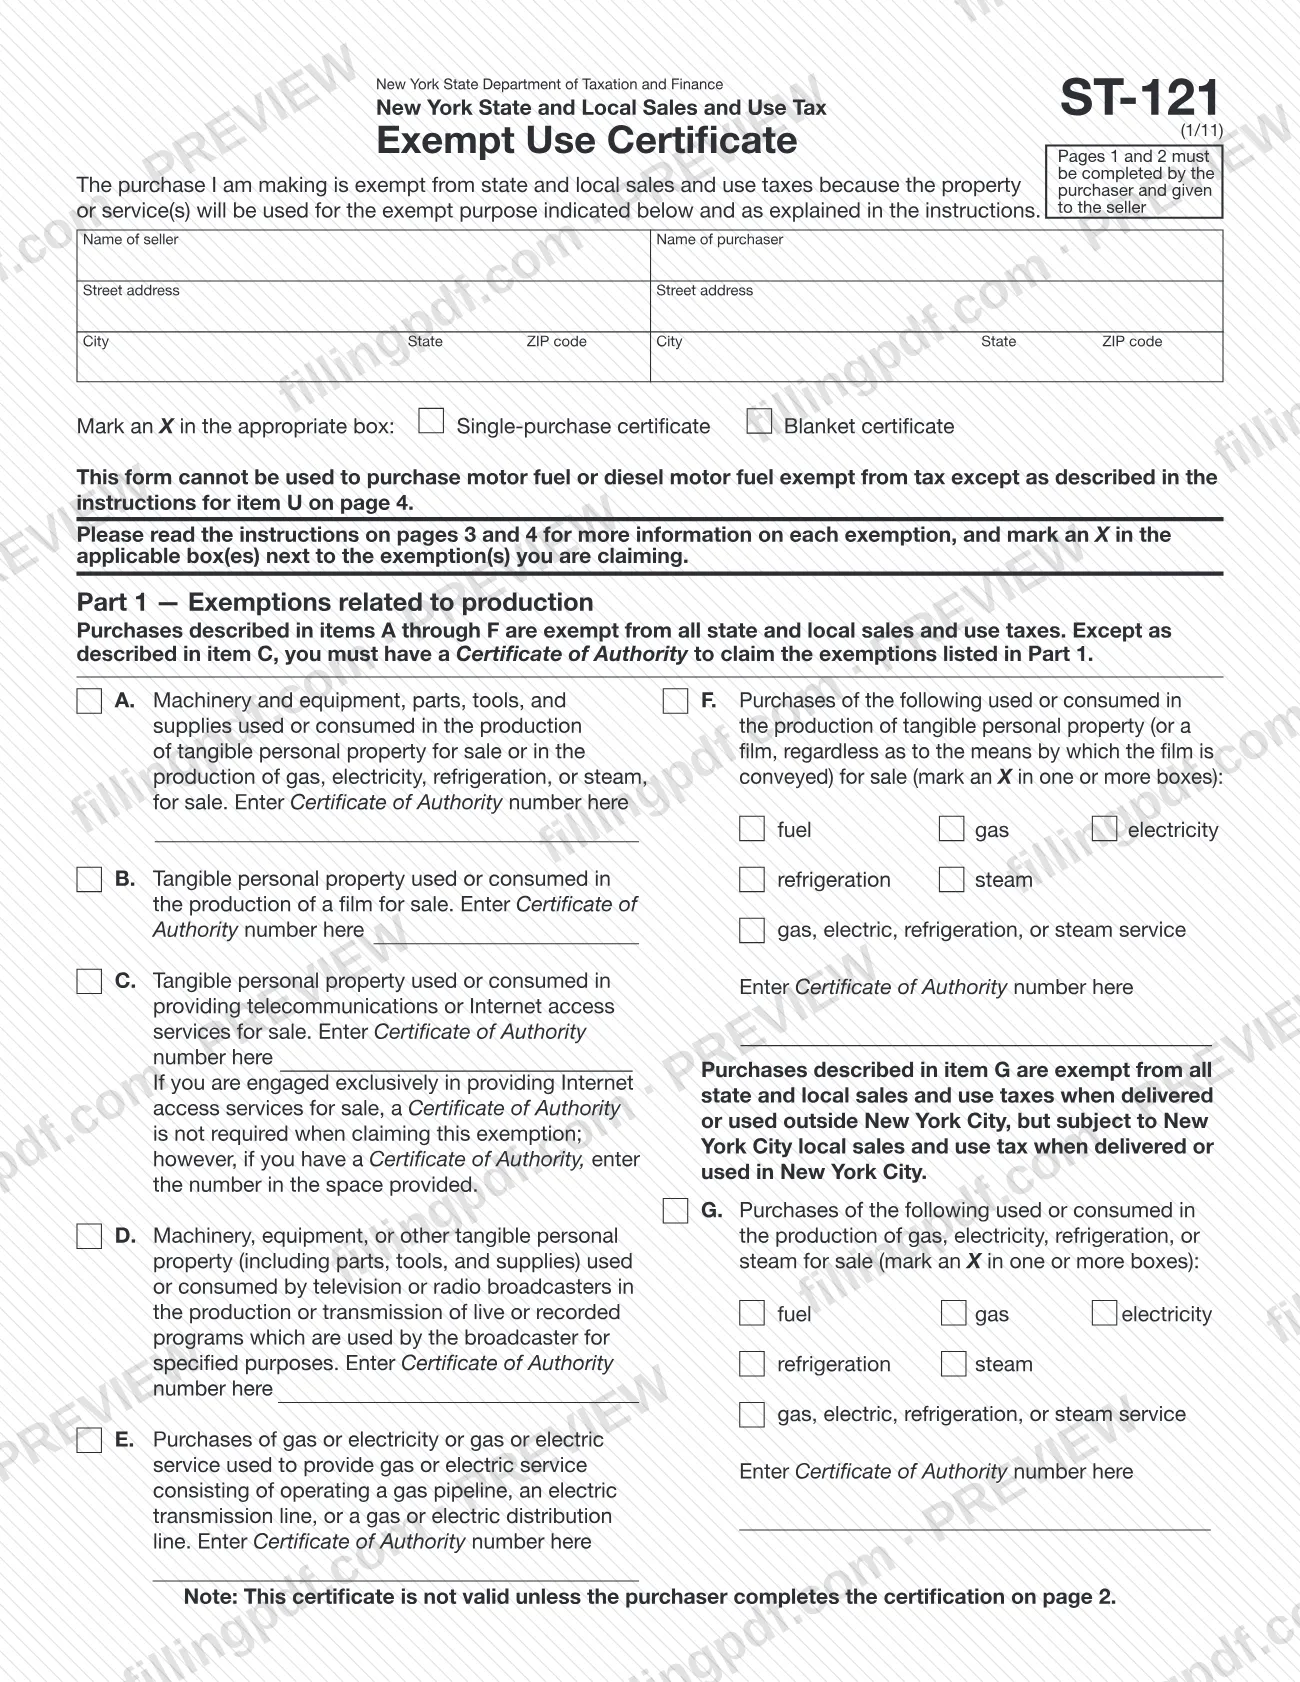
- Part 1, items A through G: exemptions related to production, such as machinery and equipment used in producing tangible personal property for sale, film production, telecommunications and Internet access services, broadcasting, and fuel and utilities.
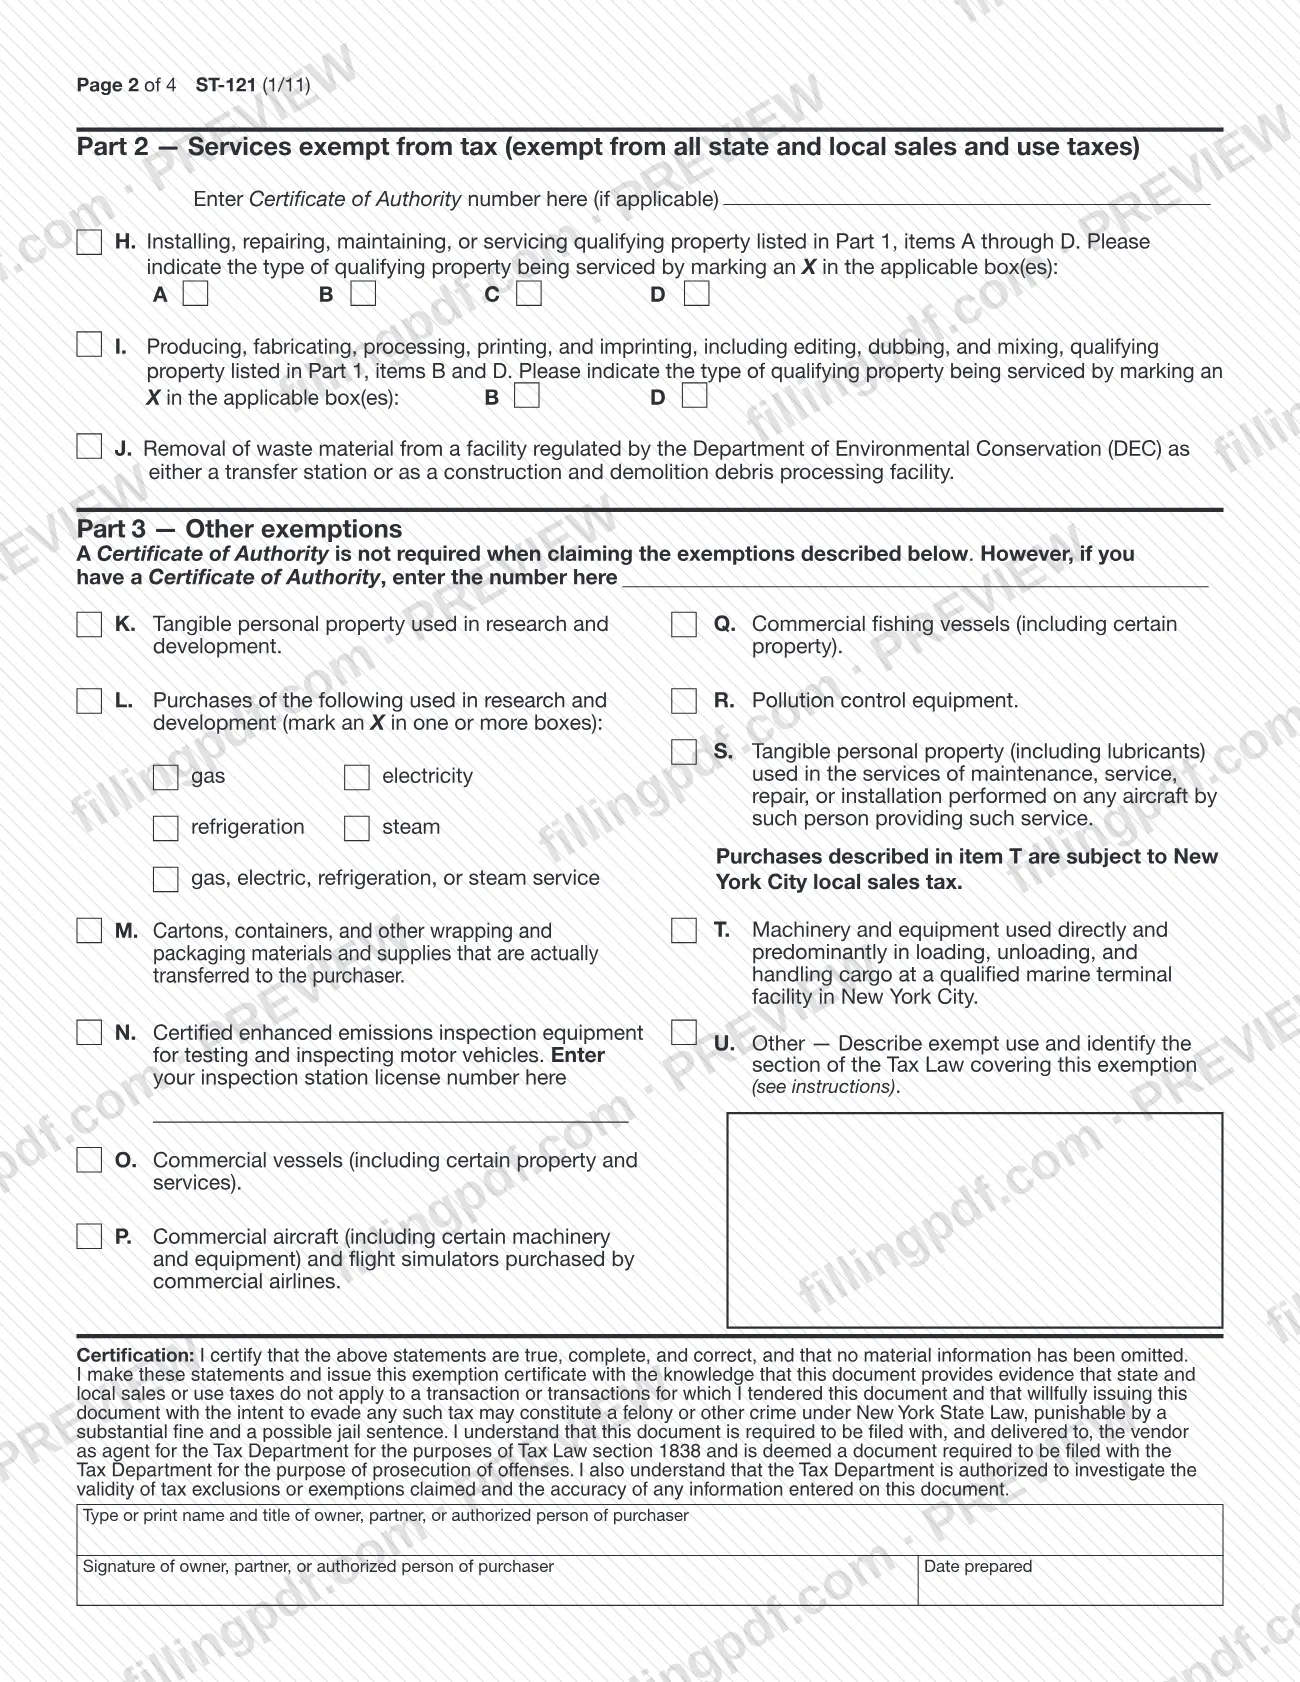
- Part 2, items H through J: exempt services, such as installing or repairing qualifying Part 1 property and removing waste from certain facilities regulated by the Department of Environmental Conservation (DEC).
- Part 3, items K through U: other exemptions, including research and development, packaging materials, commercial vessels and aircraft, pollution control equipment and an open "Other" line, item U.
Items G and T stay subject to New York City local tax. You mark either Single-purchase certificate or Blanket certificate. The form cannot be used to buy exempt motor fuel or diesel motor fuel except as described for item U. For the production exemptions, the Tax Department points to Publication 852.
Who needs to file ST-121?
The main users are purchasers who hold a valid Certificate of Authority and are buying, renting or leasing property or services that fit one of the exemptions listed on the form. The purchaser completes pages 1 and 2 and gives the form to the seller; the seller keeps it.
Conditions the instructions attach:
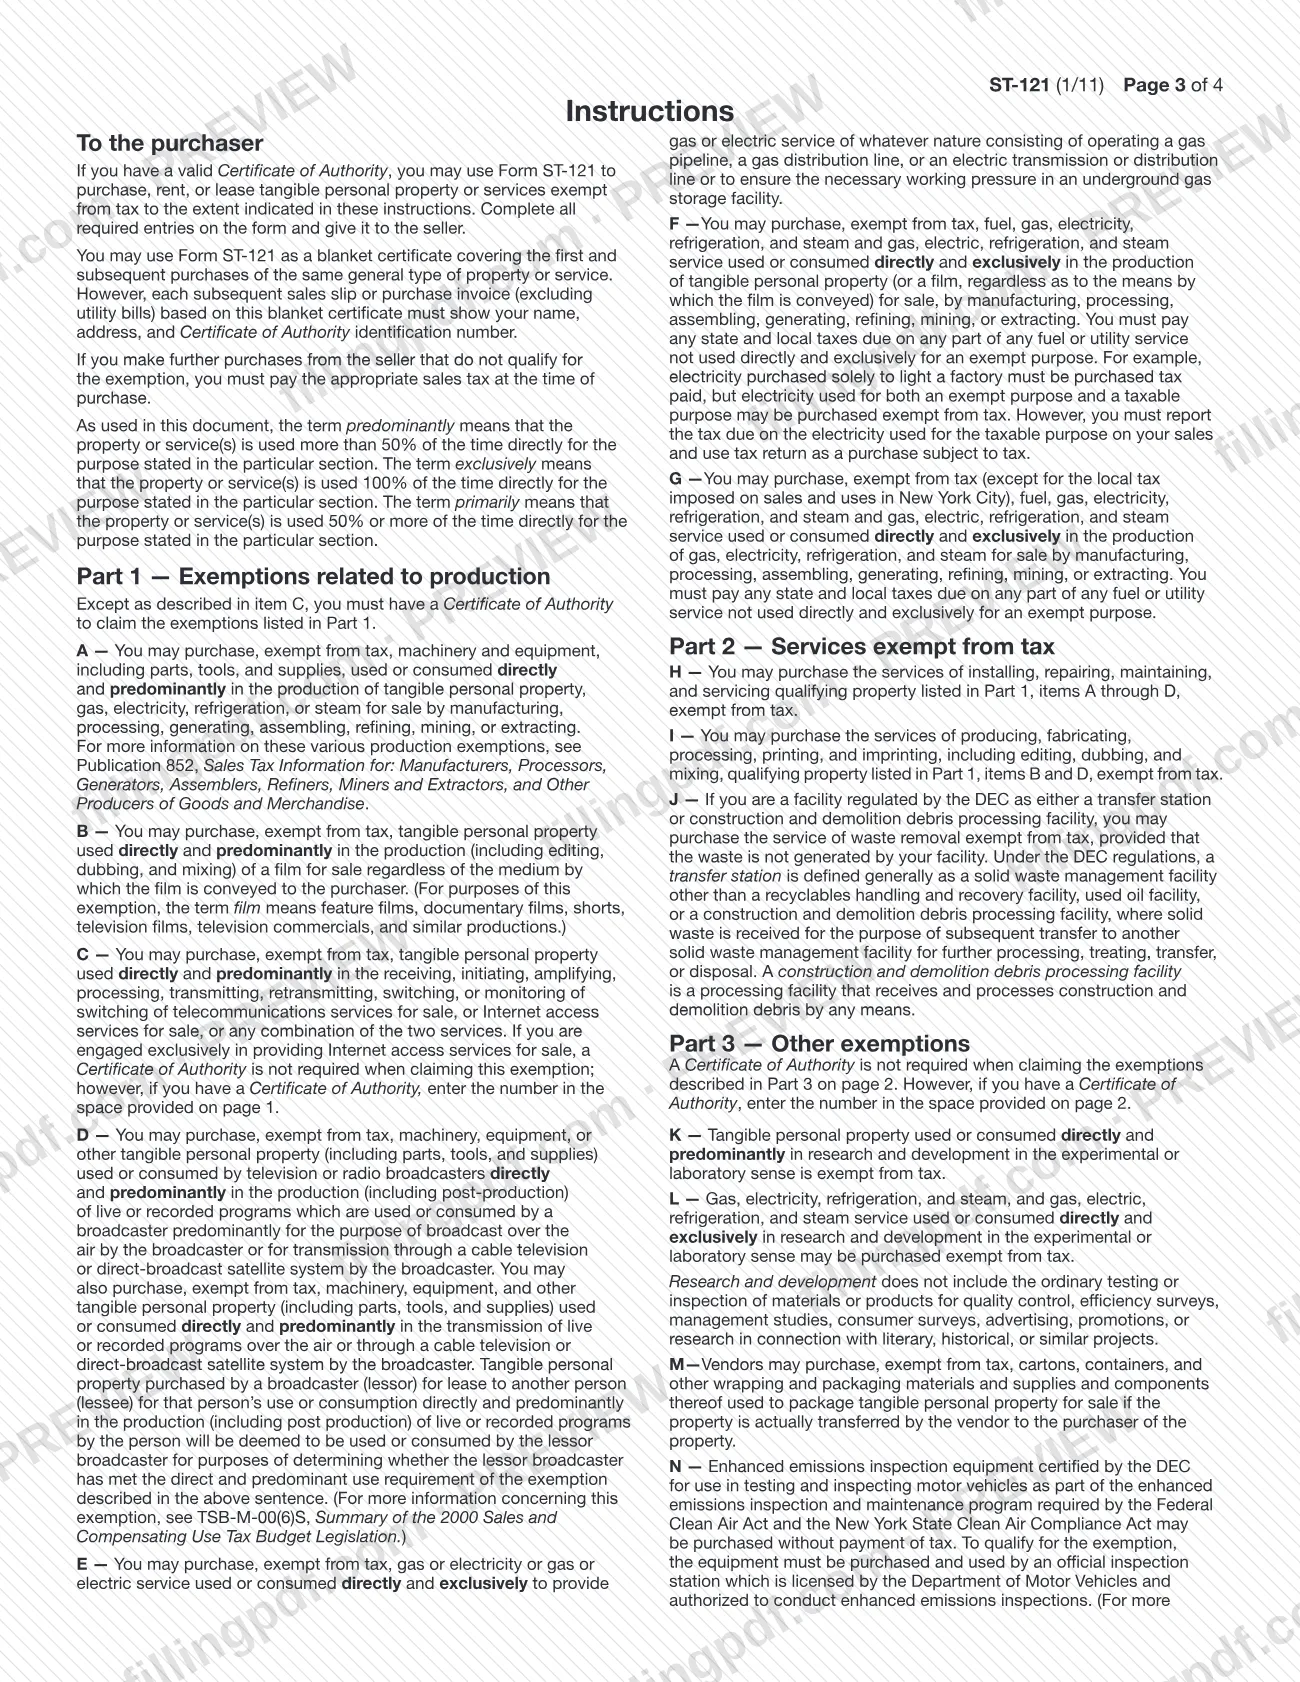
- Part 1 (items A–G): a Certificate of Authority is required, except for item C. If you provide only Internet access services for sale, you do not need one for item C, but you enter the number if you have one.
- Part 2 (items H–J): enter the Certificate of Authority number if applicable.
- Part 3 (items K–U): a Certificate of Authority is not required, but enter the number if you have one.
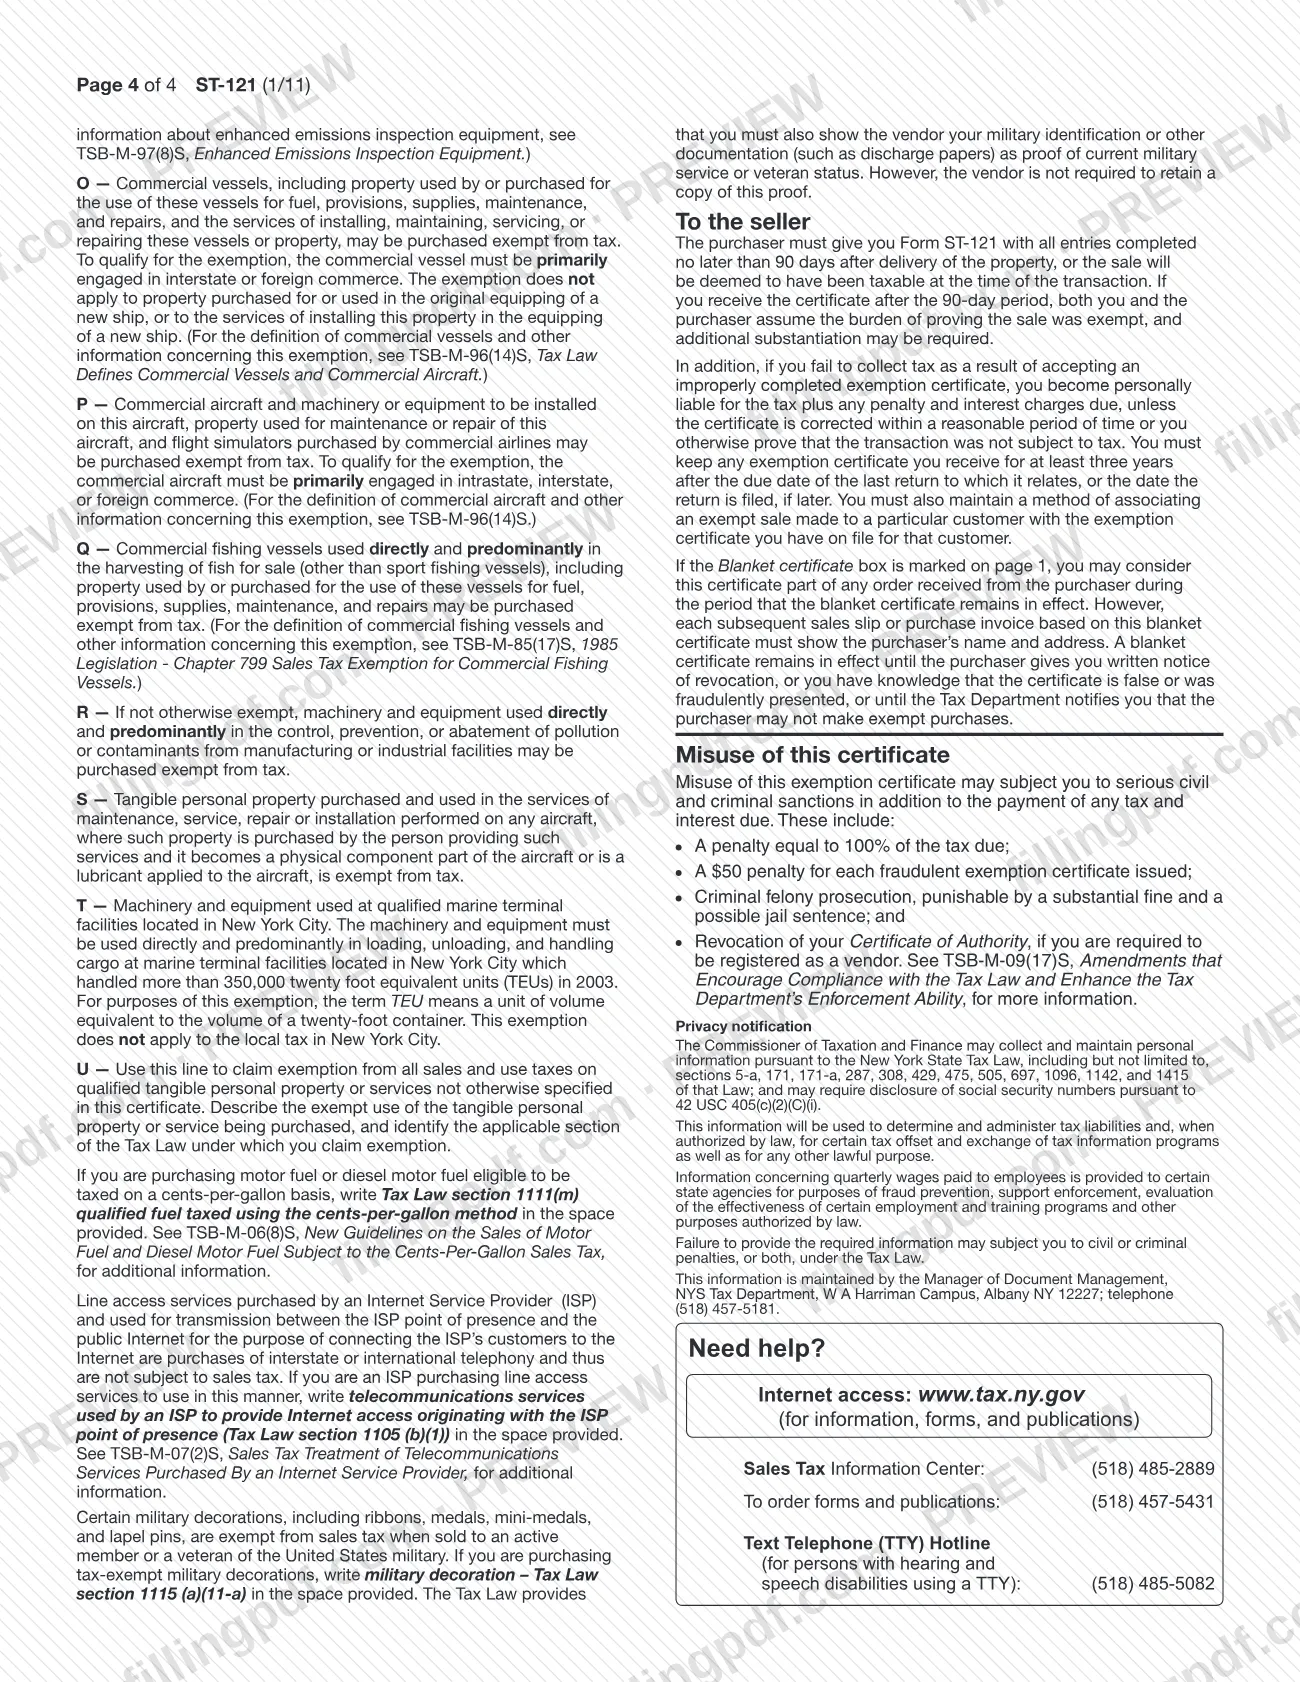
- Item J: only a facility regulated by the DEC as a transfer station or a construction and demolition debris processing facility, and only for waste not generated by that facility.
- Item N: the equipment must be bought and used by an official inspection station licensed by the Department of Motor Vehicles.
Do not use the form to buy exempt motor fuel or diesel motor fuel, except as described in the instructions for item U. The certification must be signed by an owner, partner or authorized person of the purchaser.
When to file ST-121
Give Form ST-121 to the seller when you make a purchase you claim is exempt. The seller must receive the certificate, with all entries completed, no later than 90 days after delivery of the property; otherwise the sale is deemed taxable at the time of the transaction. If it arrives after the 90-day period, the seller and purchaser share the burden of proving the sale was exempt, and more substantiation may be required.
A blanket certificate covers the first and later purchases of the same general type of property or service. It stays in effect until the purchaser gives the seller written notice of revocation, the seller knows it is false or was fraudulently presented, or the Tax Department notifies the seller that the purchaser may not make exempt purchases. Sellers keep each certificate for at least three years after the due date of the last return it relates to, or the date that return is filed, if later.
Documents you need
- Certificate of Authority number: required for Part 1 exemptions (items A–G) except item C when you provide only Internet access services; in Part 2 and Part 3 enter it only if you have one.
- Military identification or other documentation, such as discharge papers, as proof of current military service or veteran status, when buying exempt military decorations; the vendor need not keep a copy.
- Enhanced emissions inspection station license number, entered on the form for item N.
- A description of the exempt use and the Tax Law section that covers it, entered on the form for item U.
How to fill out ST-121
Enter seller and purchaser details
At the top of page 1, write the name and street address (city, state, ZIP code) of the seller and of the purchaser. The purchaser completes pages 1 and 2.
Mark single-purchase or blanket
Mark an X in Single-purchase certificate for one purchase, or Blanket certificate to cover the first and later purchases of the same general type of property or service.
Claim Part 1 production exemptions
Mark the box for each item A through G you claim and enter your Certificate of Authority number beside it. For items F and G, also mark each of fuel, gas, electricity, refrigeration, steam, or gas, electric, refrigeration or steam service that applies.
Claim Part 2 exempt services
For item H, mark which of Part 1 items A, B, C or D covers the property being serviced; for item I, mark B or D. Item J covers waste removal for DEC-regulated transfer stations and construction and demolition debris facilities. Enter your Certificate of Authority number if applicable.
Claim Part 3 other exemptions
Mark each item K through U that applies. For item L, mark the gas, electricity, refrigeration, steam or service boxes used in research and development; for item N, enter your inspection station license number.
Complete item U if you use it
Describe the exempt use and identify the section of the Tax Law covering the exemption. The instructions give wording to write for qualified motor fuel taxed cents-per-gallon, ISP line access services and military decorations.
Add your Certificate of Authority number
In Part 3, enter your Certificate of Authority number in the space provided if you have one; it is not required for those items.
Complete the certification on page 2
Type or print the name and title of the owner, partner or authorized person of the purchaser. That person signs and enters the date prepared.
Review, sign and download the PDF
Check that every claimed exemption has its box marked and that page 2 is signed. Download or print the completed PDF from FillingPDF and give it to the seller.
How to submit ST-121
You do not file Form ST-121 with the Tax Department yourself: the purchaser completes pages 1 and 2 and gives the certificate to the seller.
- Deliver to the seller: hand or send the completed, signed certificate to the vendor, who acts as agent for the Tax Department. Page 2 must carry the signed certification or the certificate is not valid.
- Blanket use: each later sales slip or purchase invoice based on the blanket certificate must show your name, address and Certificate of Authority identification number (utility bills are excluded).
- Seller's records: the seller keeps the certificate for at least three years and must be able to link each exempt sale to the certificate on file for that customer.
For questions, the Tax Department lists the Sales Tax Information Center at (518) 485-2889, forms ordering at (518) 457-5431, the TTY hotline at (518) 485-5082 and www.tax.ny.gov. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Leaving the certification on page 2 unsigned or incomplete; the form states the certificate is not valid unless the purchaser completes it.
- Claiming a Part 1 exemption without a Certificate of Authority, except item C for providers engaged exclusively in Internet access services.
- Using Form ST-121 to buy exempt motor fuel or diesel motor fuel, except as described for item U.
- Getting the completed certificate to the seller more than 90 days after delivery, which makes the sale deemed taxable at the time of the transaction.
- Buying fuel or utility service exempt under item F or G when part of it is not used directly and exclusively for the exempt purpose; tax is due on that part.
- Assuming items G and T are exempt from New York City local tax; both remain subject to it as the form states.
- Giving a blanket certificate for purchases that do not qualify; later purchases that do not qualify must be paid with tax at the time of purchase.
- Omitting your name, address and Certificate of Authority number from invoices issued under a blanket certificate, other than utility bills.
Frequently asked questions
What is Form ST-121 used for?
ST-121 is the New York exempt use certificate a purchaser gives a seller to buy, rent or lease qualifying property or services exempt from state and local sales and use taxes. The purchaser marks the exemption claimed and certifies on page 2 that the statements are true.
Do I need a Certificate of Authority to use Form ST-121?
For Part 1 exemptions (items A–G), yes, except item C when you are engaged exclusively in providing Internet access services for sale. For Part 3 it is not required; for Parts 2 and 3 you enter the number if you have one.
What is the difference between a single-purchase and a blanket certificate?
A single-purchase certificate covers one purchase. A blanket certificate covers the first and later purchases of the same general type of property or service, and later invoices must show your name, address and Certificate of Authority number.
How long does the seller have to get the certificate?
The seller must receive a fully completed ST-121 no later than 90 days after delivery of the property, or the sale is deemed taxable at the time of the transaction. A later certificate leaves both parties to prove the sale was exempt.
Where do I send Form ST-121?
Give it to the seller, not to the Tax Department. The vendor acts as agent for the Tax Department and keeps the certificate for at least three years after the due date of the last return it relates to, or the filing date if later.
Can I use ST-121 to buy motor fuel tax-free?
No, except as described in the instructions for item U. If you buy motor fuel or diesel motor fuel taxed on a cents-per-gallon basis, you write the Tax Law section 1111(m) wording on the form as the instructions say.
What happens if someone misuses an exempt use certificate?
The instructions list civil and criminal sanctions in addition to the tax and interest due, including penalties, felony prosecution and revocation of a Certificate of Authority. Sellers who accept an improperly completed certificate can become personally liable for the tax.
Can I fill out Form ST-121 online on FillingPDF?
Yes. You can fill out the fillable PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not send the certificate to the seller or the Tax Department; you deliver it to the seller yourself.
Ready to fill out ST-121?
Fill out ST-121 now