
Schedule 2 (Form 8849), Sales by Registered Ultimate Vendors, is the Internal Revenue Service (IRS) schedule that a registered ultimate vendor uses to claim a refund on undyed diesel fuel, undyed kerosene, kerosene for use in aviation, gasoline or aviation gasoline sold without the tax. It is not filed alone: it is attached to Form 8849, and you may not file it with any other schedule. On this page you can fill out Schedule 2 (Form 8849) online on FillingPDF and download or print the completed PDF. The IRS publishes the form and the latest information at www.irs.gov/Form8849.
Last updated
What is Schedule 2 (Form 8849)?
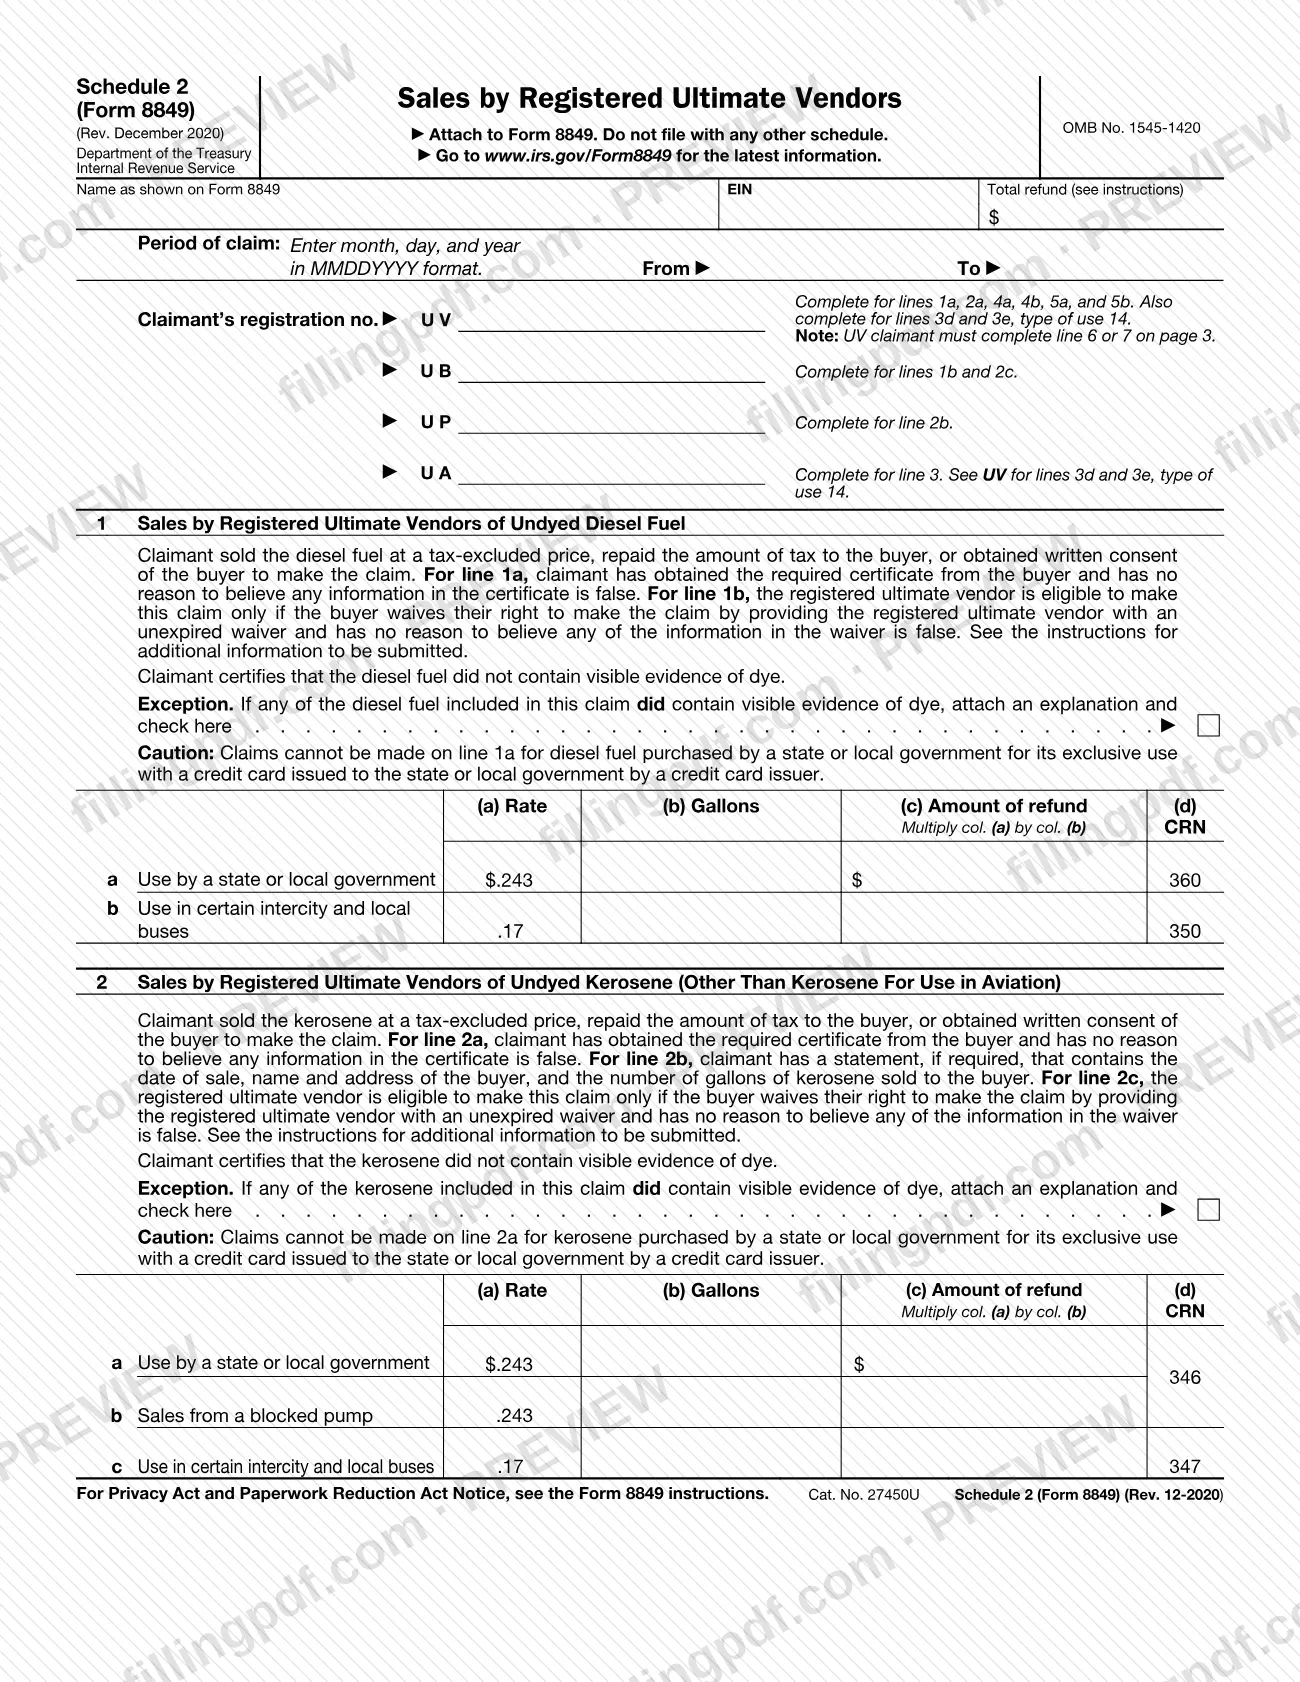
Schedule 2 (Form 8849), Sales by Registered Ultimate Vendors, is the IRS schedule on which a registered ultimate vendor of certain fuels claims a refund for fuel it sold at a tax-excluded price, or for which it repaid the tax to the buyer or obtained the buyer's written consent to make the claim.
The schedule is attached to Form 8849 and carries OMB No. 1545-1420. Its five sections follow the fuel sold:
- Line 1: undyed diesel fuel (use by a state or local government; use in certain intercity and local buses).
- Line 2: undyed kerosene other than kerosene for use in aviation (state or local government use, sales from a blocked pump, certain intercity and local buses).
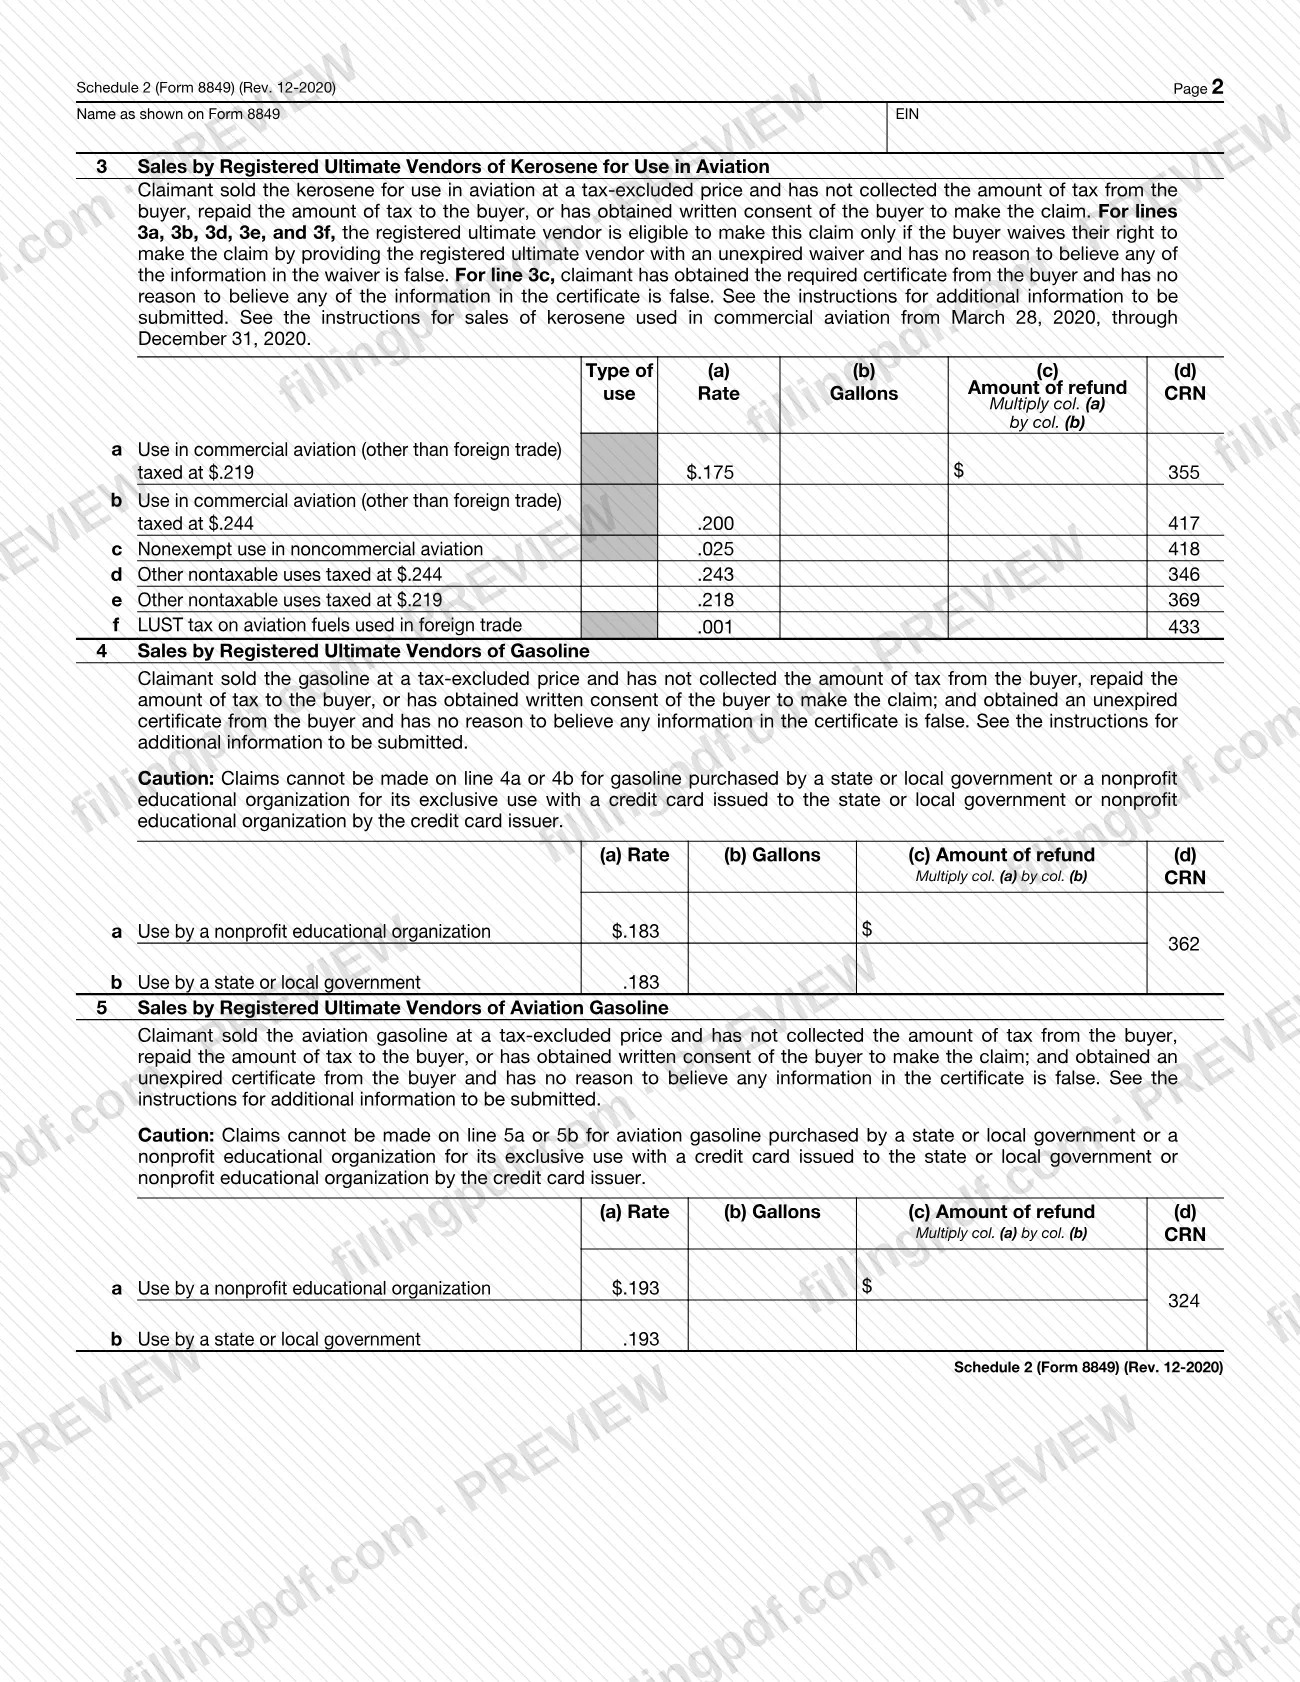
- Line 3: kerosene for use in aviation (commercial aviation, nonexempt noncommercial aviation, other nontaxable uses and the LUST tax on aviation fuels used in foreign trade).
- Line 4: gasoline (use by a nonprofit educational organization or a state or local government).
- Line 5: aviation gasoline (the same two kinds of use).
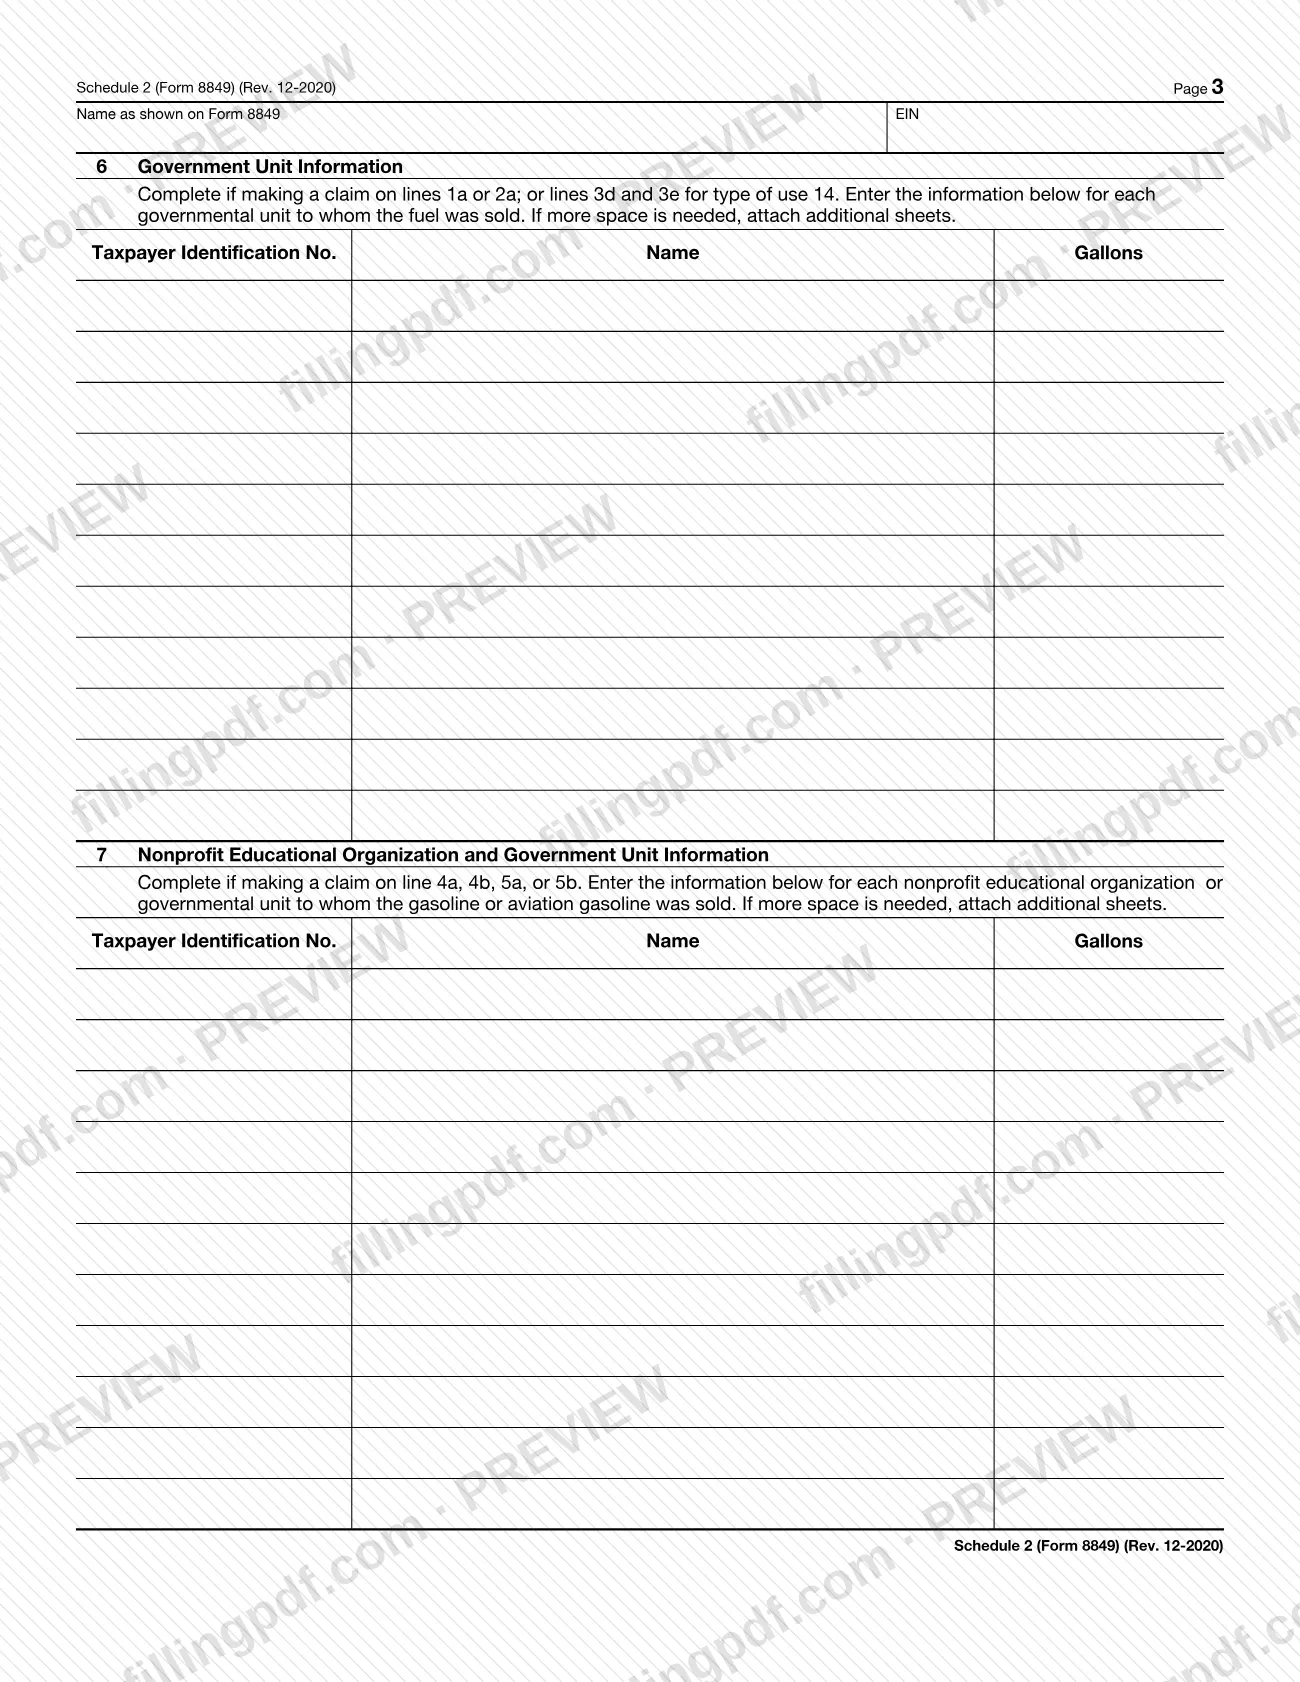
Page 3 adds Line 6, Government Unit Information, and Line 7, Nonprofit Educational Organization and Government Unit Information, which list the buyers and the gallons sold to each. The other schedules of Form 8849 cover different claims; the IRS instructions say only that Schedule 2 is for registered ultimate vendors. It is also a different document from the schedules numbered 2 in other IRS returns, so use the complete name, Schedule 2 (Form 8849).
Who needs to file Schedule 2 (Form 8849)?
Registered ultimate vendors of undyed diesel fuel, undyed kerosene, kerosene sold for use in aviation, gasoline or aviation gasoline use this schedule to claim a refund. Only one claim may be filed for any gallon.
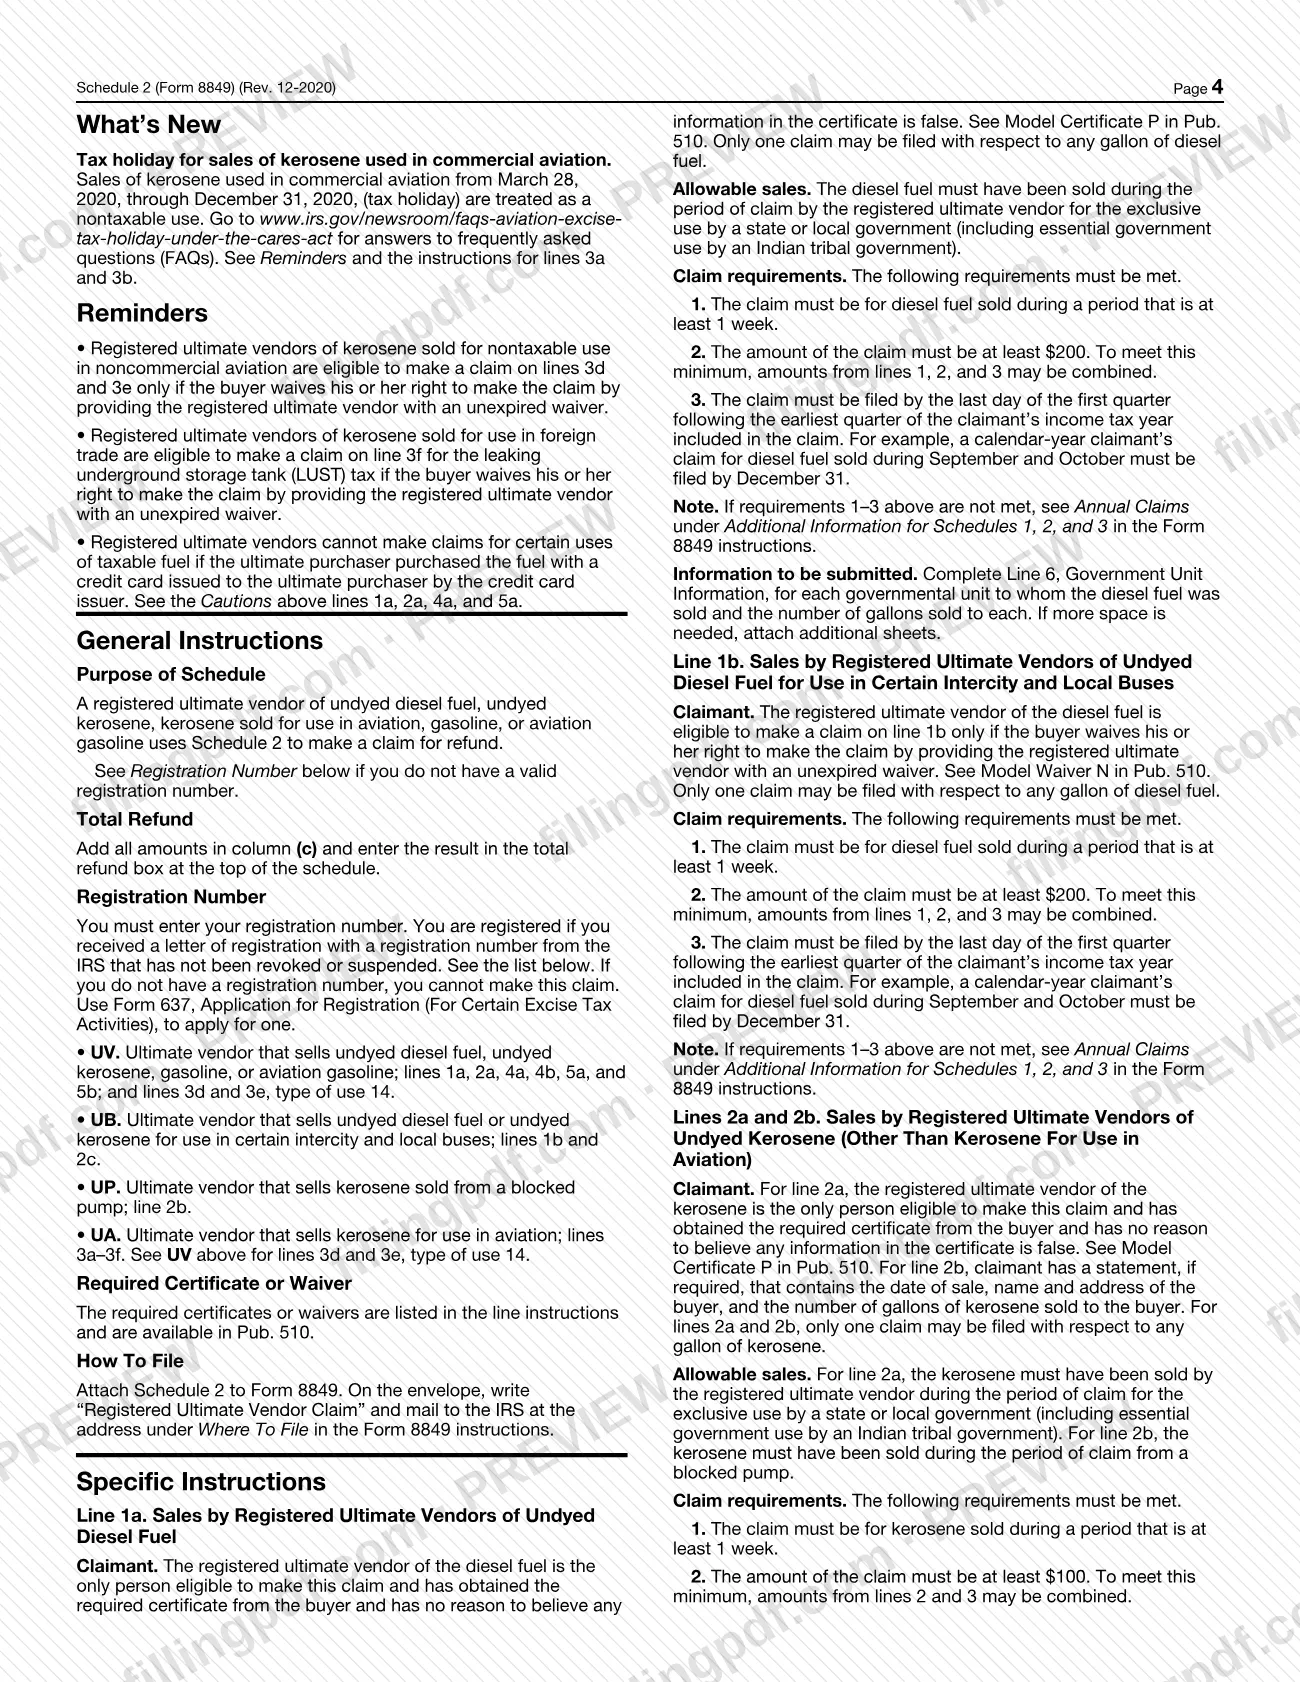
You must enter your registration number. You are registered if the IRS sent you a letter of registration with a registration number that has not been revoked or suspended. If you have no registration number, you cannot make the claim; Form 637, Application for Registration (For Certain Excise Tax Activities), is the form to apply for one. The number prefix decides which lines you may complete:
- UV: lines 1a, 2a, 4a, 4b, 5a and 5b, and lines 3d and 3e for type of use 14.
- UB: lines 1b and 2c (certain intercity and local buses).
- UP: line 2b (blocked pump).
- UA: line 3 (aviation kerosene); see UV for lines 3d and 3e, type of use 14.
Several lines are open to you only if the buyer waives the right to claim by giving you an unexpired waiver. Claims cannot be made on lines 1a, 2a, 4a, 4b, 5a and 5b when a state or local government, or a nonprofit educational organization where the line names it, bought the fuel for its exclusive use with a credit card issued to it by a credit card issuer. Do not file this schedule with any other schedule.
When to file Schedule 2 (Form 8849)
File Schedule 2 (Form 8849) by the last day of the first quarter following the earliest quarter of your income tax year included in the claim. For example, a calendar-year claimant's claim for fuel sold during September and October must be filed by December 31.
Two other requirements apply to every line group. The claim must cover fuel sold during a period of at least 1 week, and it must reach a minimum claim amount: higher for diesel fuel and for gasoline and aviation gasoline, lower for kerosene. Amounts from related lines may be combined to meet the minimum (lines 1, 2 and 3 for diesel fuel; lines 2 and 3 for kerosene; lines 4a, 4b, 5a and 5b for gasoline).
If these requirements are not met, the instructions send you to Annual Claims under Additional Information for Schedules 1, 2, and 3 in the Form 8849 instructions. Kerosene sold for commercial aviation from March 28, 2020, through December 31, 2020 (the tax holiday) is reported under type of use 15 on line 3d or 3e.
Documents you need
- Registration number from the IRS letter of registration (prefix UV, UB, UP or UA) that has not been revoked or suspended; apply with Form 637 if you have none.
- Certificate from the buyer for lines 1a and 2a (state or local government use), as in Model Certificate P in Pub. 510.
- Unexpired waiver from the buyer for lines 1b and 2c (certain intercity and local buses), as in Model Waiver N in Pub. 510.
- Unexpired waiver from the buyer for lines 3a and 3b, and for lines 3d, 3e and 3f except type of use 14, as in Model Waiver L in Pub. 510.
- Certificate from the ultimate purchaser for line 3c (nonexempt noncommercial aviation), as in Model Certificate Q in Pub. 510. For type of use 14 on lines 3d and 3e, use Model Certificate P.
- Unexpired certificate from the buyer for lines 4a, 4b, 5a and 5b, as in Model Certificate M in Pub. 510.
- For line 2b, a statement, if required, with the date of sale, name and address of the buyer and the gallons of kerosene sold.
- An explanation, if any fuel in the claim showed visible evidence of dye on lines 1 or 2; check the exception box.
- A statement that the claim is for the tax-holiday relief, for sales of kerosene used in commercial aviation from March 28, 2020, through December 31, 2020, reported as type of use 15.
- Additional sheets listing governmental units or nonprofit educational organizations and gallons sold, when lines 6 or 7 do not have enough space.
How to fill out Schedule 2 (Form 8849)
Enter name and EIN
At the top of each page, enter the name as shown on Form 8849 and the employer identification number (EIN).
Enter registration number and period
Enter your registration number (UV, UB, UP or UA, depending on the lines you complete) and the period of claim in MMDDYYYY format in the From and To boxes. The period must cover at least 1 week.
Complete line 1 for diesel fuel
Use line 1a for use by a state or local government or line 1b for certain intercity and local buses. Enter the gallons in column (b), multiply by the rate in column (a) and enter the result in column (c). Check the dye exception box only if any fuel showed visible evidence of dye.
Complete line 2 for kerosene
Use line 2a (state or local government), 2b (blocked pump) or 2c (certain intercity and local buses) for kerosene other than aviation kerosene. Enter gallons in column (b) and the refund in column (c).
Complete line 3 for aviation kerosene
On page 2, use lines 3a through 3f for the type of use that applies, entering gallons in column (b) and the refund in column (c). Report tax-holiday sales as type of use 15 on line 3d or 3e and attach the statement.
Complete lines 4 and 5
For gasoline use line 4a (nonprofit educational organization) or 4b (state or local government). For aviation gasoline use line 5a or 5b. Enter gallons and the refund in each row.
List buyers on lines 6 and 7
On page 3, line 6 lists each governmental unit for claims on lines 1a, 2a, or 3d and 3e (type of use 14). Line 7 lists each nonprofit educational organization or governmental unit for lines 4a, 4b, 5a and 5b. Give the taxpayer identification number, name and gallons, and attach additional sheets if needed.
Add up the total refund
Add all amounts in column (c) and enter the result in the Total refund box at the top of page 1.
Review, download and attach
Check the registration number, period, buyer information and totals. Download or print the completed PDF from FillingPDF and attach it to Form 8849 as described under How to submit.
How to submit Schedule 2 (Form 8849)
You submit Schedule 2 (Form 8849) on paper, attached to Form 8849, and mail the package to the IRS.
- Attach to Form 8849: the schedule is not filed on its own and not with any other schedule.
- Mark the envelope: write "Registered Ultimate Vendor Claim" on the envelope.
- Mail: send it to the IRS at the address listed under Where To File in the Form 8849 instructions. The schedule prints no address of its own.
- Extra sheets: if lines 6 or 7 need more space for governmental units or nonprofit educational organizations, attach additional sheets.
Other items the instructions ask for with particular claims: an explanation if the fuel showed visible evidence of dye, and a statement explaining the tax-holiday relief for type of use 15 claims. The form describes no online filing channel. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Filing without a valid registration number; the instructions say you cannot make the claim without one.
- Filing the schedule with another Form 8849 schedule; the form says to attach it to Form 8849 and not to file it with any other schedule.
- Claiming on line 1a, 2a, 4a, 4b, 5a or 5b for fuel bought with a credit card issued to the state or local government (or nonprofit educational organization) by a card issuer.
- Claiming on line 1b, 2c, 3a, 3b, 3d, 3e, 3f or lines 4 and 5 without the buyer's unexpired waiver or certificate.
- Claiming fuel that showed visible evidence of dye without attaching an explanation and checking the exception box.
- Leaving lines 6 or 7 blank when claiming lines 1a, 2a, 3d and 3e (type of use 14), 4a, 4b, 5a or 5b.
- Reporting tax-holiday kerosene sales on lines 3a or 3b instead of type of use 15 on line 3d or 3e, or omitting the explanatory statement.
- Using a period of claim shorter than 1 week, or filing after the last day of the first quarter following the earliest quarter included in the claim.
- Entering dates in the Period of claim boxes in a format other than MMDDYYYY.
- Mailing the package without writing "Registered Ultimate Vendor Claim" on the envelope.
Frequently asked questions
What is Schedule 2 (Form 8849)?
Schedule 2 (Form 8849), Sales by Registered Ultimate Vendors, is the IRS schedule a registered ultimate vendor attaches to Form 8849 to claim a refund on undyed diesel fuel, undyed kerosene, aviation kerosene, gasoline or aviation gasoline sold without the tax.
Who can file Schedule 2 (Form 8849)?
Only a registered ultimate vendor with a valid registration number from the IRS (prefix UV, UB, UP or UA). Without one you cannot make the claim; Form 637 is the application for registration. Some lines also need the buyer's unexpired waiver or certificate.
When is Schedule 2 (Form 8849) due?
By the last day of the first quarter following the earliest quarter of your income tax year included in the claim. A calendar-year vendor claiming September and October sales must file by December 31. The sales period must be at least 1 week.
Where do I mail Schedule 2 (Form 8849)?
Attach it to Form 8849, write "Registered Ultimate Vendor Claim" on the envelope and mail it to the address under Where To File in the Form 8849 instructions. The schedule itself prints no address.
Can I file Schedule 2 with other Form 8849 schedules?
No. The form says to attach it to Form 8849 and not to file it with any other schedule. Claim totals from Schedule 2 go in the Total refund box at the top of page 1.
What are lines 6 and 7 for?
They list the buyers behind your claim. Line 6 covers governmental units for lines 1a, 2a, and 3d and 3e (type of use 14); line 7 covers nonprofit educational organizations and governmental units for lines 4 and 5. Give each one's taxpayer identification number, name and gallons.
How do I report the 2020 aviation tax holiday on Schedule 2?
For kerosene sold for commercial aviation from March 28, 2020, through December 31, 2020, use type of use 15 on line 3d or 3e, depending on the rate paid, and attach a statement explaining that the claim is for the tax-holiday relief.
Can I fill out Schedule 2 (Form 8849) online on FillingPDF?
Yes. You can fill out the fillable PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file it with the IRS; you mail it with Form 8849 as the instructions describe.
Ready to fill out Schedule 2 (Form 8849)?
Fill out Schedule 2 (Form 8849) now