
Schedule A (Form 5713), International Boycott Factor (Section 999(c)(1)), is the Internal Revenue Service (IRS) schedule that turns your boycott purchases, sales and payroll into a single ratio, the international boycott factor. It is used by taxpayers who participated in or cooperated with an international boycott and who use that factor to figure the loss of tax benefits. On this page you can fill out the form online on FillingPDF and download or print the completed PDF; the official PDF is published by the IRS, and the schedule is attached to Form 5713.
Last updated
What is Schedule A (Form 5713)?
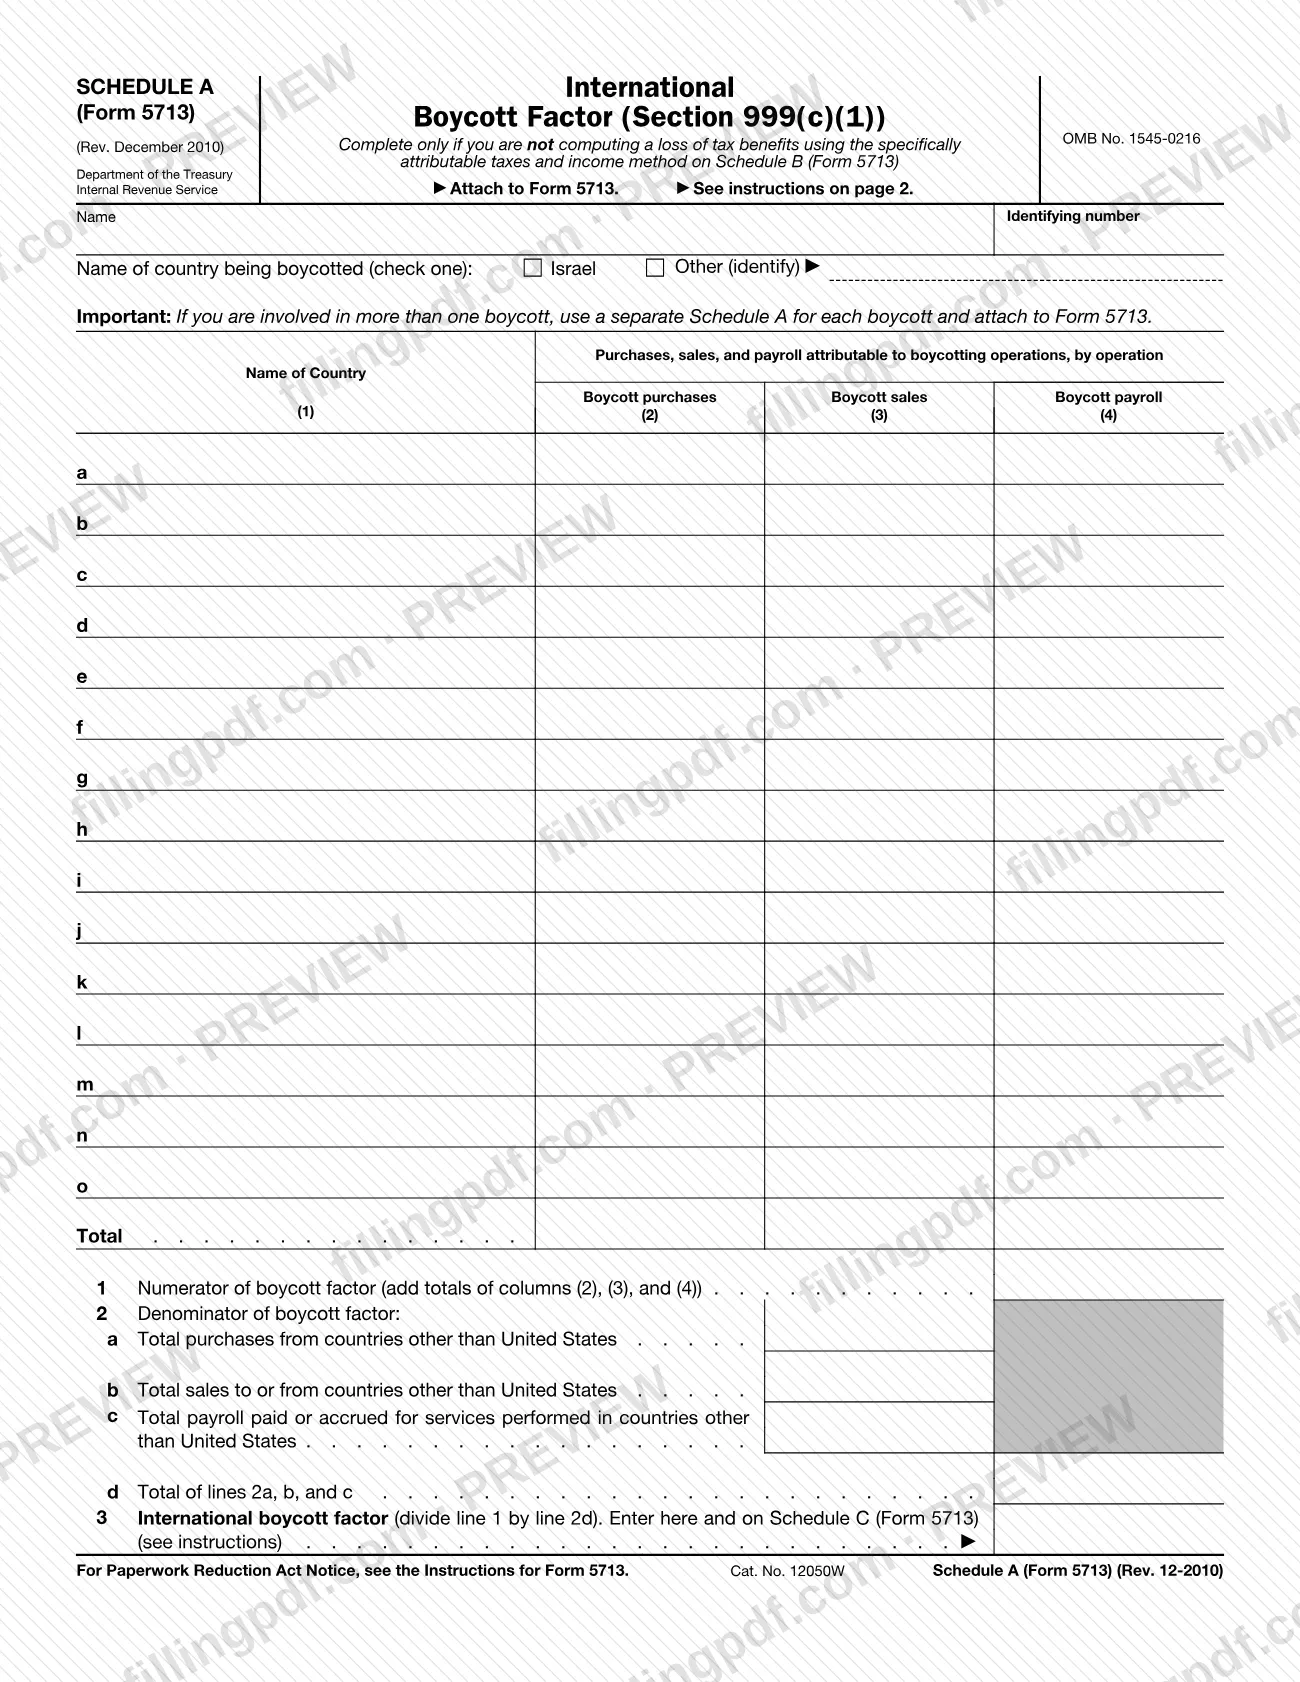
Schedule A (Form 5713), International Boycott Factor (Section 999(c)(1)), is the IRS schedule on which you divide your boycott purchases, sales and payroll by your total purchases, sales and payroll in countries other than the United States, producing the international boycott factor.
The schedule has two parts. A table of lines a through o lists each boycott operation with the name of the country (column 1) and its boycott purchases (column 2), boycott sales (column 3) and boycott payroll (column 4). Lines 1 through 3 then build the factor: line 1 is the numerator, line 2 is the denominator and line 3 is the factor itself.
The result is carried to Schedule C (Form 5713), on the line that matches the tax benefit you lose. The form is printed under OMB No. 1545-0216, Rev. December 2010, and is attached to Form 5713.
It is only the factor method. The form says to complete it only if you are not computing the loss of tax benefits with the specifically attributable taxes and income method on Schedule B (Form 5713). It is one schedule of Form 5713 and is not a stand-alone return.
Who needs to file Schedule A (Form 5713)?
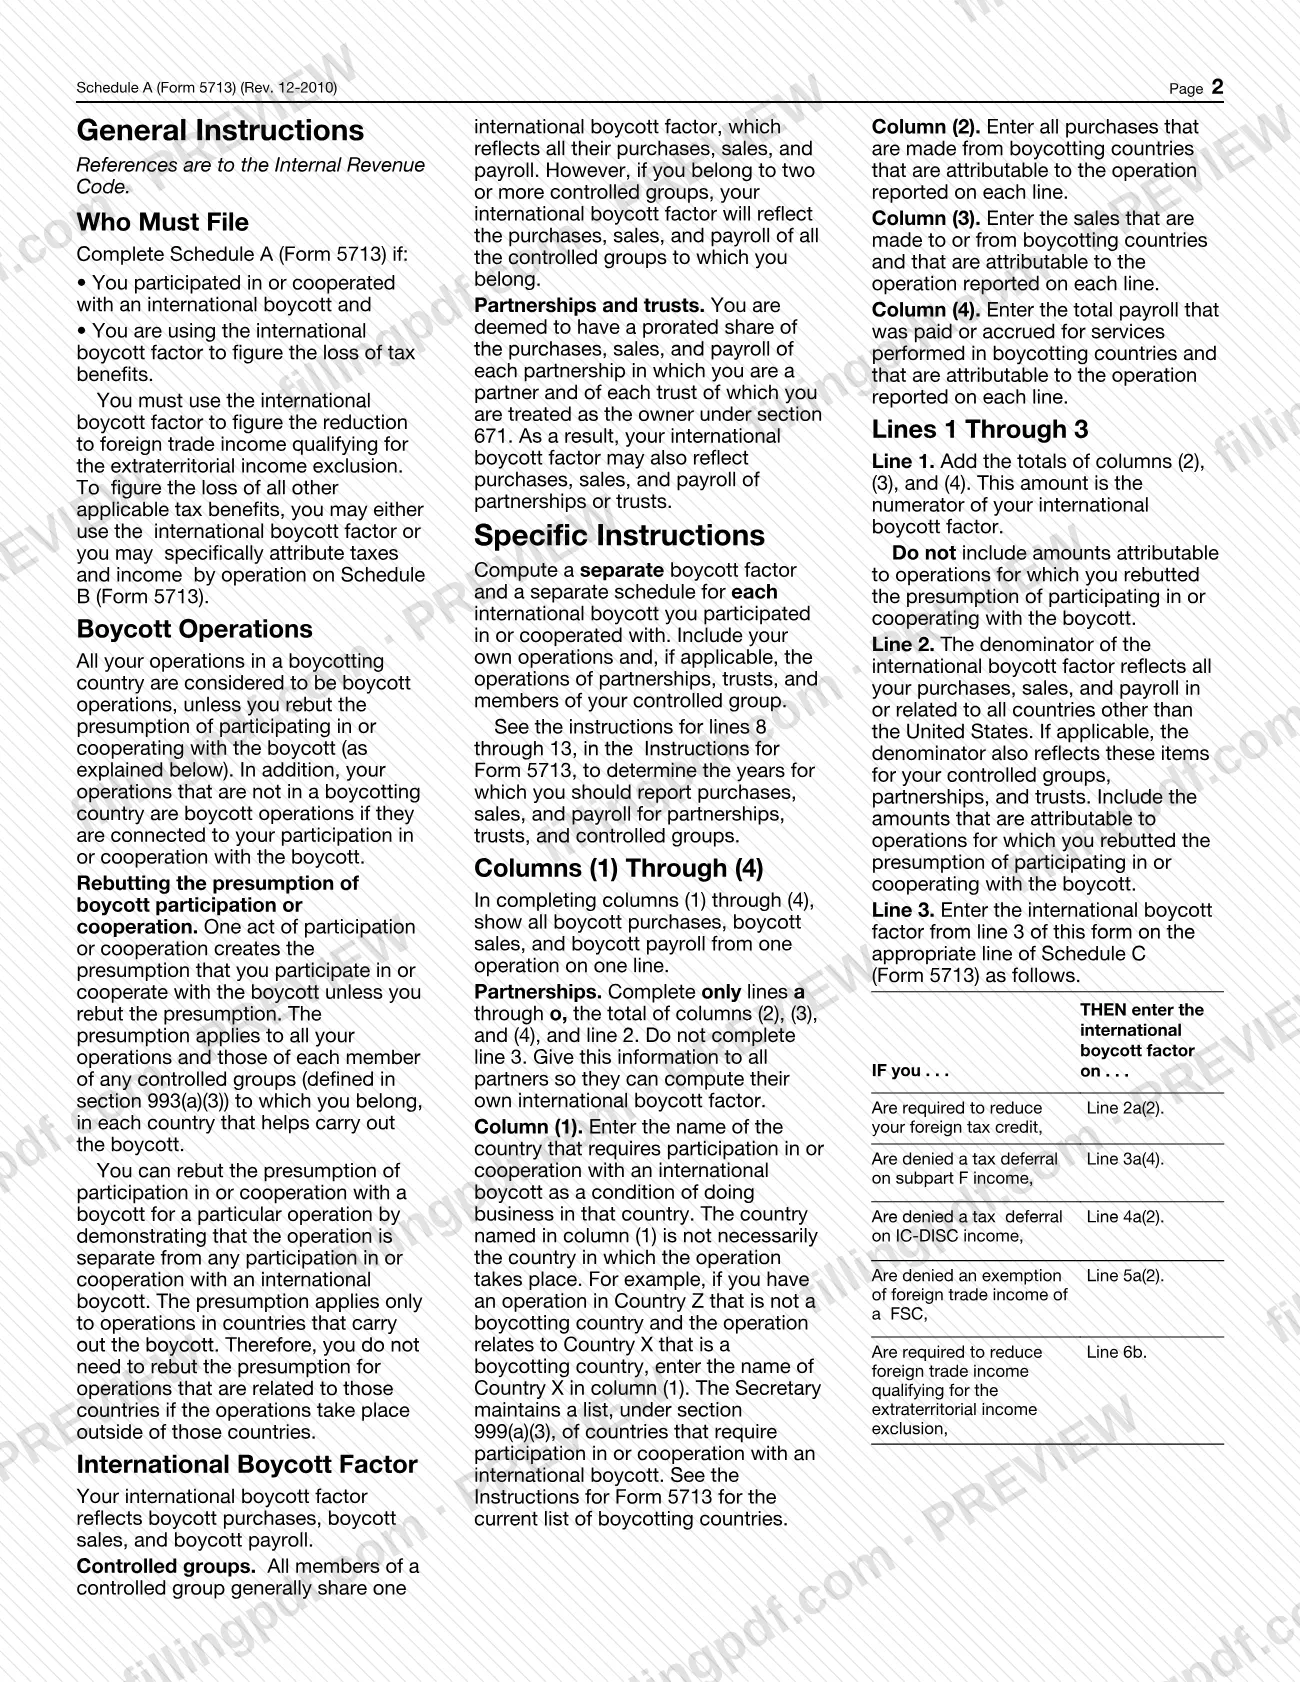
You complete Schedule A (Form 5713) if both of these are true:
- you participated in or cooperated with an international boycott, and
- you are using the international boycott factor to figure the loss of tax benefits.
You must use the factor to figure the reduction to foreign trade income qualifying for the extraterritorial income exclusion. For the loss of all other applicable tax benefits, you may use the factor or you may attribute taxes and income specifically, by operation, on Schedule B (Form 5713). If you choose the Schedule B method, this schedule is not completed.
Other situations covered by the instructions:
- More than one boycott: use a separate Schedule A for each boycott and attach each to Form 5713.
- Controlled groups: members share one factor reflecting all their purchases, sales and payroll. If you belong to two or more controlled groups, your factor reflects all of them.
- Partnerships: complete only lines a through o, the totals of columns (2), (3) and (4), and line 2. Do not complete line 3; give the information to all partners so they can compute their own factor.
- Partners and trust owners: you are deemed to hold a prorated share of each partnership's, and each section 671 trust's, purchases, sales and payroll, so your factor may reflect them.
When to file Schedule A (Form 5713)
Schedule A (Form 5713) is completed when you attach it to Form 5713 and use the international boycott factor to figure the loss of tax benefits. The schedule prints no separate due date, so it travels with Form 5713 whenever that form is filed.
The Instructions for Form 5713 (lines 8 through 13) tell you which years to report purchases, sales and payroll for partnerships, trusts and controlled groups, so check them before you gather figures. If you are involved in more than one boycott, prepare a separate schedule for each at the same time.
How to fill out Schedule A (Form 5713)
Confirm Schedule A applies to you
Use this schedule only if you are not computing the loss of tax benefits with the specifically attributable taxes and income method on Schedule B (Form 5713). Prepare one schedule per boycott.
Enter your name and identifying number
Write your name and identifying number in the boxes at the top of the form.
Check the boycotted country
Under Name of country being boycotted (check one), check Israel or Other (identify) and write the country's name if you check Other.
List each boycott operation
On lines a through o, enter one operation per line. In column (1) name the country that requires participation in or cooperation with the boycott as a condition of doing business there; this is not necessarily where the operation takes place.
Enter boycott purchases, sales and payroll
For each operation, column (2) is purchases from boycotting countries, column (3) is sales to or from boycotting countries, and column (4) is payroll paid or accrued for services performed in boycotting countries.
Total the columns
Add each of columns (2), (3) and (4) on the Total line. Partnerships complete only lines a through o, these totals and line 2.
Figure the numerator on line 1
On line 1, add the totals of columns (2), (3) and (4). Leave out amounts attributable to operations for which you rebutted the presumption of participating in or cooperating with the boycott.
Complete the denominator on lines 2a to 2d
Enter total purchases from countries other than the United States on line 2a, total sales to or from those countries on line 2b, and total payroll paid or accrued for services performed there on line 2c. Add them on line 2d, including rebutted operations.
Divide to get the factor on line 3
Divide line 1 by line 2d and enter the international boycott factor on line 3. Partnerships skip this line.
Carry the factor to Schedule C
Enter line 3 on Schedule C (Form 5713): line 2a(2) for foreign tax credit reduction, 3a(4) for subpart F deferral denial, 4a(2) for IC-DISC deferral denial, 5a(2) for FSC exemption denial, or 6b for the extraterritorial income exclusion reduction.
Review, download and attach
Check the totals and the country entries, then download or print the completed PDF from FillingPDF and attach it to Form 5713.
How to submit Schedule A (Form 5713)
Schedule A (Form 5713) has no filing channel of its own: you attach it to Form 5713, and it is sent the way Form 5713 is sent.
- Attach to Form 5713. Add one completed Schedule A for each international boycott you participated in or cooperated with.
- Use the factor on Schedule C. Enter the line 3 result on the matching line of Schedule C (Form 5713), which is part of the same filing.
- Where to send it. The schedule prints no mailing address, portal or appointment rule. Follow the Instructions for Form 5713 for how and where that form is filed.
FillingPDF lets you fill out and download the PDF; submission follows the channels that apply to Form 5713.
Common mistakes to avoid
- Completing Schedule A (Form 5713) when you are computing the loss of tax benefits with the specifically attributable taxes and income method on Schedule B (Form 5713).
- Combining two boycotts on one schedule; the form requires a separate Schedule A for each boycott, attached to Form 5713.
- Including on line 1 the amounts for operations where you rebutted the presumption of participating in or cooperating with the boycott.
- Leaving the rebutted operations out of line 2; the denominator includes the amounts attributable to them.
- Putting more than one operation on a single line of the table; each operation's boycott purchases, sales and payroll go on one line.
- Completing line 3 as a partnership; partnerships stop after lines a through o, the column totals and line 2, and give the figures to their partners.
- Entering the line 3 factor on the wrong line of Schedule C (Form 5713) for the tax benefit involved, for example line 6b for the extraterritorial income exclusion reduction.
- Entering a country in column (1) only because the operation takes place there; column (1) names the country that requires boycott participation as a condition of doing business, which may be a different country.
Frequently asked questions
What is Schedule A (Form 5713)?
Schedule A (Form 5713) is the IRS schedule that computes the international boycott factor under section 999(c)(1). It compares your boycott purchases, sales and payroll with your totals in countries other than the United States, and the result is carried to Schedule C (Form 5713).
Who has to complete Schedule A (Form 5713)?
Taxpayers who participated in or cooperated with an international boycott and who are using the international boycott factor to figure the loss of tax benefits. If you use the specifically attributable taxes and income method on Schedule B (Form 5713), you do not complete it.
Do I file Schedule A (Form 5713) by itself?
No. The schedule says to attach it to Form 5713, so it is filed with that form and has no separate address or due date. Its line 3 result goes on Schedule C (Form 5713).
What if I took part in more than one boycott?
Use a separate Schedule A for each boycott and attach all of them to Form 5713. The instructions call for a separate boycott factor and a separate schedule for each international boycott you participated in or cooperated with.
What do I put in column (1) of the table?
Enter the country that requires participation in or cooperation with an international boycott as a condition of doing business there. It need not be the country where the operation takes place. See the Instructions for Form 5713 for the current list of boycotting countries.
Where does the line 3 boycott factor go?
On Schedule C (Form 5713), on the line matching the tax benefit: 2a(2) foreign tax credit, 3a(4) subpart F deferral, 4a(2) IC-DISC deferral, 5a(2) FSC exemption, or 6b for foreign trade income qualifying for the extraterritorial income exclusion.
How do partnerships complete Schedule A (Form 5713)?
A partnership completes only lines a through o, the totals of columns (2), (3) and (4), and line 2. It leaves line 3 blank and gives the information to all partners so they can compute their own international boycott factor.
Can I fill out Schedule A (Form 5713) online on FillingPDF?
Yes. You can fill out the fillable PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file anything with the IRS; the schedule goes in with Form 5713 through the IRS channels.
Ready to fill out Schedule A (Form 5713)?
Fill out Schedule A (Form 5713) now