
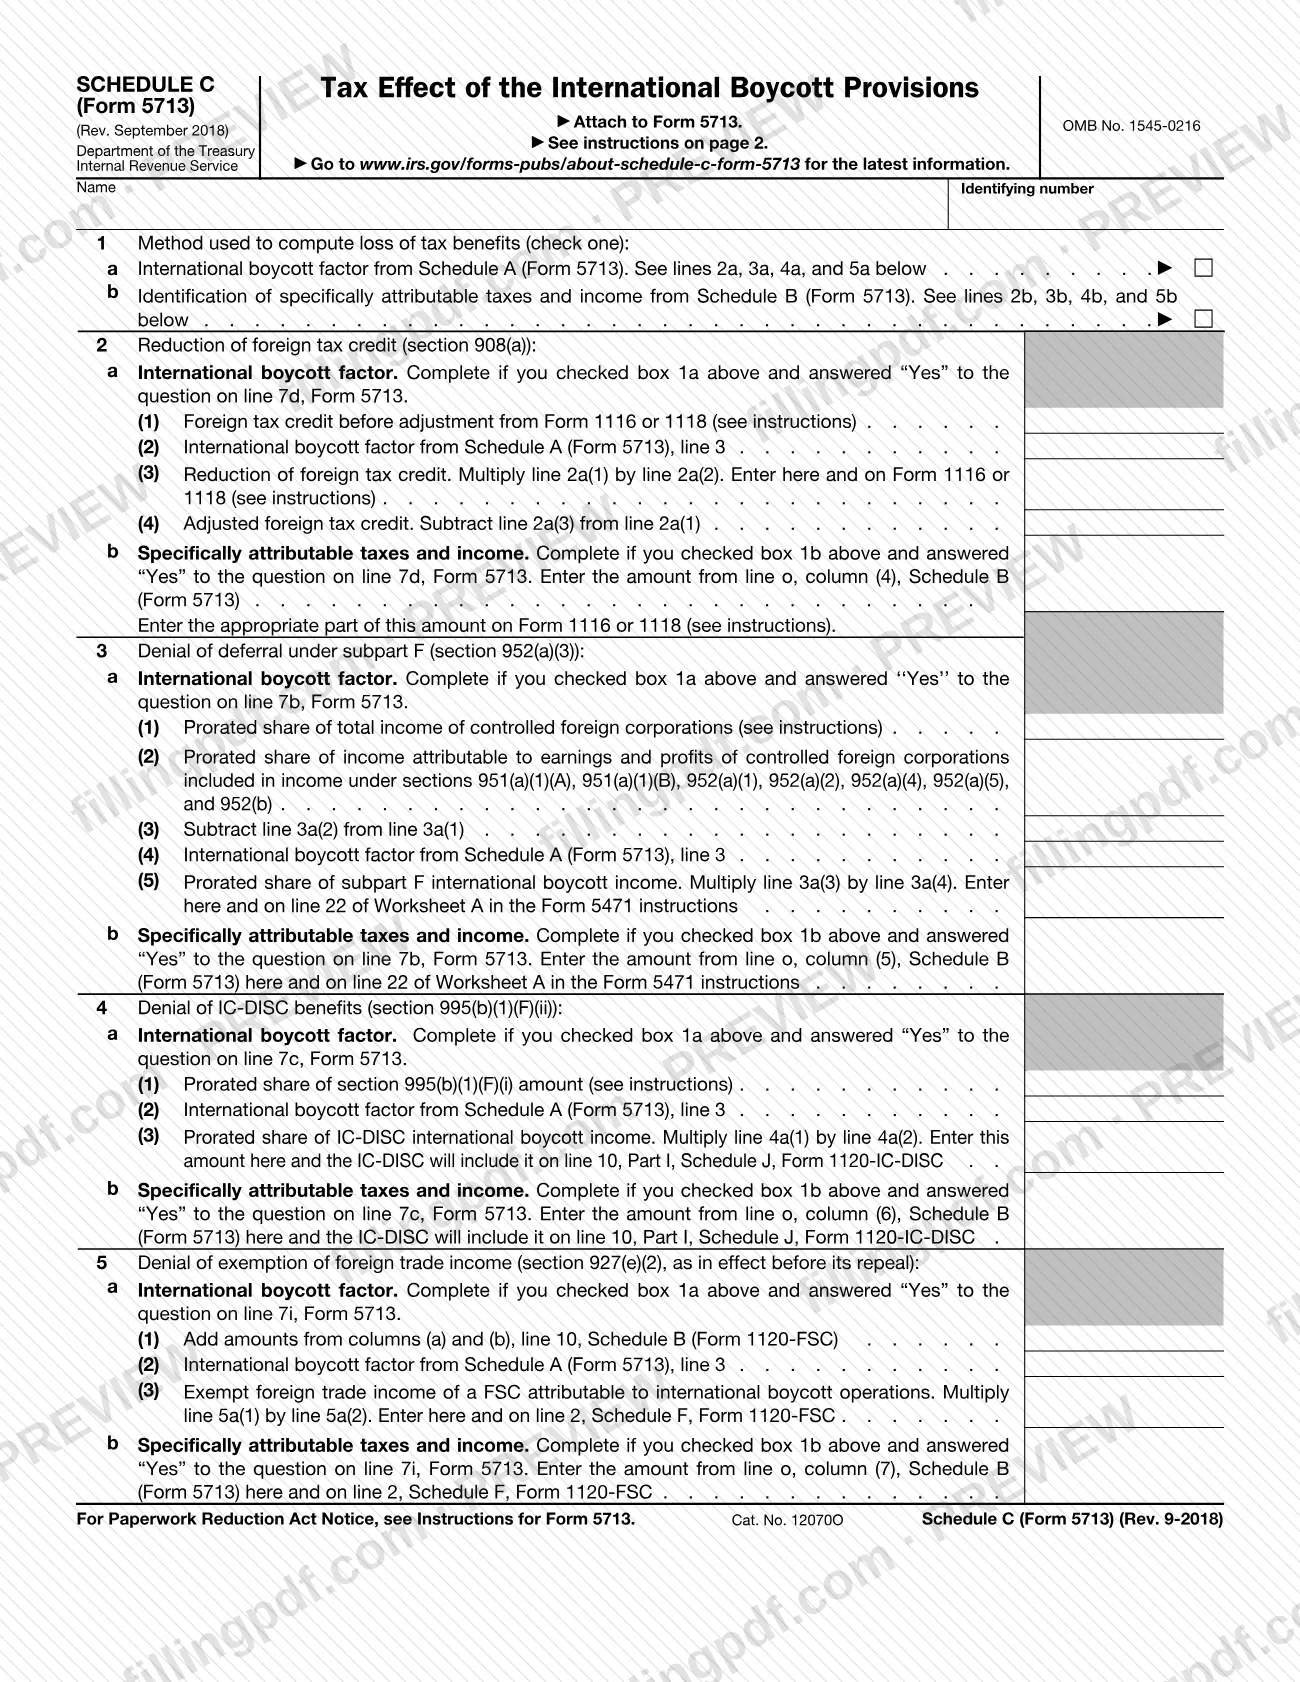
Schedule C (Form 5713), Tax Effect of the International Boycott Provisions, is the Internal Revenue Service (IRS) schedule that computes the tax benefits lost because of participation in or cooperation with an international boycott. You complete it if you completed Schedule A or Schedule B of Form 5713, and you attach it to Form 5713. On this page you can fill out the form online on FillingPDF and download or print the completed PDF; the original PDF and the latest information are published by the IRS at www.irs.gov/forms-pubs/about-schedule-c-form-5713.
Last updated
What is Schedule C (Form 5713)?
Schedule C (Form 5713), Tax Effect of the International Boycott Provisions, is the IRS schedule, attached to Form 5713, used to compute the loss of tax benefits attributable to participation in or cooperation with an international boycott.
The schedule starts with a choice on line 1 of the method used to compute the loss: the international boycott factor from Schedule A (Form 5713), or the identification of specifically attributable taxes and income from Schedule B (Form 5713). Lines 2 through 5 then work through each benefit that is reduced or denied, using the method you checked:
- Line 2: reduction of foreign tax credit (section 908(a)).
- Line 3: denial of deferral under subpart F (section 952(a)(3)).
- Line 4: denial of IC-DISC benefits (section 995(b)(1)(F)(ii)).
- Line 5: denial of exemption of foreign trade income (section 927(e)(2), as in effect before its repeal).
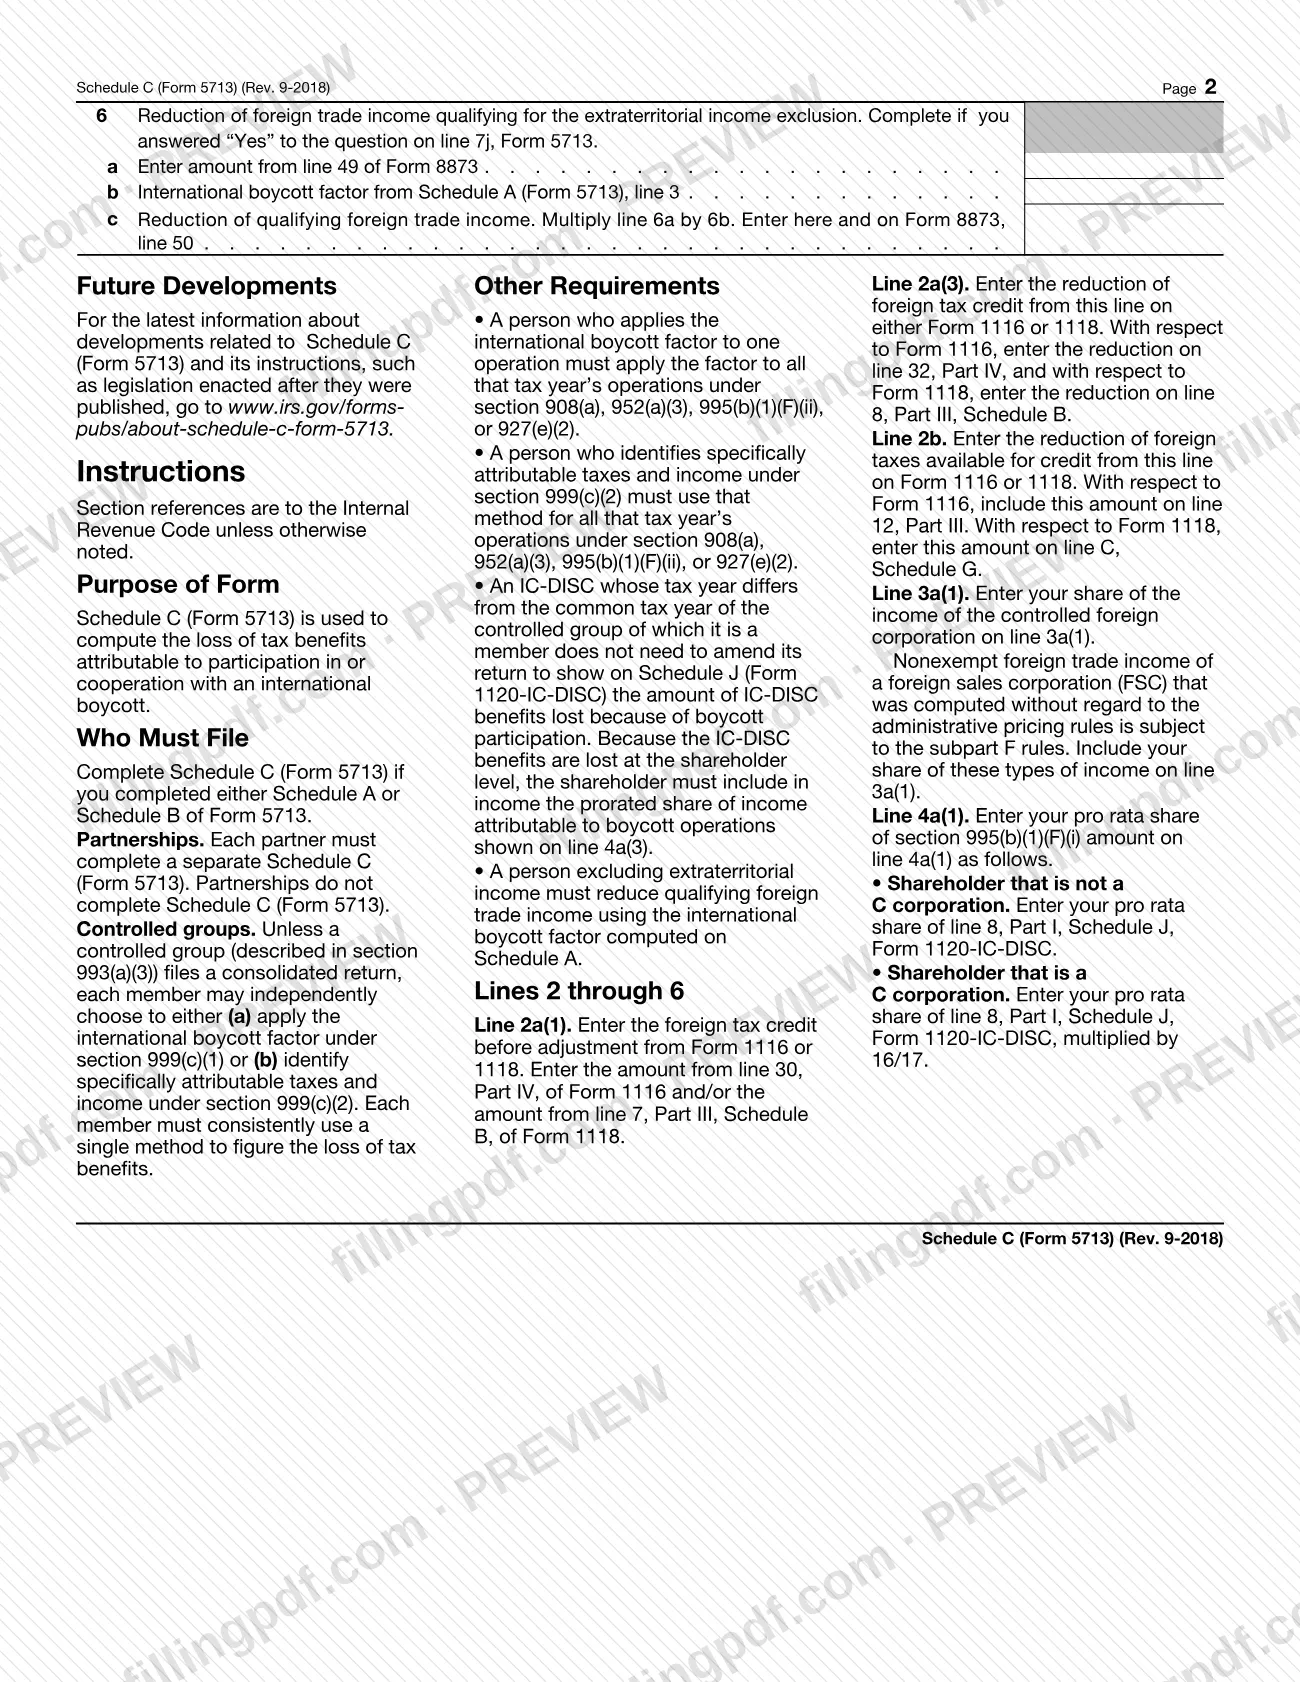
Line 6, on page 2, reduces foreign trade income that qualifies for the extraterritorial income exclusion.
The results are carried to other returns and forms, including Form 1116 or 1118, Worksheet A in the Form 5471 instructions, Form 1120-IC-DISC, Form 1120-FSC and Form 8873. The form is identified as OMB No. 1545-0216, revision Rev. September 2018, and refers to the Instructions for Form 5713 for the Paperwork Reduction Act Notice.
Who needs to file Schedule C (Form 5713)?
You complete Schedule C (Form 5713) if you completed either Schedule A or Schedule B of Form 5713.
- Partnerships: a partnership does not complete Schedule C (Form 5713). Each partner completes a separate Schedule C (Form 5713).
- Controlled groups: unless the controlled group (described in section 993(a)(3)) files a consolidated return, each member may independently choose to apply the international boycott factor under section 999(c)(1) or to identify specifically attributable taxes and income under section 999(c)(2). Each member must use a single method consistently to figure the loss of tax benefits.
- IC-DISC shareholders: an IC-DISC whose tax year differs from the common tax year of its controlled group does not need to amend its return to show the benefits lost on Schedule J (Form 1120-IC-DISC). Because those benefits are lost at the shareholder level, the shareholder includes in income the prorated share of income attributable to boycott operations shown on line 4a(3).
- Exporters excluding extraterritorial income: a person excluding extraterritorial income must reduce qualifying foreign trade income using the international boycott factor computed on Schedule A.
A person who applies the international boycott factor to one operation must apply it to all of that tax year's operations under sections 908(a), 952(a)(3), 995(b)(1)(F)(ii) or 927(e)(2). The same rule applies to the specifically attributable method under section 999(c)(2).
When to file Schedule C (Form 5713)
Schedule C (Form 5713) is completed whenever you complete Schedule A or Schedule B of Form 5713, because the form says to attach it to Form 5713. It has no due date of its own printed on it, so it travels with Form 5713 whenever that form is submitted.
The lines you complete depend on the answers on Form 5713: lines 2a and 2b follow the question on line 7d, lines 3a and 3b follow line 7b, lines 4a and 4b follow line 7c, lines 5a and 5b follow line 7i, and line 6 follows line 7j. For any deadline that applies to Form 5713, check the Instructions for Form 5713 and www.irs.gov/forms-pubs/about-schedule-c-form-5713.
Documents you need
- Schedule A (Form 5713): needed if you check box 1a, because the international boycott factor on lines 2a(2), 3a(4), 4a(2), 5a(2) and 6b comes from its line 3.
- Schedule B (Form 5713): needed if you check box 1b, because lines 2b, 3b, 4b and 5b take their amounts from line o, columns (4) through (7).
- Form 1116 or Form 1118: needed for line 2a(1), which takes the amount from line 30, Part IV, of Form 1116 and/or line 7, Part III, Schedule B, of Form 1118.
- Form 1120-IC-DISC (Schedule J): needed for line 4a(1), which uses line 8, Part I, Schedule J, if you are an IC-DISC shareholder.
- Schedule B (Form 1120-FSC): needed for line 5a(1), which adds columns (a) and (b) of line 10, if you complete line 5a.
- Form 8873: needed for line 6a, which takes the amount from line 49, if you answered "Yes" to line 7j of Form 5713.
How to fill out Schedule C (Form 5713)
Enter your name and identifying number
At the top of page 1, enter your name and your identifying number as they appear on Form 5713.
Check the method on line 1
Check one: line 1a for the international boycott factor from Schedule A (Form 5713), or line 1b for specifically attributable taxes and income from Schedule B (Form 5713). Your choice decides whether you complete the "a" or the "b" part of lines 2 through 5.
Compute the foreign tax credit reduction
Line 2a, if you checked 1a and answered "Yes" on line 7d of Form 5713: enter the credit before adjustment on 2a(1), the factor on 2a(2), multiply for 2a(3) and subtract for 2a(4). Line 2b, if you checked 1b: enter the amount from line o, column (4), Schedule B.
Compute the denial of subpart F deferral
Line 3a, if you checked 1a and answered "Yes" on line 7b: enter lines 3a(1) and 3a(2), subtract for 3a(3), then multiply by the factor on 3a(4) to get 3a(5). Line 3b: enter column (5) from line o of Schedule B. Enter the result on line 22 of Worksheet A in the Form 5471 instructions.
Compute the denial of IC-DISC benefits
Line 4a, if you checked 1a and answered "Yes" on line 7c: enter your pro rata share on 4a(1), the factor on 4a(2) and multiply for 4a(3). Line 4b: enter column (6) from line o of Schedule B. The IC-DISC includes the result on line 10, Part I, Schedule J, Form 1120-IC-DISC.
Compute the denial of foreign trade income exemption
Line 5a, if you checked 1a and answered "Yes" on line 7i: add columns (a) and (b) of line 10, Schedule B (Form 1120-FSC) on 5a(1), enter the factor on 5a(2) and multiply for 5a(3). Line 5b: enter column (7) from line o of Schedule B. Enter the result on line 2, Schedule F, Form 1120-FSC.
Reduce qualifying foreign trade income
Line 6, on page 2, if you answered "Yes" on line 7j of Form 5713: enter the amount from line 49 of Form 8873 on 6a and the factor from Schedule A, line 3, on 6b. Multiply 6a by 6b for 6c and enter it on Form 8873, line 50.
Carry amounts to the related forms
Enter the foreign tax credit reduction on Form 1116 (line 32, Part IV) or Form 1118 (line 8, Part III, Schedule B), and the line 2b amount on Form 1116 (line 12, Part III) or Form 1118 (line C, Schedule G).
Review, download and attach
Check each line against your Schedule A or B and Form 5713, then download or print the completed PDF from FillingPDF and attach it to Form 5713.
How to submit Schedule C (Form 5713)
Schedule C (Form 5713) is submitted as an attachment to Form 5713. The form prints no mailing address, portal or appointment rule of its own.
- Attach it to Form 5713: the form states "Attach to Form 5713," so the completed schedule goes with that form and follows the way you submit Form 5713.
- Check the instructions: the form refers you to the Instructions for Form 5713 and to www.irs.gov/forms-pubs/about-schedule-c-form-5713 for the latest information, including legislation enacted after the instructions were published.
- Carry the results forward: the amounts computed on lines 2 through 6 are also entered on the other forms named on those lines, such as Form 1116 or 1118, Form 1120-IC-DISC, Form 1120-FSC or Form 8873.
FillingPDF lets you fill out and download the PDF; submission follows the IRS channels that apply to Form 5713.
Common mistakes to avoid
- Filing Schedule C (Form 5713) on its own instead of attaching it to Form 5713.
- Filing it as a partnership; partnerships do not complete Schedule C (Form 5713), and each partner completes a separate one.
- Checking both boxes on line 1 when the form says to check one method.
- Completing lines 2a through 5a after checking box 1b, or lines 2b through 5b after checking box 1a; each part applies only to the method you checked.
- Switching methods within a tax year; a person using one method must use it for all that tax year's operations under sections 908(a), 952(a)(3), 995(b)(1)(F)(ii) or 927(e)(2).
- Entering the foreign tax credit reduction from line 2a(3) on the wrong line: Form 1116 uses line 32, Part IV, and Form 1118 uses line 8, Part III, Schedule B.
- Omitting the 16/17 multiplier on line 4a(1) when the shareholder is a C corporation.
- Not entering the line 3a(5) or 3b amount on line 22 of Worksheet A in the Form 5471 instructions.
Frequently asked questions
What is Schedule C (Form 5713)?
Schedule C (Form 5713) is the IRS schedule that computes the loss of tax benefits attributable to participation in or cooperation with an international boycott. It is attached to Form 5713 and covers the foreign tax credit, subpart F deferral, IC-DISC benefits and foreign trade income.
Who has to complete Schedule C (Form 5713)?
Anyone who completed Schedule A or Schedule B of Form 5713. Partnerships do not complete it; each partner completes a separate Schedule C (Form 5713). Members of a controlled group may each choose a method unless the group files a consolidated return.
Do I complete the "a" lines or the "b" lines?
It depends on line 1. Check box 1a to use the international boycott factor from Schedule A, and complete the "a" lines. Check box 1b to use specifically attributable taxes and income from Schedule B, and complete the "b" lines. You also need a "Yes" answer on the matching line 7 question of Form 5713.
Can I use different methods for different operations?
No. A person who applies the international boycott factor to one operation must apply it to all of that tax year's operations under sections 908(a), 952(a)(3), 995(b)(1)(F)(ii) or 927(e)(2). A person who identifies specifically attributable taxes and income must likewise use that method for all of them.
Where do I send Schedule C (Form 5713)?
Attach it to Form 5713 and submit it the way you submit that form. The schedule prints no address or portal of its own. Use the Instructions for Form 5713 and www.irs.gov/forms-pubs/about-schedule-c-form-5713 for the latest information.
Where does the line 2a(3) reduction go?
Enter the reduction of foreign tax credit on Form 1116 or Form 1118. On Form 1116 it goes on line 32, Part IV. On Form 1118 it goes on line 8, Part III, Schedule B.
Can I fill out Schedule C (Form 5713) online?
Yes. You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the form with the IRS; you submit it with Form 5713 through the IRS channels.
Ready to fill out Schedule C (Form 5713)?
Fill out Schedule C (Form 5713) now