
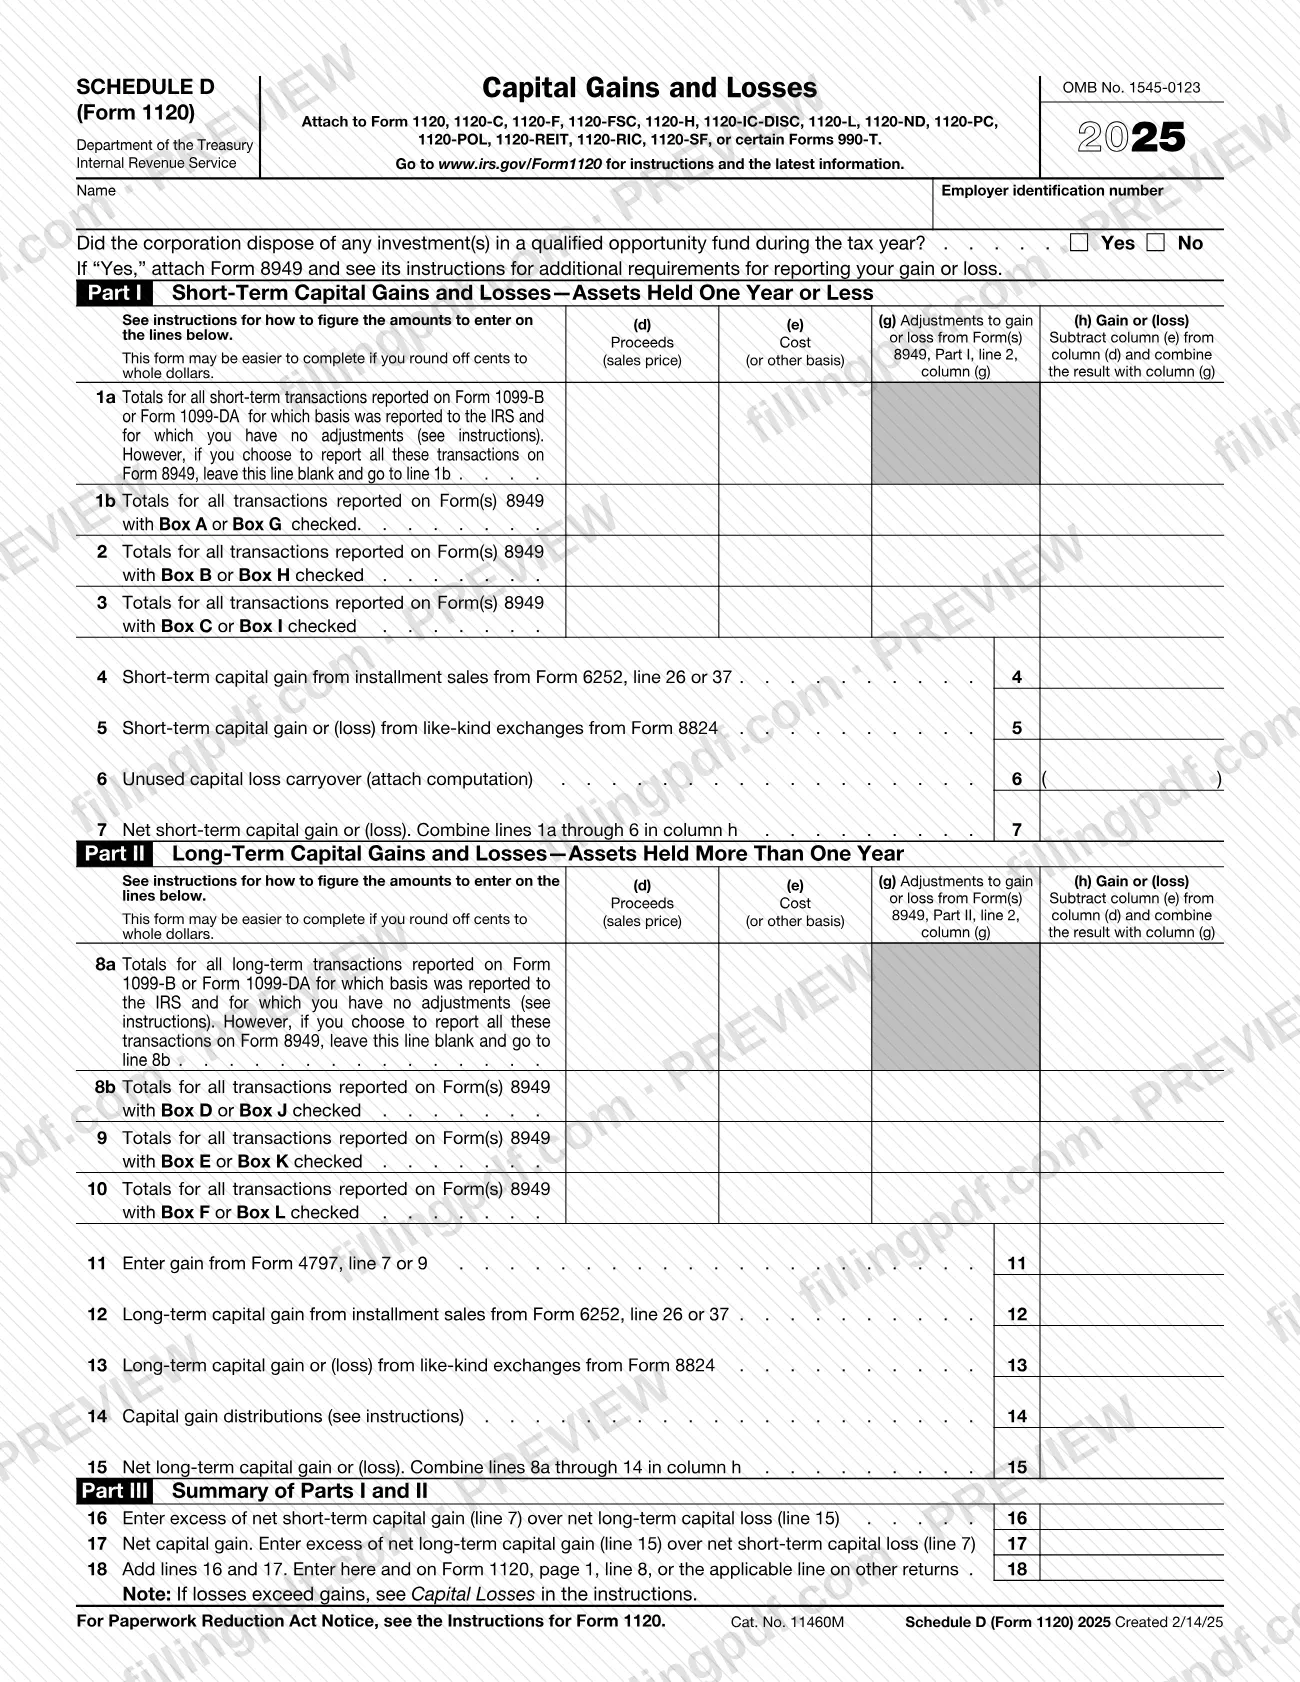
Schedule D (Form 1120), Capital Gains and Losses, is the Internal Revenue Service (IRS) schedule on which a corporation reports its short-term and long-term capital gains and losses and works out its net capital gain. It is attached to Form 1120 or to one of the related corporate returns the form lists, and it is the corporate schedule, not the one filed with an individual return. On FillingPDF you can fill out the 2025 form online and download or print the completed PDF; the IRS publishes the original PDF and the instructions at www.irs.gov/Form1120.
Last updated
What is Schedule D (Form 1120)?
Schedule D (Form 1120), Capital Gains and Losses, is the IRS schedule that a corporation attaches to its return to report gain or loss from transactions on Form 8949, plus certain transactions it does not have to report on Form 8949.
The IRS instructions say the schedule is used for several kinds of amounts:
- the overall gain or loss from transactions reported on Form 8949;
- certain transactions the corporation does not have to report on Form 8949 (lines 1a and 8a);
- gain from Form 6252, Installment Sale Income, or from Part I of Form 4797, Sales of Business Property;
- gain or loss from Form 8824, Like-Kind Exchanges;
- an unused capital loss carryover;
- capital gain distributions not reported directly on Form 1120, line 8.
The form has three parts. Part I covers short-term gains and losses on assets held one year or less. Part II covers long-term gains and losses on assets held more than one year. Part III summarizes both and produces the net capital gain, which is carried to Form 1120, page 1, line 8, or the applicable line on other returns.
The schedule is not the place for everything. Form 4797 is used for the sale of business property such as real property used in a trade or business, Form 4684 for casualties and thefts, and Form 6781 for section 1256 contracts and straddles. For 2025, new codes G, H, I, J, K and L were added to lines 1b, 2, 3, 8b, 9 and 10 so that digital asset transactions can be reported. The form carries OMB No. 1545-0123.
Who needs to file Schedule D (Form 1120)?
Corporations that file Form 1120, 1120-C, 1120-F, 1120-FSC, 1120-H, 1120-IC-DISC, 1120-L, 1120-ND, 1120-PC, 1120-POL, 1120-REIT, 1120-RIC or 1120-SF, or certain Forms 990-T, complete and attach Schedule D (Form 1120) when they have capital gains or losses to report. The form's heading and the IRS instructions list exactly these returns.
Typical situations covered by the instructions include:
- a corporation that sold or exchanged capital assets, which it first reports on Form 8949 unless lines 1a or 8a apply;
- a corporation with an unused capital loss carryover, which goes on line 6;
- a RIC or REIT shareholder that received capital gain distributions, which go on line 14;
- a corporation that disposed of any investment in a qualified opportunity fund (QOF) during the tax year, which checks Yes in the box at the top of the form.
Do not use Schedule D for items that belong on other forms. Sales of business property go on Form 4797, casualty and theft losses on Form 4684, and section 1256 contracts and straddles on Form 6781, as the instructions explain. The form does not describe any individual filer or any representative who signs it; it is attached to the corporation's return.
When to file Schedule D (Form 1120)
Schedule D (Form 1120) is completed when the corporation files the return it is attached to, so it has no separate due date of its own. Use it for the tax year in which the corporation sold, exchanged or otherwise disposed of capital assets, received capital gain distributions, or has an unused capital loss carryover. The form printed here is the 2025 edition.
Complete all applicable lines of Form 8949 first, because lines 1b, 2, 3, 8b, 9 and 10 take their totals from it. The instructions give one timing rule for an election: to elect out of the installment method, report the full gain on Form 8949 for the year of the sale on a return filed by the due date, including extensions. If the original return was filed on time without the election, it may be made on an amended return filed no later than 6 months after the original due date, excluding extensions.
Documents you need
- Form 8949, Sales and Other Dispositions of Capital Assets: complete it before lines 1b, 2, 3, 8b, 9 or 10, and attach it if you check Yes on the qualified opportunity fund question.
- A statement showing how the unused capital loss carryover on line 6 was computed.
- An explanation of the basis used, if the corporation uses a basis other than the actual cost of the property (see the Instructions for Form 8949, column (e)).
- Form 8997, Initial and Annual Statement of Qualified Opportunity Fund (QOF) Investments: attach it annually until the QOF investment is disposed of, if the corporation deferred gain by investing in a QOF.
- Form 6198, At-Risk Limitations: attach it if a capital asset was sold or exchanged in an at-risk activity and combining the gain or loss with the activity's profit or loss gives a net loss.
- Form 6252, Form 4797 or Form 8824: the figures for lines 4 and 12, line 11, and lines 5 and 13 come from these forms, when the corporation had installment sales, business property gains or like-kind exchanges.
How to fill out Schedule D (Form 1120)
Enter the corporation's name and EIN
At the top, write the corporation's name and employer identification number exactly as they appear on the return the schedule is attached to.
Answer the qualified opportunity fund question
Check Yes or No to whether the corporation disposed of any investment in a qualified opportunity fund during the tax year. If Yes, attach Form 8949 and follow its instructions.
Complete Form 8949 first
Finish every applicable page of Form 8949 before you fill in lines 1b, 2, 3, 8b, 9 and 10, because those lines are totals taken from it.
Report short-term transactions on lines 1a to 3
Part I lines 1a, 1b, 2 and 3 hold proceeds in column (d), cost or other basis in column (e), adjustments in column (g) and the gain or (loss) in column (h). Use line 1a only for transactions that meet the instructions; lines 1b, 2 and 3 take the Form 8949, Part I totals for boxes A or G, B or H, and C or I.
Add other short-term items on lines 4 to 6
Line 4: short-term gain from installment sales from Form 6252, line 26 or 37. Line 5: short-term gain or (loss) from like-kind exchanges from Form 8824. Line 6: any unused capital loss carryover, in parentheses, with the computation attached.
Figure net short-term gain on line 7
Combine lines 1a through 6 in column (h) to get the net short-term capital gain or (loss).
Report long-term transactions on lines 8a to 10
Part II works like Part I. Use line 8a only for transactions that meet the instructions; lines 8b, 9 and 10 take the Form 8949, Part II totals for boxes D or J, E or K, and F or L.
Add other long-term items on lines 11 to 14
Line 11: gain from Form 4797, line 7 or 9. Line 12: long-term gain from installment sales from Form 6252. Line 13: long-term gain or (loss) from like-kind exchanges from Form 8824. Line 14: capital gain distributions, as the instructions describe.
Figure net long-term gain on line 15
Combine lines 8a through 14 in column (h) to get the net long-term capital gain or (loss).
Complete the Part III summary
Line 16: excess of net short-term gain (line 7) over net long-term loss (line 15). Line 17: excess of net long-term gain (line 15) over net short-term loss (line 7). Line 18: add lines 16 and 17.
Carry line 18 to the return
Enter the line 18 result on Form 1120, page 1, line 8, or on the applicable line of the other return. If losses exceed gains, see Capital Losses in the instructions.
Review, download and attach
Check that all amounts use whole dollars or cents consistently and that losses are in parentheses. Download or print the completed PDF from FillingPDF and attach it, with Form 8949 and any statements, to your return.
How to submit Schedule D (Form 1120)
Schedule D (Form 1120) is not filed on its own. You attach it to the corporate return it supports, and it is submitted by whichever method that return uses.
- Attach to the return: the schedule goes with Form 1120, 1120-C, 1120-F, 1120-FSC, 1120-H, 1120-IC-DISC, 1120-L, 1120-ND, 1120-PC, 1120-POL, 1120-REIT, 1120-RIC, 1120-SF or certain Forms 990-T.
- Supporting attachments: include Form 8949 when the form requires it, a statement showing how any line 6 carryover was computed, and any other form your situation calls for (see the list of documents on this page).
- Where and how to file: the schedule prints no mailing address, portal or appointment rule. Follow the instructions for the parent return, and find the latest information at www.irs.gov/Form1120.
FillingPDF lets you fill out and download the PDF; submission follows the IRS channels that apply to your return.
Common mistakes to avoid
- Reporting a transaction on line 1a or 8a when the Form 1099-B or 1099-DA does not show basis reported to the IRS, or when basis needs correcting; the instructions say to use Form 8949 instead.
- Completing lines 1b, 2, 3, 8b, 9 or 10 before finishing every applicable page of Form 8949, which supplies their totals.
- Leaving the qualified opportunity fund question unanswered, or checking No after disposing of a QOF investment; a Yes answer also needs Form 8949.
- Entering a line 6 carryover without attaching the statement that shows how it was computed.
- Reporting sales of business property or casualty and theft losses on Schedule D instead of Form 4797 or Form 4684.
- Deducting a wash sale loss on stock or securities; the instructions bar it unless the corporation is a dealer and the loss arose in the ordinary course of business.
- Mixing whole dollars and cents; the corporation must either round all amounts on its return to whole dollars or use cents for all amounts.
- Leaving a loss out of parentheses; negative amounts in column (h) must be entered in parentheses.
Frequently asked questions
What is Schedule D (Form 1120)?
Schedule D (Form 1120), Capital Gains and Losses, is the IRS schedule a corporation attaches to its return to report the overall gain or loss from Form 8949 transactions and certain other items. Part III produces the net capital gain carried to Form 1120, page 1, line 8.
Which returns does Schedule D (Form 1120) attach to?
Form 1120, 1120-C, 1120-F, 1120-FSC, 1120-H, 1120-IC-DISC, 1120-L, 1120-ND, 1120-PC, 1120-POL, 1120-REIT, 1120-RIC, 1120-SF or certain Forms 990-T. The form heading and the IRS instructions list these returns.
Do I need Form 8949 with Schedule D (Form 1120)?
Usually yes. Lines 1b, 2, 3, 8b, 9 and 10 take totals from Form 8949, so complete it first. Only transactions that meet the instructions for line 1a or 8a, such as basis reported to the IRS with no adjustments, can skip Form 8949.
When can I use line 1a or line 8a?
For aggregate totals from Forms 1099-B or 1099-DA where basis was reported to the IRS and no adjustments are needed. The Ordinary and QOF checkboxes must not be checked, and sales of collectibles are excluded. If you choose to report these on Form 8949, leave the line blank.
What happens if my corporation has a net capital loss?
A corporation's capital losses are allowed in the current year only to the extent of capital gains. A net capital loss is carried back 3 years and forward up to 5 years as a short-term capital loss. Foreign expropriation capital losses are only carried forward, up to 10 years.
Where do I send Schedule D (Form 1120)?
You do not send it separately. Attach it to the corporate return it supports and file that return as its own instructions direct. The schedule prints no address of its own; instructions are at www.irs.gov/Form1120.
Where does the line 18 result go?
Enter the sum of lines 16 and 17 on Form 1120, page 1, line 8, or on the applicable line of the other return you are filing. If losses exceed gains, the form refers you to Capital Losses in the instructions.
Can I fill out Schedule D (Form 1120) online?
Yes. You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the schedule with the IRS; it goes in with your corporate return through the IRS channels.
Ready to fill out Schedule D (Form 1120)?
Fill out Schedule D (Form 1120) now