
Schedule E (Form 5471), Income, War Profits, and Excess Profits Taxes Paid or Accrued, is an Internal Revenue Service (IRS) schedule that the person filing Form 5471 attaches to it for a foreign corporation. It lists the foreign income taxes the corporation paid, accrued or is deemed to have paid, the taxes for which a foreign tax credit is disallowed, and the balances carried in Schedule E-1. On this page you can fill out the form online on FillingPDF and download or print the completed PDF; the IRS publishes the form and its instructions at www.irs.gov/Form5471.
Last updated
What is Schedule E (Form 5471)?
Schedule E (Form 5471), Income, War Profits, and Excess Profits Taxes Paid or Accrued, is the IRS schedule attached to Form 5471 that reports a foreign corporation's taxes paid, accrued or deemed paid, and tracks them in a running balance by category of income.
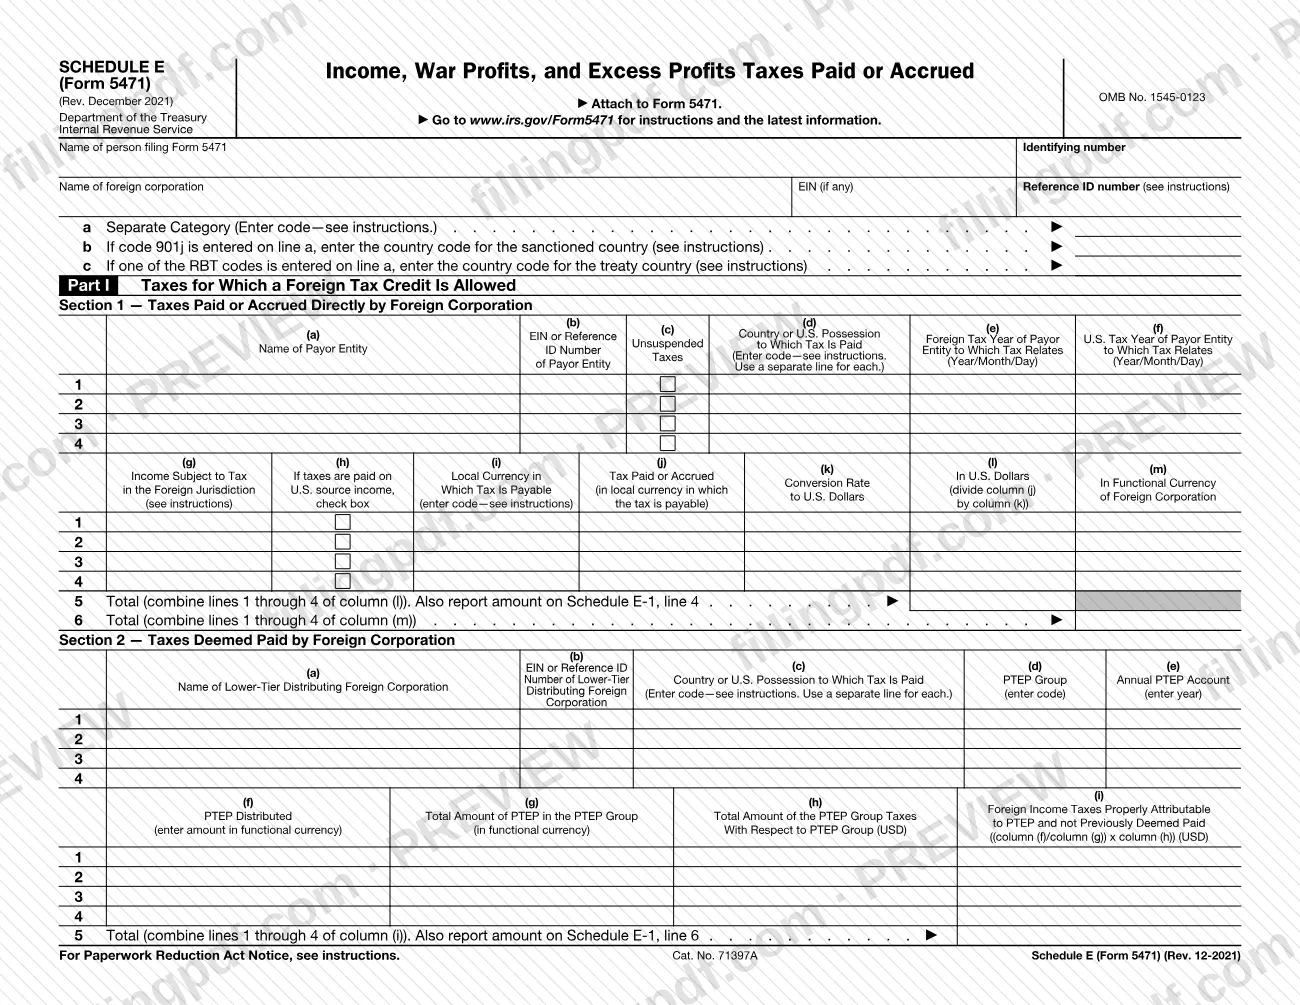
The form is issued under OMB No. 1545-0123 and is dated Rev. December 2021. It is not filed on its own: it says to attach it to Form 5471. It has three pages and these blocks:
- Part I, Taxes for Which a Foreign Tax Credit Is Allowed. Section 1 covers taxes paid or accrued directly by the foreign corporation, with local-currency amounts converted to U.S. dollars. Section 2 covers taxes deemed paid, based on previously taxed earnings and profits (PTEP) distributed by lower-tier foreign corporations.
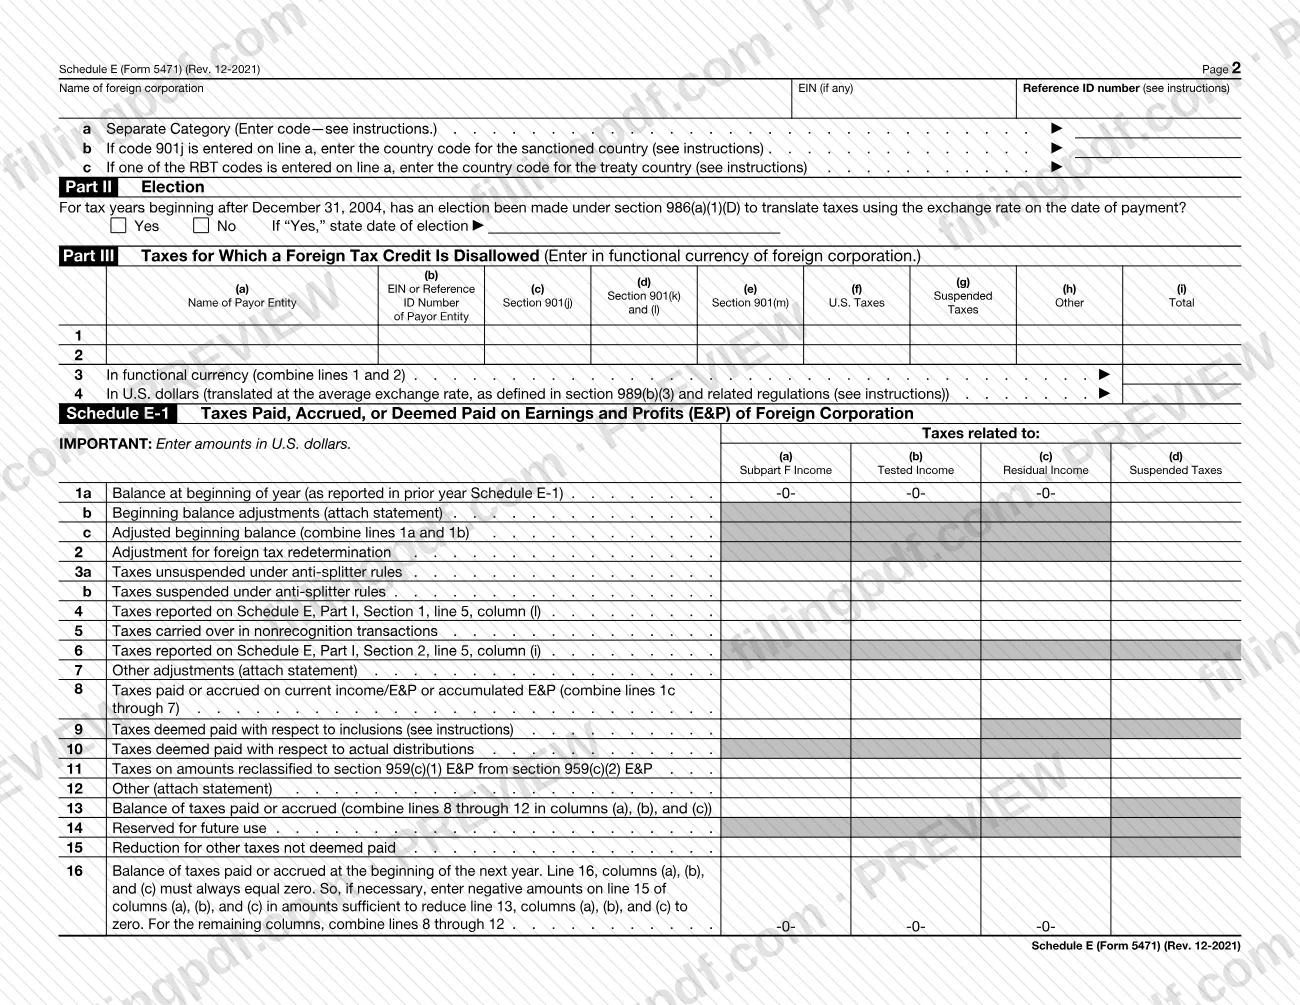
- Part II, Election. One question on whether an election under section 986(a)(1)(D) was made to translate taxes at the exchange rate on the date of payment.
- Part III, Taxes for Which a Foreign Tax Credit Is Disallowed. Taxes under sections 901(j), 901(k) and (l), 901(m), U.S. taxes and other taxes, entered in the corporation's functional currency.
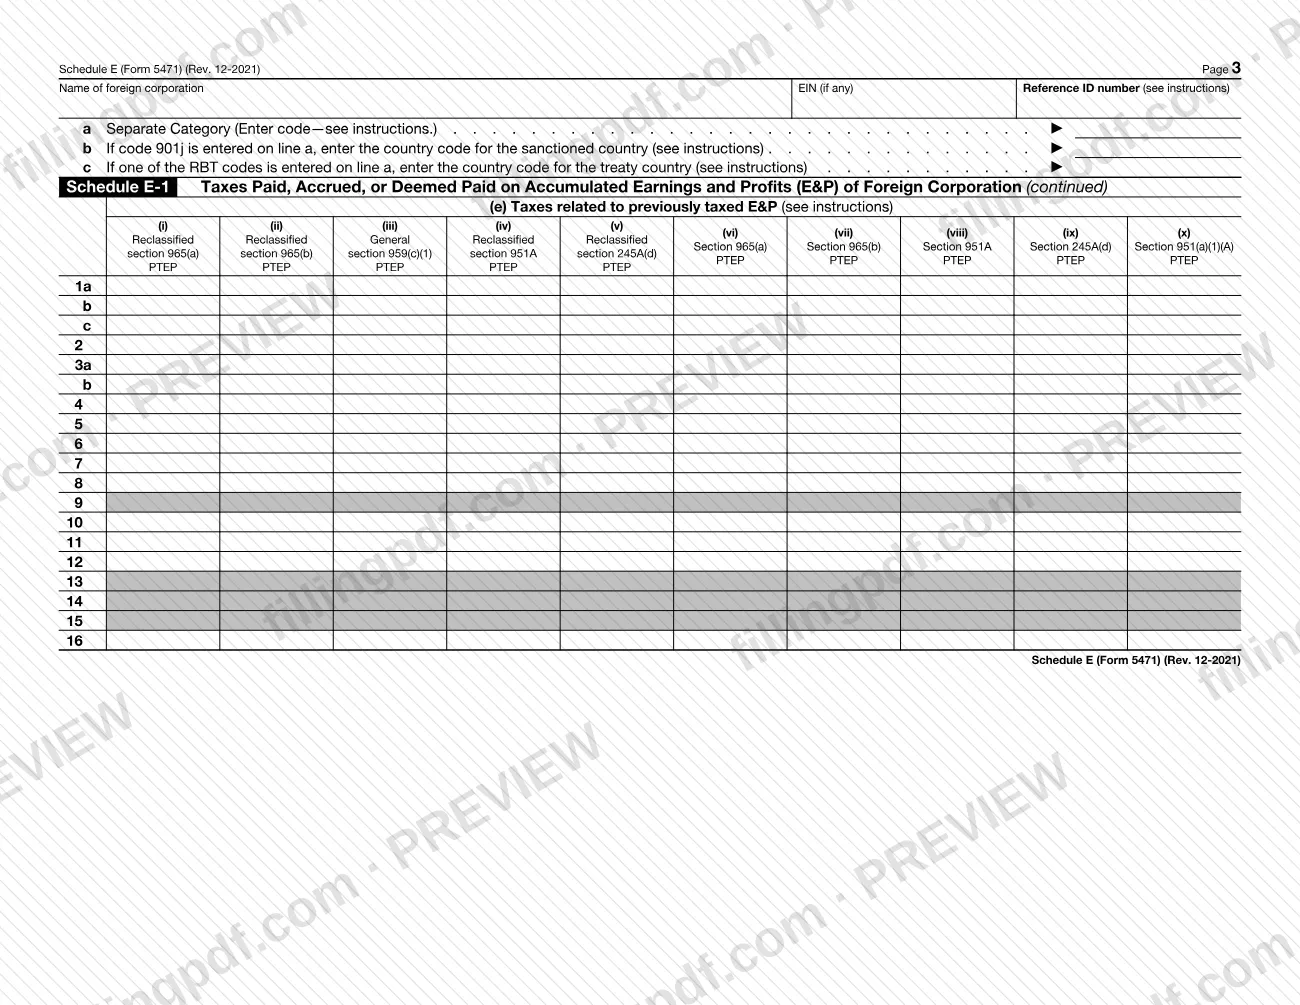
- Schedule E-1. A roll-forward, in U.S. dollars, of taxes paid, accrued or deemed paid on earnings and profits (E&P), split into Subpart F income, tested income, residual income and suspended taxes, with a further breakdown for PTEP on page 3.
The totals of Part I, Section 1 (line 5, column (l)) and Section 2 (line 5, column (i)) feed lines 4 and 6 of Schedule E-1.
Who needs to file Schedule E (Form 5471)?
The person filing Form 5471 completes Schedule E (Form 5471) and attaches it to that form. The first line of the schedule asks for the name of the person filing Form 5471 and an identifying number, followed by the name of the foreign corporation, its EIN (if any) and a reference ID number.
The schedule applies to the foreign corporation named at the top of each page. The same corporation and separate category entries repeat on pages 2 and 3, so every page of a completed schedule belongs to one foreign corporation.
Whether a particular filer must file Form 5471, and which schedules go with it, is decided by the Form 5471 instructions at www.irs.gov/Form5471; the schedule itself does not list the persons who must file it.
When to file Schedule E (Form 5471)
Schedule E (Form 5471) is completed when you complete Form 5471, because the form says to attach it to Form 5471. No separate due date is printed on it, so it travels with Form 5471 whenever that form is filed. For the due date and any extension that applies to Form 5471, see the IRS instructions at www.irs.gov/Form5471.
Schedule E-1, line 1a asks for the balance at the beginning of the year as reported in the prior year's Schedule E-1, so keep last year's schedule at hand before you start.
Documents you need
- A statement attached for any beginning balance adjustments reported on Schedule E-1, line 1b.
- A statement attached for any other adjustments reported on Schedule E-1, line 7.
- A statement attached for any other amounts reported on Schedule E-1, line 12.
How to fill out Schedule E (Form 5471)
Enter filer and corporation details
At the top, enter the name of the person filing Form 5471 and the identifying number, then the name of the foreign corporation, its EIN (if any) and the reference ID number (see instructions).
Enter the separate category code
Line a: the separate category code. Line b: the sanctioned country code, only if you entered code 901j on line a. Line c: the treaty country code, only if you entered one of the RBT codes on line a.
Identify payors in Part I, Section 1
For each of lines 1 to 4, enter in columns (a) to (f) the payor entity name, its EIN or reference ID number, the country or U.S. possession to which tax is paid, the unsuspended taxes code, and the foreign and U.S. tax years of the payor entity in Year/Month/Day format.
Enter income, taxes and conversion
Columns (g) to (m): income subject to tax in the foreign jurisdiction, a check box if taxes are paid on U.S. source income, the local currency, tax paid or accrued in local currency, the conversion rate, and the amounts in U.S. dollars and in functional currency.
Total Section 1
Line 5: combine lines 1 to 4 of column (l), and report the amount on Schedule E-1, line 4. Line 6: combine lines 1 to 4 of column (m).
Complete Section 2, taxes deemed paid
For each lower-tier distributing foreign corporation enter its name, EIN or reference ID number, country code, PTEP group code and annual PTEP account year in columns (a) to (e). Then enter columns (f) to (i); line 5 totals column (i) and goes to Schedule E-1, line 6.
Answer the Part II election
Check Yes or No for whether an election under section 986(a)(1)(D) was made to translate taxes at the exchange rate on the date of payment. If Yes, enter the date of election.
Report disallowed taxes in Part III
On lines 1 and 2, enter each payor entity, its EIN or reference ID number and the amounts for sections 901(j), 901(k) and (l), 901(m), U.S. taxes, other taxes and the total, in functional currency. Line 3 combines lines 1 and 2; line 4 translates to U.S. dollars at the average exchange rate.
Roll forward Schedule E-1, lines 1a to 8
In U.S. dollars, enter the beginning balance, adjustments, redetermination, anti-splitter amounts and the Schedule E amounts on lines 4 and 6 in columns (a) to (d). Line 8 combines lines 1c through 7. Attach statements for lines 1b and 7.
Complete Schedule E-1, lines 9 to 16
Enter taxes deemed paid on inclusions and distributions, reclassified amounts and other items on lines 9 to 12, then the balance on line 13. Use line 15 to reduce columns (a), (b) and (c) so line 16 equals zero.
Complete the PTEP columns on page 3
Repeat the foreign corporation and separate category entries, then enter the amounts in columns (e)(i) to (e)(x), the taxes related to previously taxed E&P, on the Schedule E-1 lines.
Review and download the PDF
Check that every page shows the same foreign corporation and category and that the Schedule E-1 totals tie to Part I. Download or print the completed PDF from FillingPDF and attach it to Form 5471.
How to submit Schedule E (Form 5471)
Schedule E (Form 5471) is submitted as an attachment to Form 5471; it has no separate filing channel, address or portal printed on it.
- With Form 5471: attach the completed schedule to Form 5471 and send both the way Form 5471 is filed.
- Instructions: the form directs you to www.irs.gov/Form5471 for instructions and the latest information, including where Form 5471 goes.
- Statements: if you use lines 1b, 7 or 12 of Schedule E-1, attach the statement those lines call for.
FillingPDF lets you fill out and download the PDF; submission follows the IRS channels that apply to Form 5471.
Common mistakes to avoid
- Filing Schedule E (Form 5471) without attaching it to Form 5471; the form states it is to be attached to Form 5471.
- Entering Schedule E-1 amounts in functional currency; the form says to enter amounts in U.S. dollars.
- Leaving Schedule E-1, line 16, columns (a), (b) and (c) at an amount other than zero; the form says they must always equal zero, using negative amounts on line 15 if necessary.
- Entering foreign tax amounts in U.S. dollars in Part III, which the form says to enter in the foreign corporation's functional currency.
- Not carrying the Part I, Section 1, line 5 total to Schedule E-1, line 4, or the Section 2, line 5 total to Schedule E-1, line 6.
- Combining several countries or possessions on one line in Part I when the form says to use a separate line for each.
- Entering a country code on line b or c without the matching code on line a (901j for line b, an RBT code for line c).
- Entering an amount on Schedule E-1, line 14, which is marked Reserved for future use.
- Attaching adjustments on lines 1b, 7 or 12 of Schedule E-1 without the statement the form calls for.
Frequently asked questions
What is Schedule E (Form 5471)?
Schedule E (Form 5471), Income, War Profits, and Excess Profits Taxes Paid or Accrued, is the IRS schedule attached to Form 5471. It reports the taxes a foreign corporation paid, accrued or deemed paid, the taxes for which a foreign tax credit is disallowed, and the Schedule E-1 balances.
Is Schedule E (Form 5471) filed by itself?
No. The form says to attach it to Form 5471, so it is submitted with that form. It has no separate address, portal or due date printed on it.
Where do I find the instructions for Schedule E (Form 5471)?
The IRS publishes instructions and the latest information at www.irs.gov/Form5471, the address printed on the form. Several entries, such as the separate category codes and the reference ID number, are marked as explained in those instructions.
What is Schedule E-1 on this form?
Schedule E-1 is the part of the form, on pages 2 and 3, that reports taxes paid, accrued or deemed paid on earnings and profits of the foreign corporation. Amounts go in U.S. dollars, and Part I totals feed its lines 4 and 6.
What must Schedule E-1, line 16 equal?
For columns (a), (b) and (c), line 16 must always equal zero. If necessary, enter negative amounts on line 15 in those columns that are large enough to reduce line 13 to zero. For the remaining columns, combine lines 8 through 12.
Do I enter amounts in U.S. dollars or foreign currency?
It depends on the part. Schedule E-1 is in U.S. dollars. Part III is entered in the foreign corporation's functional currency, with line 4 translated to dollars. Part I, Section 1 shows local currency, functional currency and U.S. dollar columns.
Can I fill out Schedule E (Form 5471) online?
Yes. You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the schedule with the IRS; you submit it with Form 5471.
What is the difference between Schedule E and Schedule E-1 of Form 5471?
Schedule E (Part I to III) lists the individual taxes: those paid directly, deemed paid, and disallowed. Schedule E-1 then rolls those taxes into a balance by category of income, using the Schedule E totals on its lines 4 and 6.
Ready to fill out Schedule E (Form 5471)?
Fill out Schedule E (Form 5471) now