
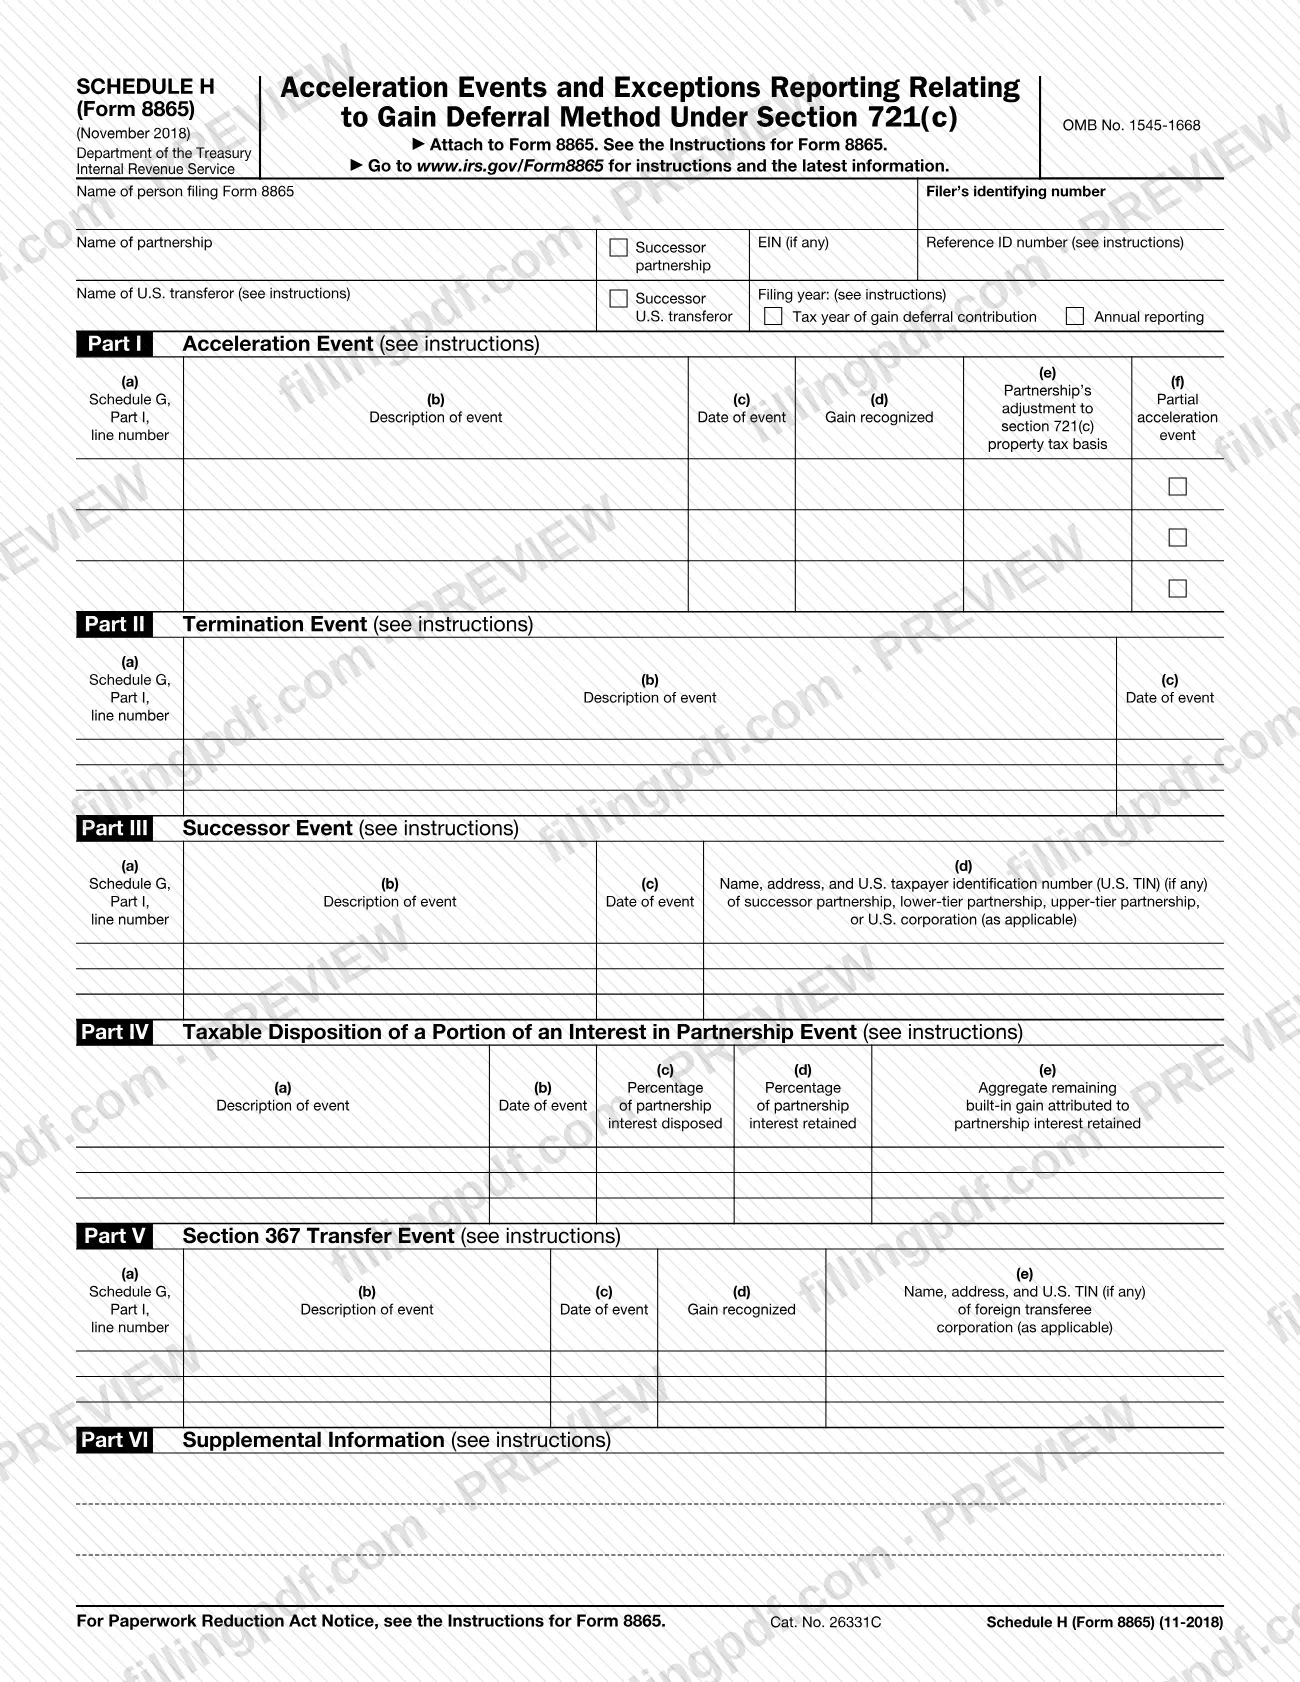
Schedule H (Form 8865), Acceleration Events and Exceptions Reporting Relating to Gain Deferral Method Under Section 721(c), is an Internal Revenue Service (IRS) schedule that you attach to Form 8865. It is used to report acceleration, termination, successor, partial-disposition and section 367 transfer events tied to the section 721(c) gain deferral method. On FillingPDF you can fill out the schedule online and download or print the completed PDF. The form and its instructions are published by the IRS at www.irs.gov/Form8865.
Last updated
What is Schedule H (Form 8865)?
Schedule H (Form 8865), Acceleration Events and Exceptions Reporting Relating to Gain Deferral Method Under Section 721(c), is the Internal Revenue Service (IRS) schedule attached to Form 8865 to report events that affect a partnership's use of the section 721(c) gain deferral method.
The schedule is divided into six parts:
- Part I, Acceleration Event: description, date, gain recognized, the partnership's adjustment to section 721(c) property tax basis, and whether the event is a partial acceleration event.
- Part II, Termination Event: description and date of the event.
- Part III, Successor Event: description, date, and the name, address and U.S. taxpayer identification number (U.S. TIN) of the successor partnership, lower-tier partnership, upper-tier partnership or U.S. corporation, as applicable.
- Part IV, Taxable Disposition of a Portion of an Interest in Partnership Event: the percentage of the partnership interest disposed of and retained, and the aggregate remaining built-in gain attributed to the interest retained.
- Part V, Section 367 Transfer Event: description, date, gain recognized, and the name, address and U.S. TIN of the foreign transferee corporation, as applicable.
- Part VI, Supplemental Information.
Most parts ask for the Schedule G, Part I, line number to which the event relates. The header identifies the person filing Form 8865, the partnership, the U.S. transferor, any successor EIN, a reference ID number and the filing year. The form prints OMB No. 1545-1668. It is a schedule of Form 8865, not a separate return, and the IRS instructions for Form 8865 explain each part.
Who needs to file Schedule H (Form 8865)?
Schedule H (Form 8865) is completed by the person filing Form 8865 who has events to report under the section 721(c) gain deferral method. The header asks for the name and identifying number of the person filing Form 8865, the name of the partnership and the name of the U.S. transferor.
The form has boxes for two special cases in the header: a successor partnership and a successor U.S. transferor. It also asks whether the filing year is the tax year of the gain deferral contribution or an annual reporting year.
The schedule is not filed alone; it states "Attach to Form 8865." The form itself does not say which filers must complete it or when a part applies, so check the Instructions for Form 8865 at www.irs.gov/Form8865 to confirm whether your situation calls for it and which of Parts I through VI you must complete.
When to file Schedule H (Form 8865)
Schedule H (Form 8865) travels with Form 8865: the form says to attach it to Form 8865, so it is filed whenever that form is filed. No separate due date is printed on the schedule.
The header asks you to identify the filing year, choosing between the tax year of the gain deferral contribution and annual reporting. Event dates are entered in Parts I through V for each event you report. For the deadline that applies to Form 8865 and for the rules on which events must be reported in which year, see the Instructions for Form 8865 at www.irs.gov/Form8865.
How to fill out Schedule H (Form 8865)
Identify the filer and partnership
At the top, enter the name of the person filing Form 8865 and the filer's identifying number. Then enter the name of the partnership, its successor EIN (if any) and the reference ID number, following the instructions for that box.
Enter the U.S. transferor
Enter the name of the U.S. transferor as the Instructions for Form 8865 direct. Check the box for successor partnership or successor U.S. transferor if it applies.
Choose the filing year
Mark the filing year: either the tax year of the gain deferral contribution or annual reporting. See the instructions for what each choice covers.
Report acceleration events in Part I
For each event, enter the Schedule G, Part I, line number in column (a), a description in (b), the date in (c) and the gain recognized in (d). Enter the partnership's adjustment to section 721(c) property tax basis in (e) and complete (f) for a partial acceleration event.
Report termination events in Part II
Enter the Schedule G, Part I, line number in column (a), the description of the event in (b) and its date in (c).
Report successor events in Part III
Complete columns (a) through (c) as in Part II, then in (d) give the name, address and U.S. TIN (if any) of the successor partnership, lower-tier partnership, upper-tier partnership or U.S. corporation, as applicable.
Report partial interest dispositions in Part IV
Describe the event in (a) and give its date in (b). Enter the percentage of the partnership interest disposed of in (c), the percentage retained in (d), and the aggregate remaining built-in gain attributed to the interest retained in (e).
Report section 367 transfers in Part V
Enter the Schedule G, Part I, line number, the description, the date and the gain recognized in columns (a) through (d). In (e) give the name, address and U.S. TIN (if any) of the foreign transferee corporation, as applicable.
Add supplemental information in Part VI
Use Part VI for any additional information the Instructions for Form 8865 ask you to give for the events reported in Parts I through V.
Review and download the completed PDF
Check that each event appears in the correct part and that the header matches Form 8865. Download or print the completed PDF from FillingPDF and attach it to Form 8865.
How to submit Schedule H (Form 8865)
Schedule H (Form 8865) is submitted as an attachment to Form 8865; the schedule prints no mailing address, portal or appointment rule of its own.
- With Form 8865: attach the completed schedule to Form 8865 and send both together by the channel you use for Form 8865.
- Instructions: the form refers you to the Instructions for Form 8865 and to www.irs.gov/Form8865 for instructions and the latest information.
Check that the header shows the name and identifying number of the person filing Form 8865 before you send the package. FillingPDF lets you fill out and download the PDF; submission follows the IRS channels that apply to Form 8865.
Common mistakes to avoid
- Submitting Schedule H (Form 8865) without attaching it to Form 8865; the schedule states it is to be attached to Form 8865.
- Leaving out the name of the person filing Form 8865 or the filer's identifying number in the header.
- Skipping the filing year choice in the header between the tax year of gain deferral contribution and annual reporting.
- Leaving out the Schedule G, Part I, line number in the parts that ask for it (Parts I, II, III and V).
- Entering the successor partnership, lower-tier partnership, upper-tier partnership or U.S. corporation details in Part III without a name, address and U.S. TIN, if any.
- Reporting a taxable disposition of part of a partnership interest in Part I or Part V instead of Part IV, which asks for the percentages disposed of and retained.
- Omitting the foreign transferee corporation's name, address and U.S. TIN, if any, when reporting a section 367 transfer event in Part V.
Frequently asked questions
What is Schedule H (Form 8865)?
Schedule H (Form 8865) is the IRS schedule titled Acceleration Events and Exceptions Reporting Relating to Gain Deferral Method Under Section 721(c). You attach it to Form 8865 to report acceleration, termination, successor, partial-disposition and section 367 transfer events.
Is Schedule H (Form 8865) filed on its own?
No. The form says to attach it to Form 8865, so it is filed with that form rather than separately. It prints no separate address or due date; the Instructions for Form 8865 govern filing.
What are the parts of Schedule H (Form 8865)?
There are six: Part I Acceleration Event, Part II Termination Event, Part III Successor Event, Part IV Taxable Disposition of a Portion of an Interest in Partnership Event, Part V Section 367 Transfer Event, and Part VI Supplemental Information.
What goes in Part IV of Schedule H (Form 8865)?
Part IV covers a taxable disposition of a portion of a partnership interest. You enter a description and date, the percentage of the partnership interest disposed of, the percentage retained, and the aggregate remaining built-in gain attributed to the interest retained.
Where do I find the instructions for Schedule H (Form 8865)?
The IRS refers you to the Instructions for Form 8865 and to www.irs.gov/Form8865 for instructions and the latest information. The form itself points to those instructions for the header boxes and for each of Parts I through VI.
Can I fill out Schedule H (Form 8865) online?
Yes. You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the schedule with the IRS; you submit it with Form 8865 through the IRS channels.
What revision of Schedule H (Form 8865) is this page based on?
The form prints November 2018 as its revision date, with OMB No. 1545-1668. Check www.irs.gov/Form8865 for the latest information before filing.
Ready to fill out Schedule H (Form 8865)?
Fill out Schedule H (Form 8865) now