
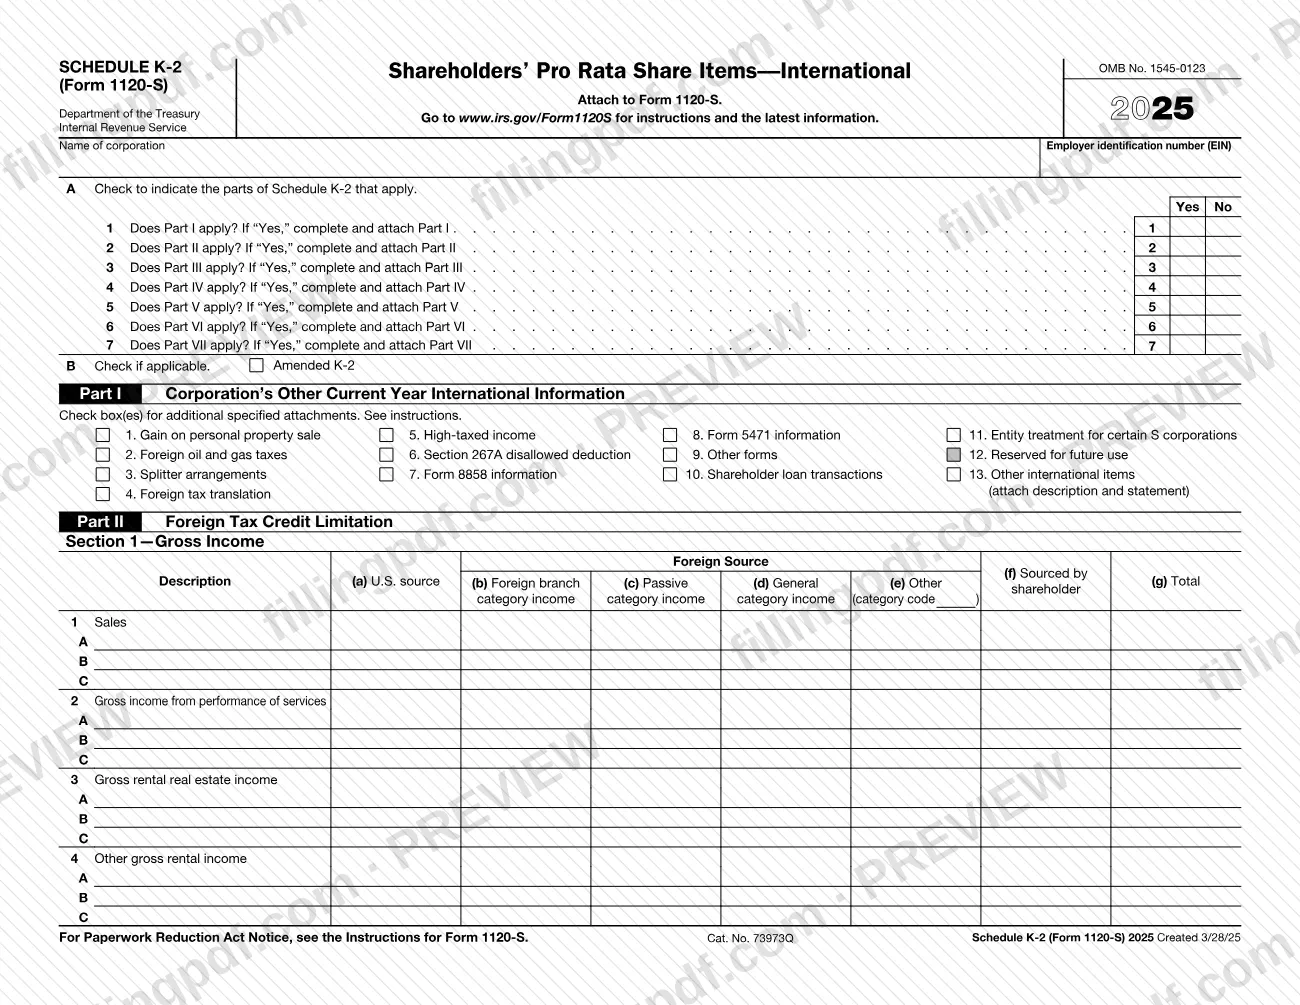
Schedule K-2 (Form 1120-S), Shareholders’ Pro Rata Share Items—International, is an Internal Revenue Service (IRS) schedule that an S corporation attaches to Form 1120-S for the 2025 tax year. It collects international information in seven parts, from foreign tax credit limitation figures to foreign corporation and PFIC data. On this page you can fill out the form online on FillingPDF and download or print the completed PDF; the form and its instructions are published by the IRS at www.irs.gov/Form1120S.
Last updated
What is Schedule K-2 (Form 1120-S)?
Schedule K-2 (Form 1120-S), Shareholders’ Pro Rata Share Items—International, is the Internal Revenue Service (IRS) schedule attached to Form 1120-S on which an S corporation reports international items, including foreign tax credit limitation figures and information on foreign corporations, for the tax year.
The form carries OMB No. 1545-0123 and the 2025 tax year. It opens with the corporation's name and employer identification number (EIN), then a Yes/No table on lines 1 to 7 of item A that tells you which of its seven parts apply. Item B is a box to check if the schedule is an amended K-2.
The parts are:
- Part I, Corporation’s Other Current Year International Information, with check boxes for additional specified attachments.
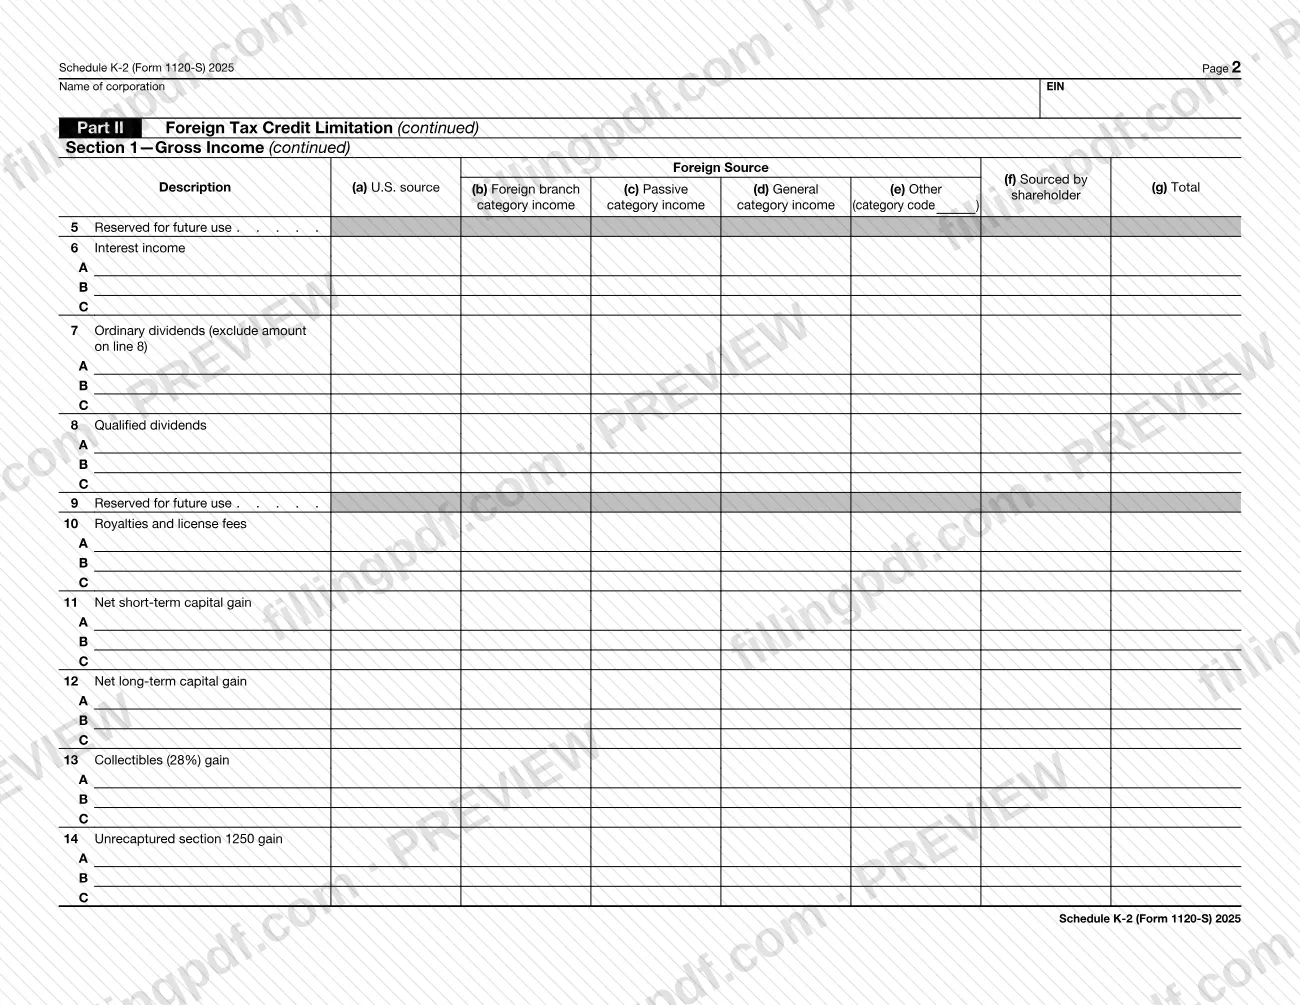
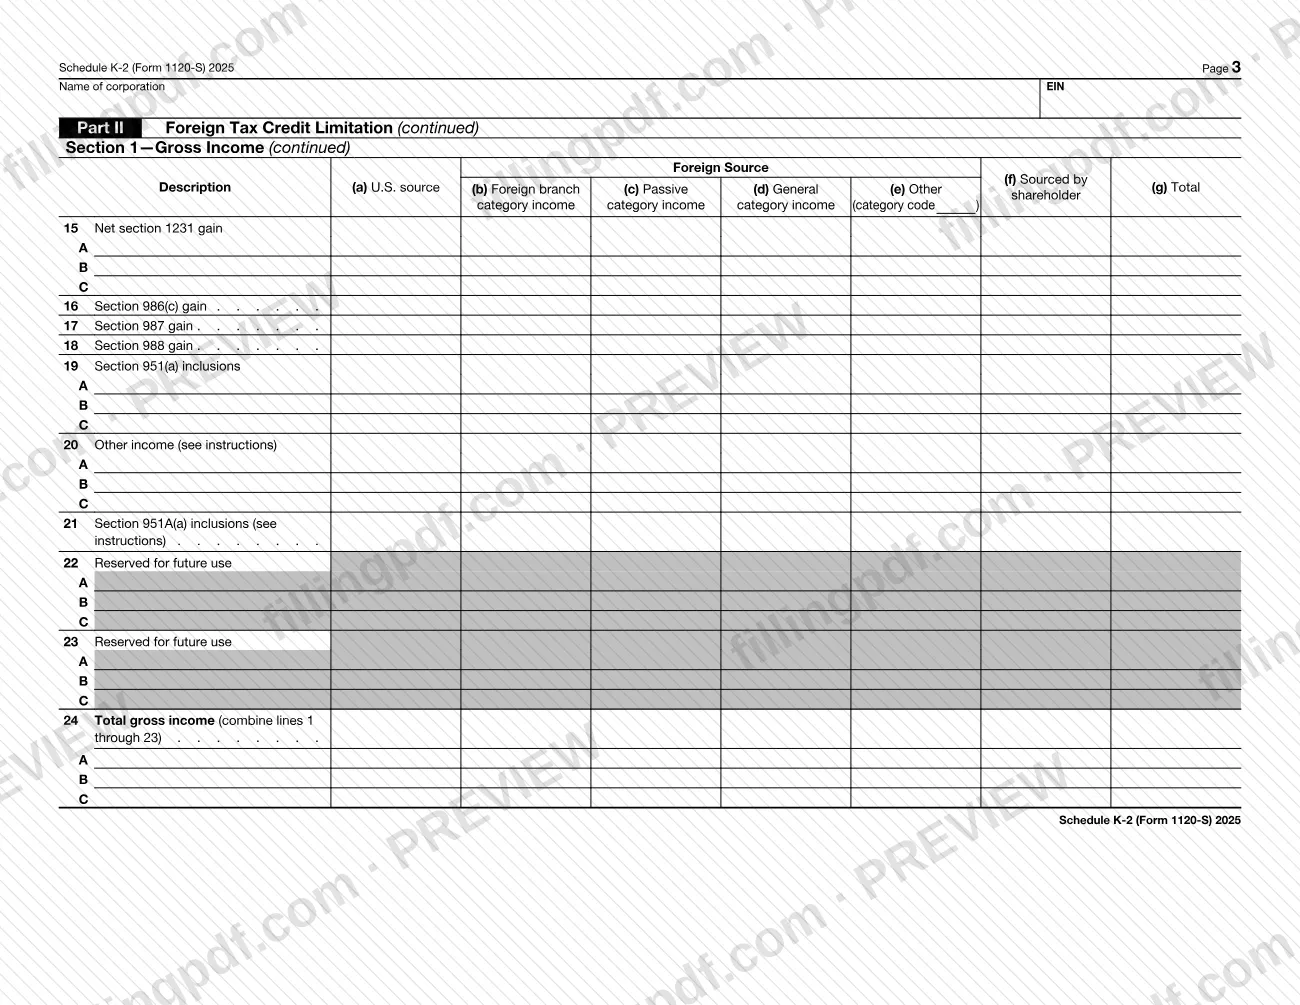
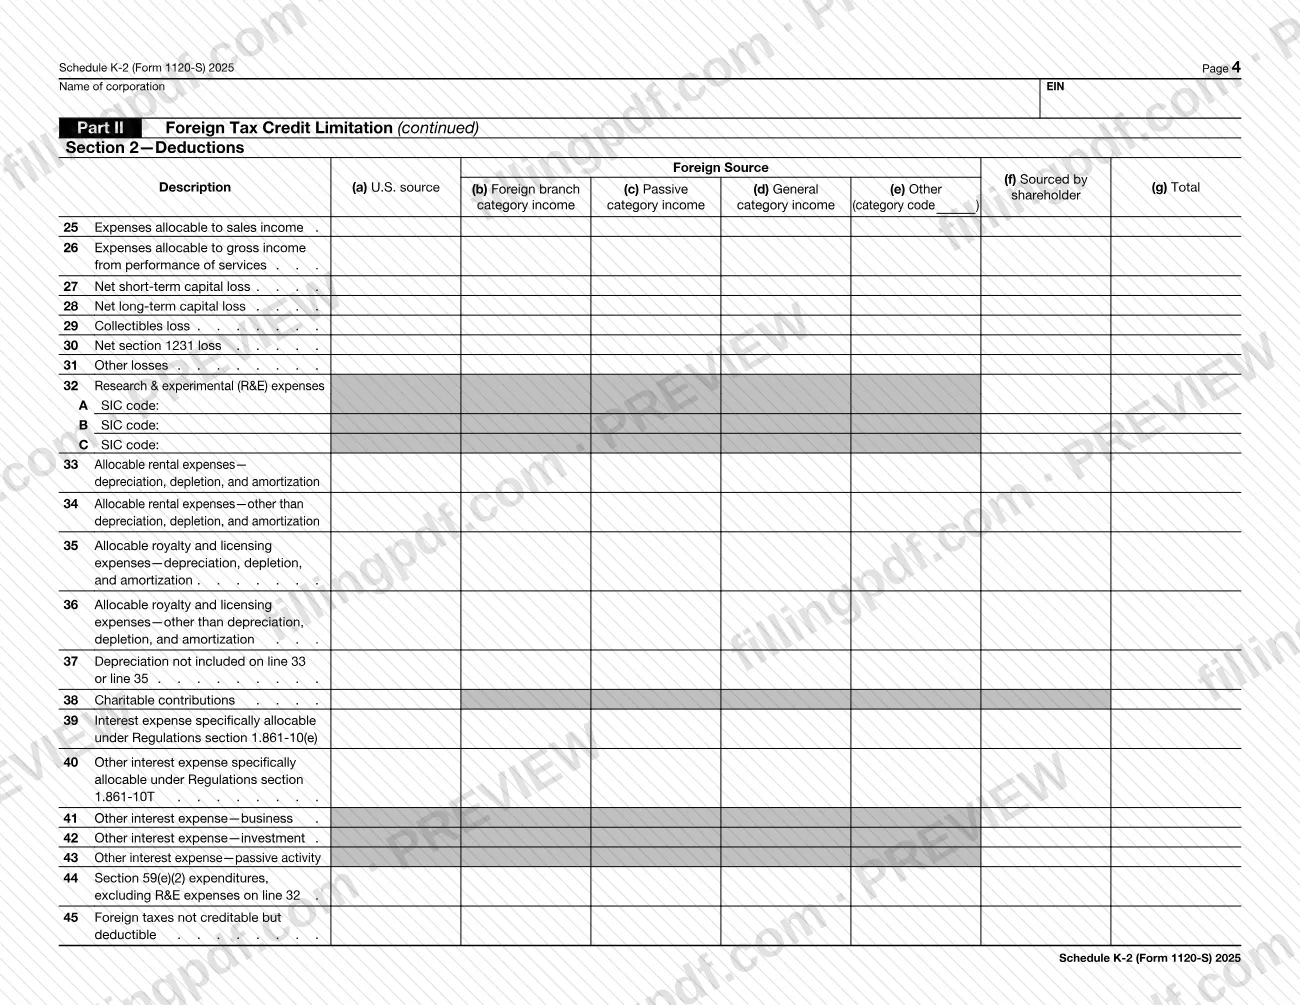
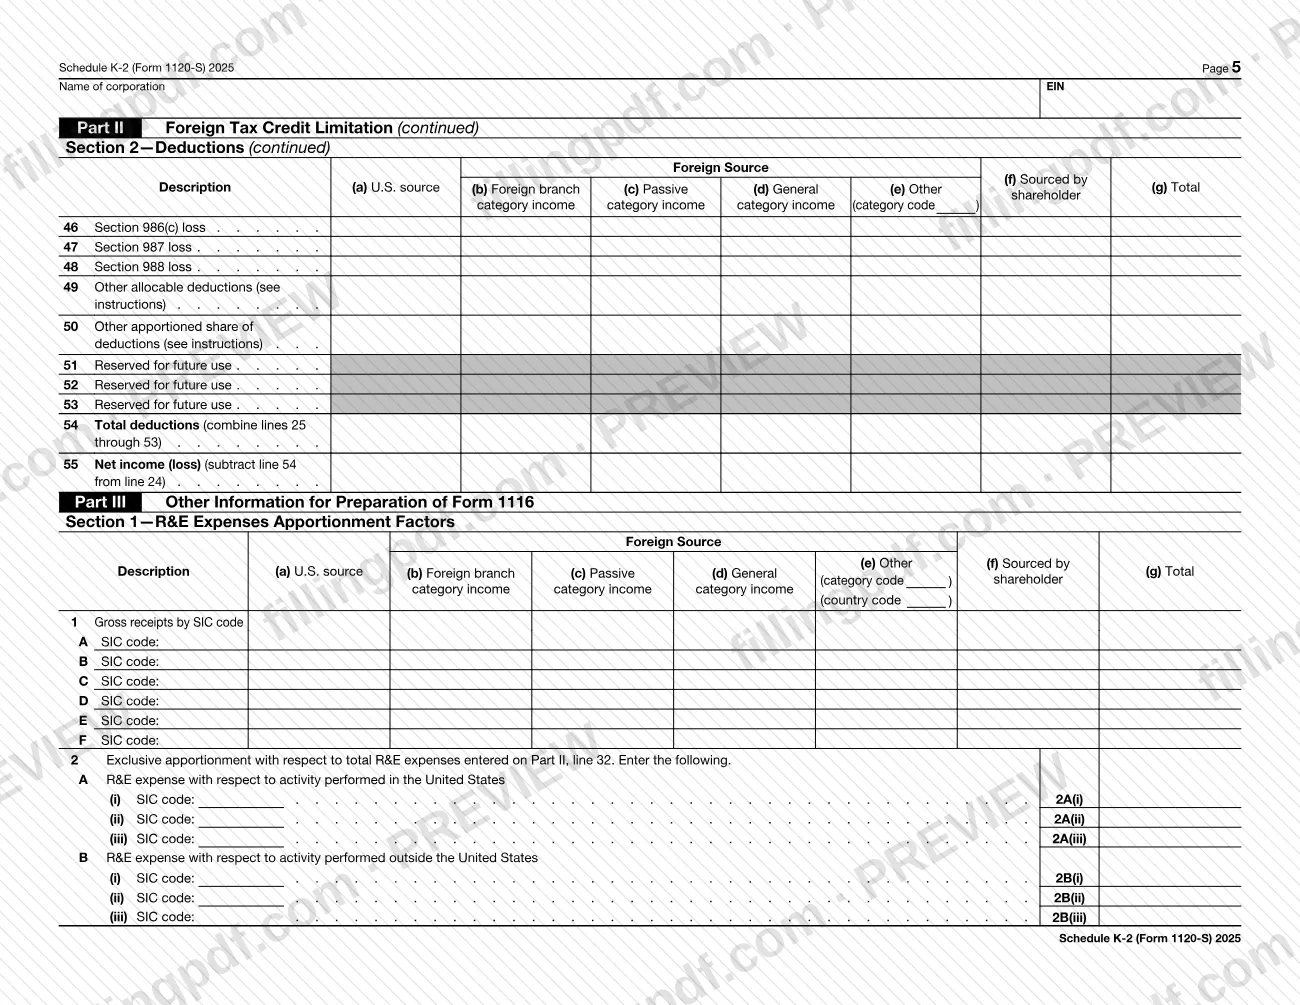
- Part II, Foreign Tax Credit Limitation, with Section 1 (gross income, lines 1 to 24) and Section 2 (deductions, lines 25 to 55).
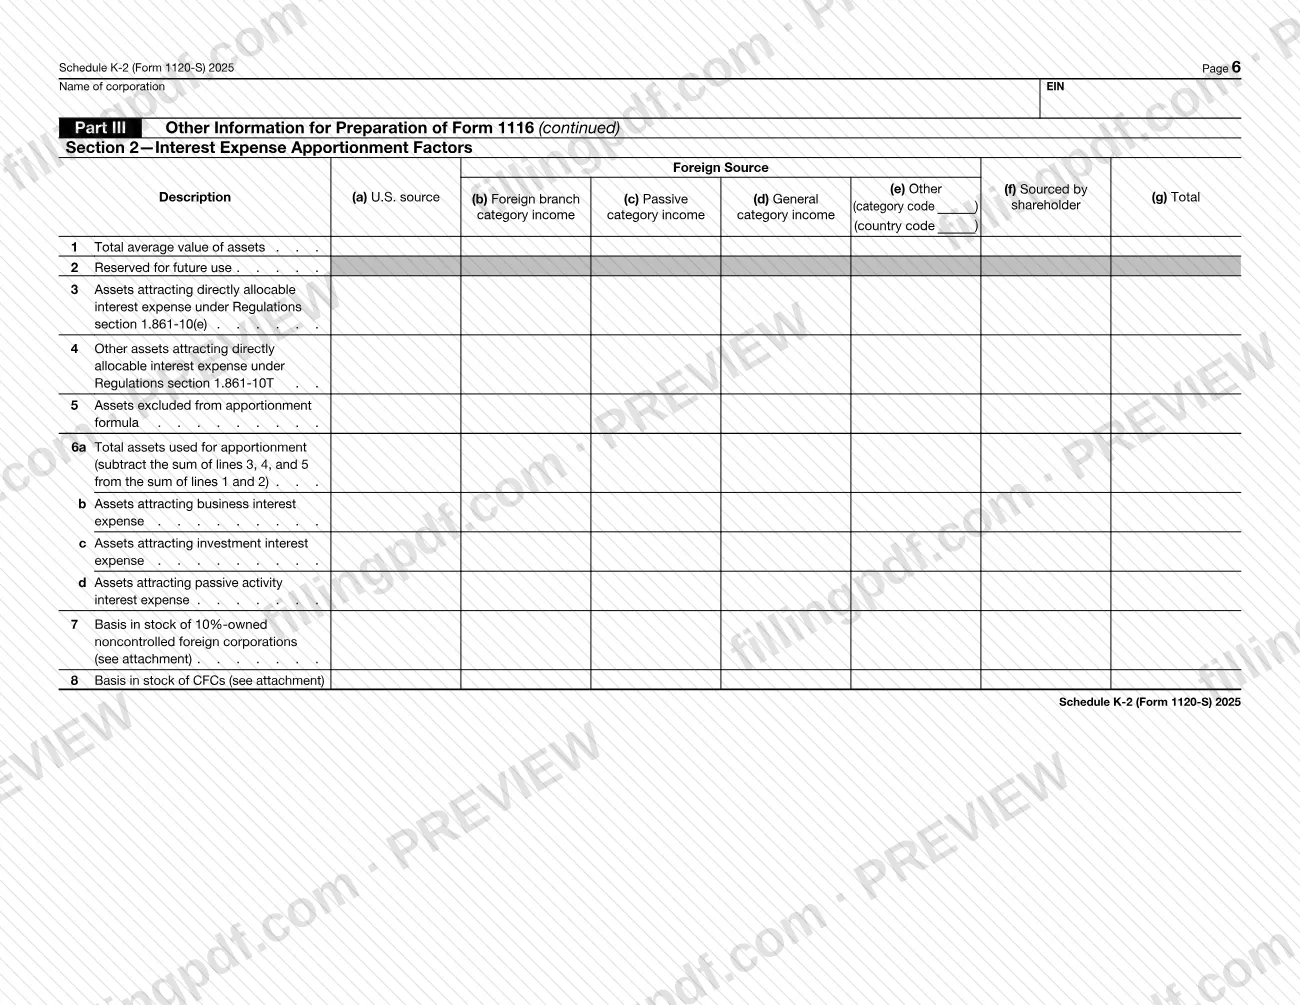
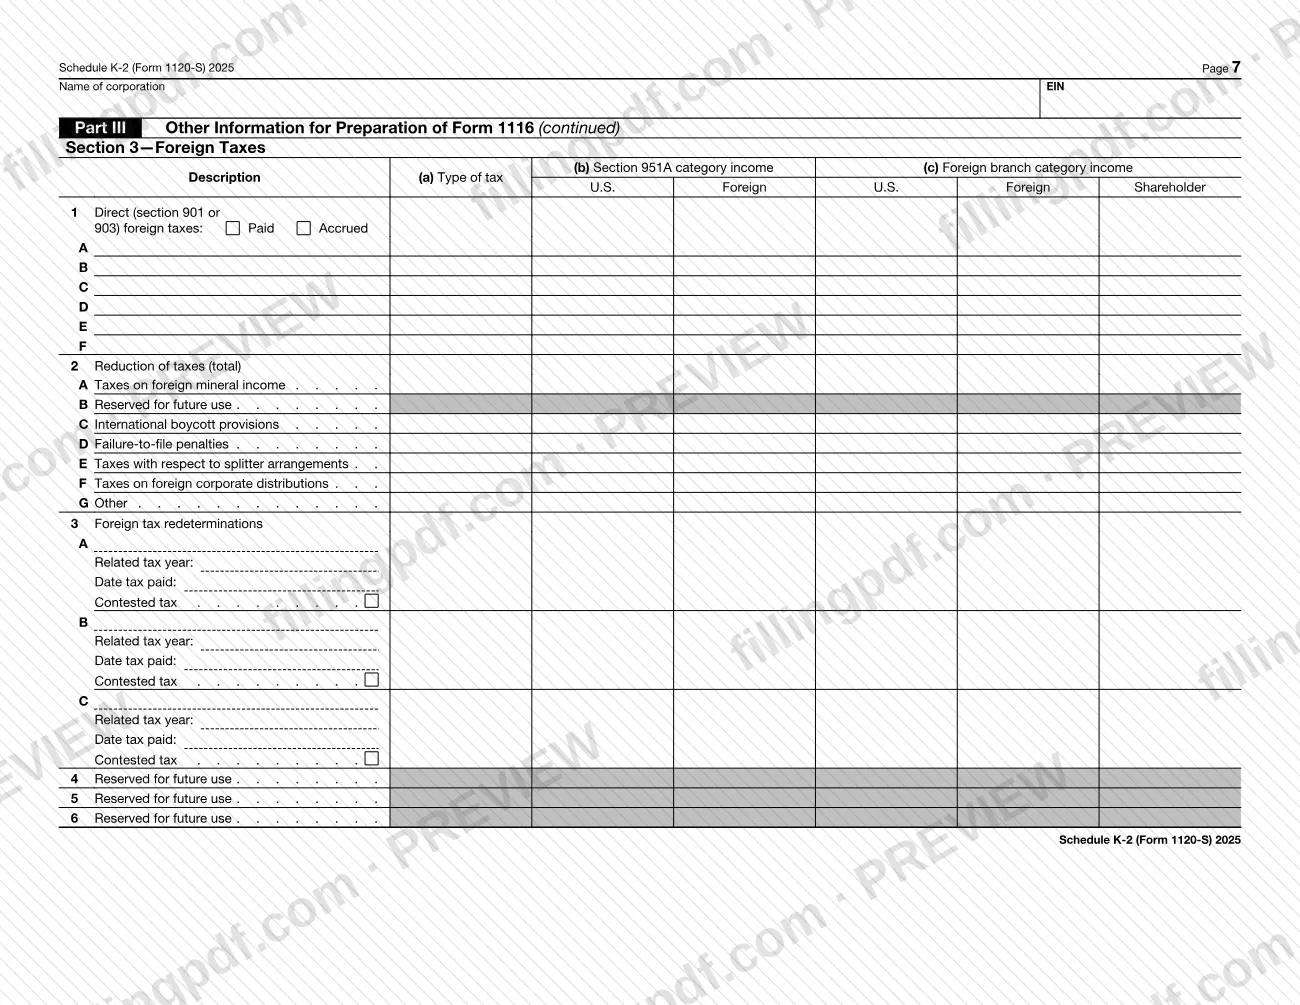
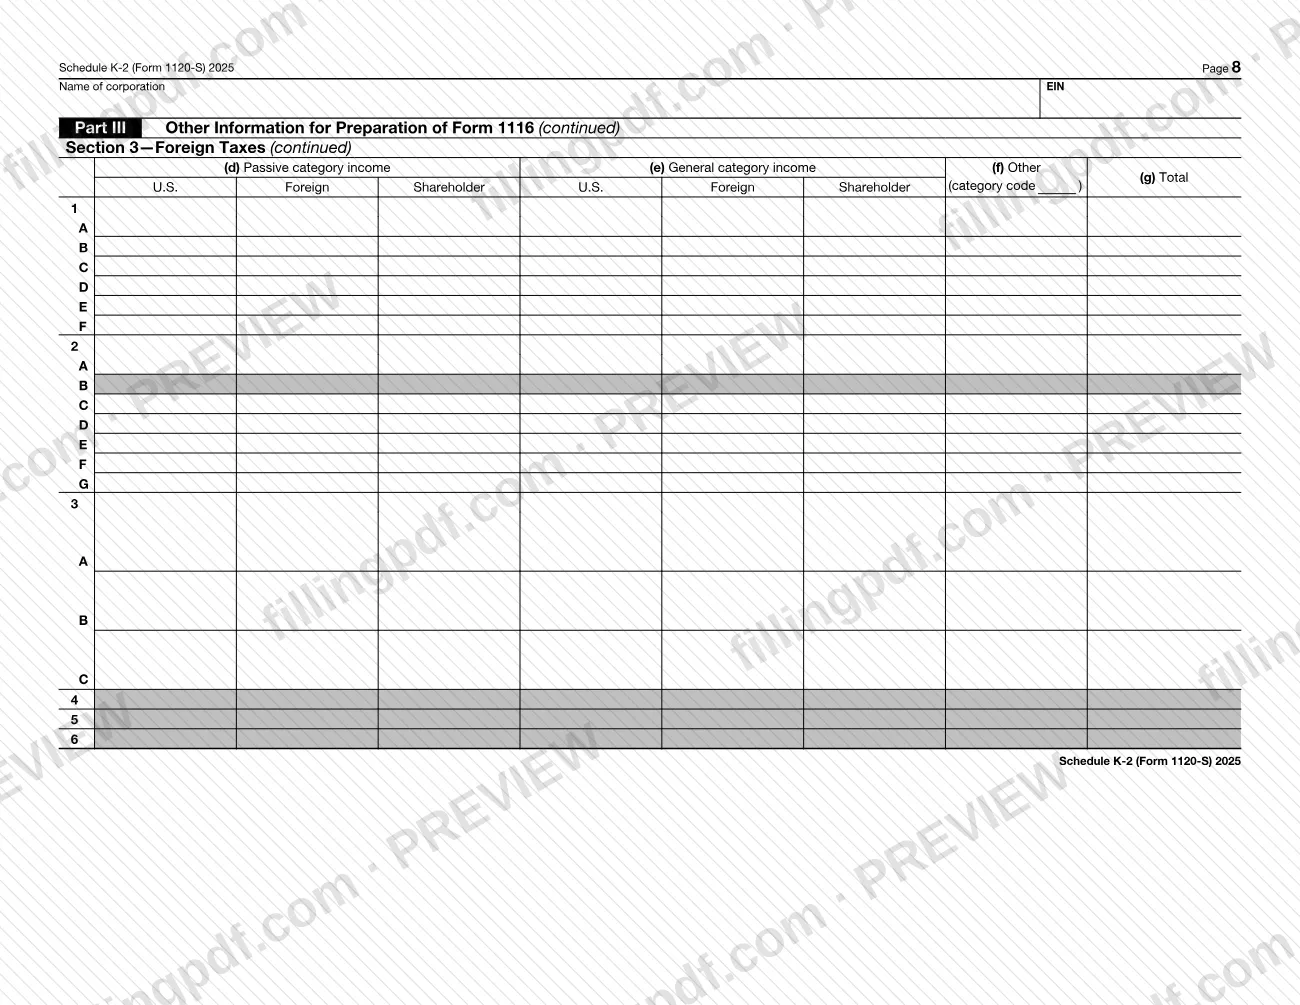
- Part III, Other Information for Preparation of Form 1116: R&E expense and interest expense apportionment factors and foreign taxes.
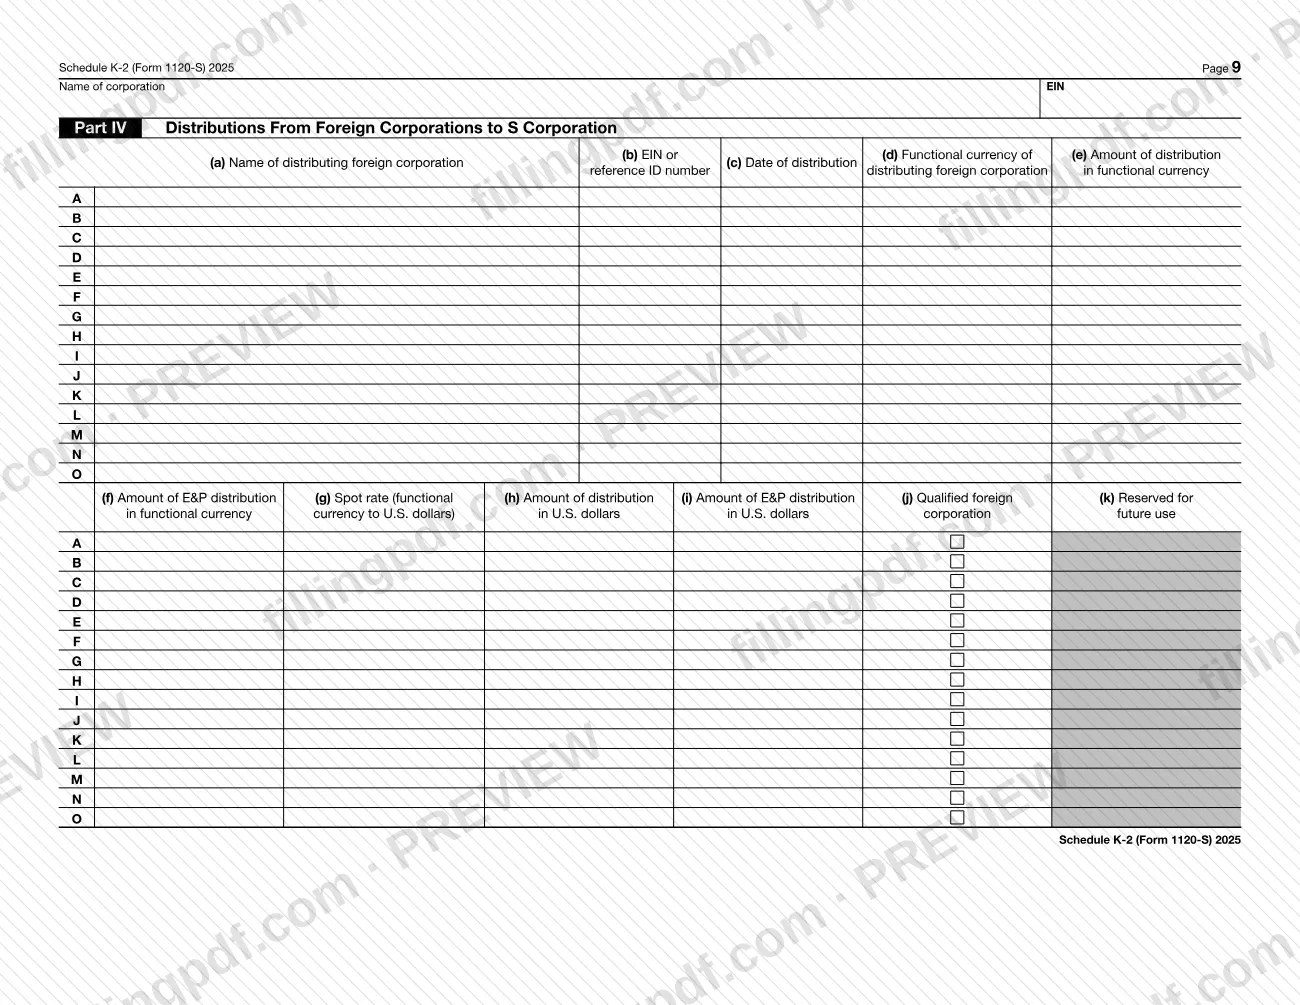
- Part IV, Distributions From Foreign Corporations to S Corporation.
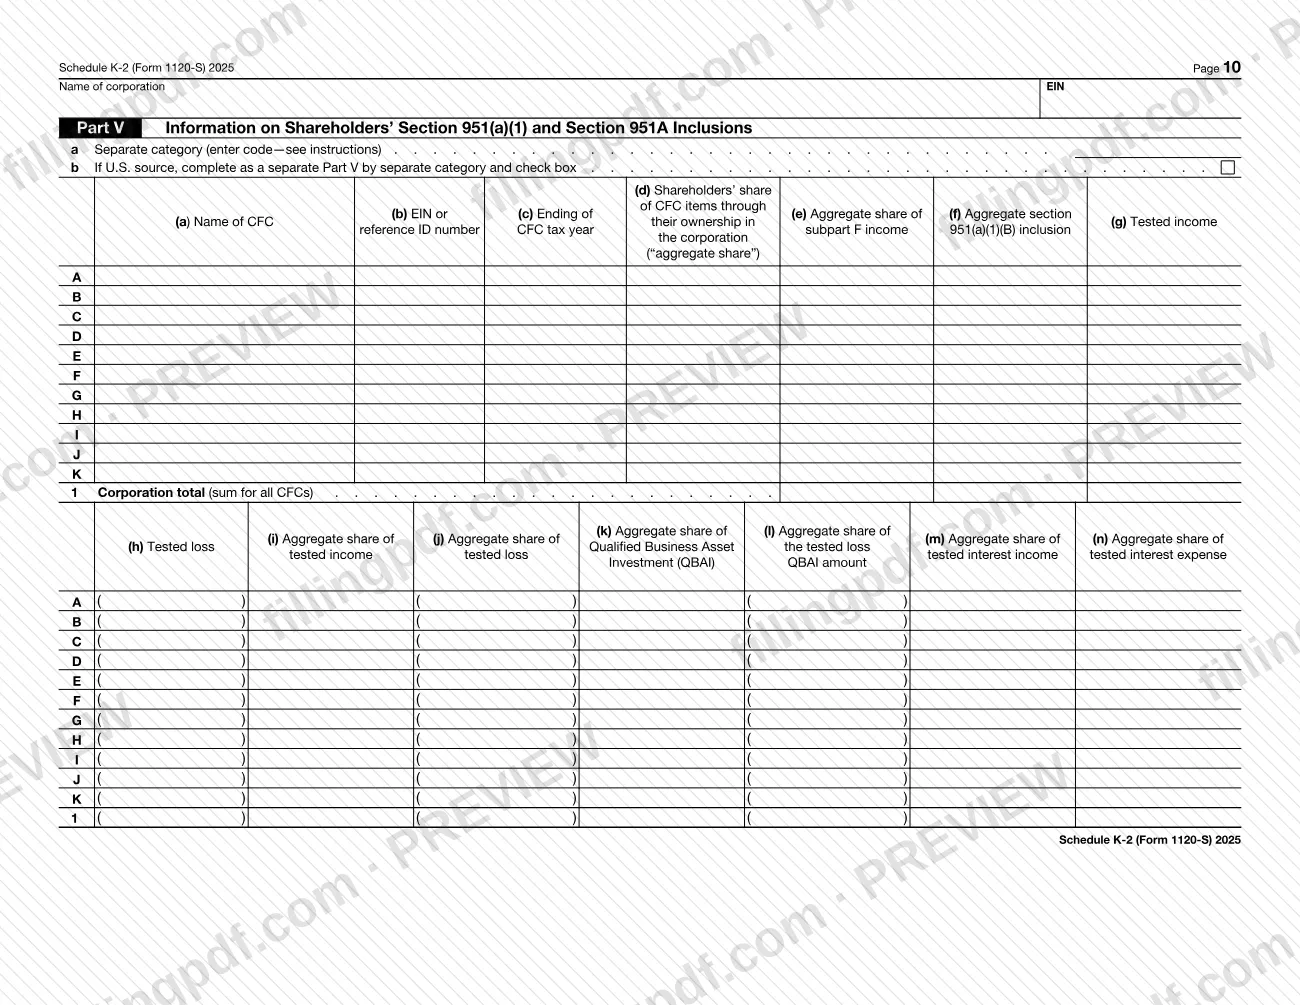
- Part V, Information on Shareholders’ Section 951(a)(1) and Section 951A Inclusions.
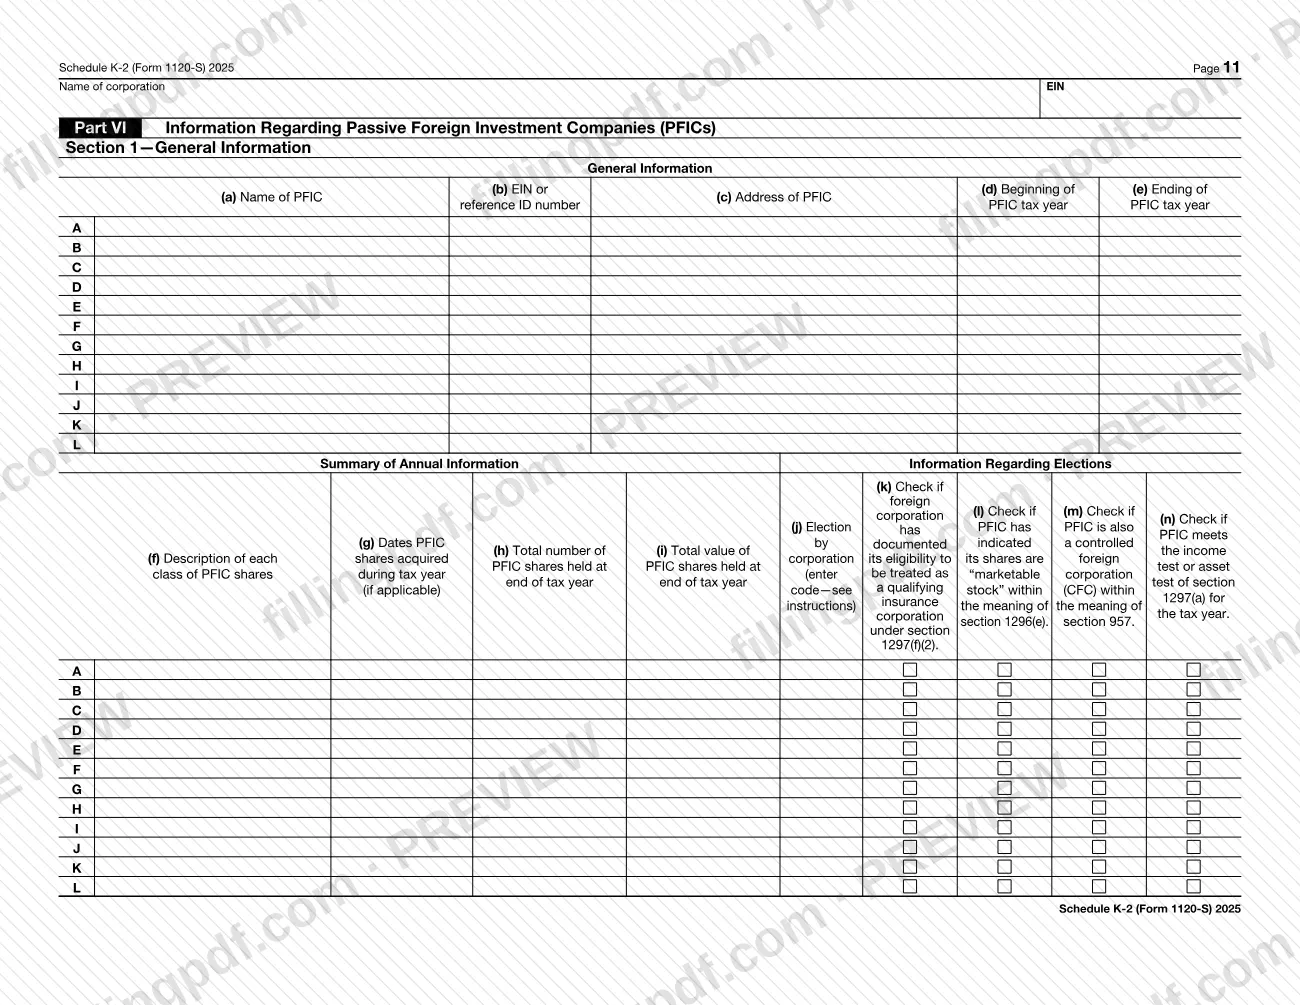
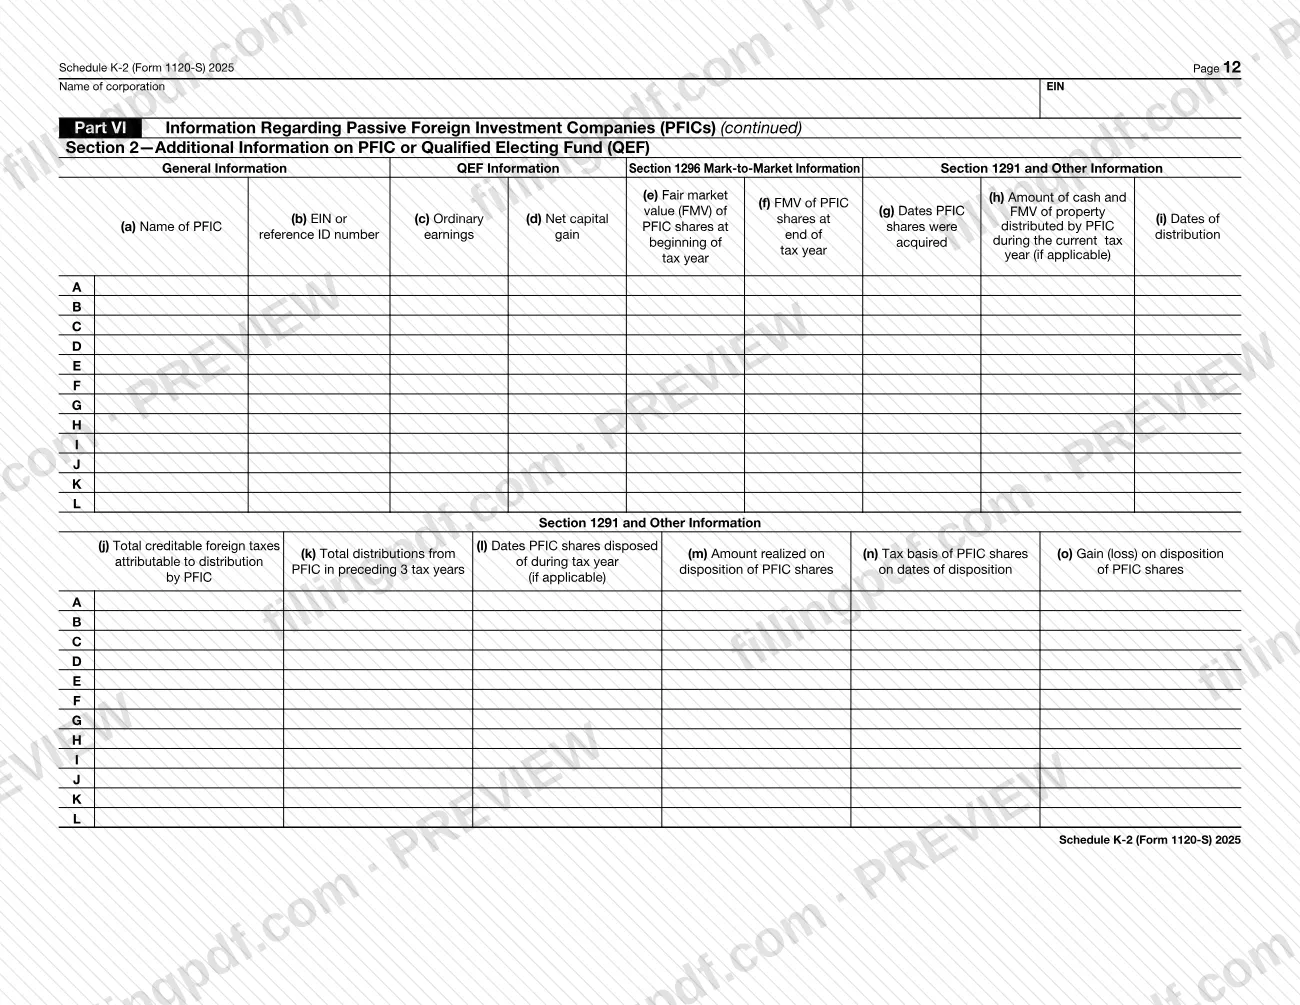
- Part VI, Information Regarding Passive Foreign Investment Companies (PFICs).
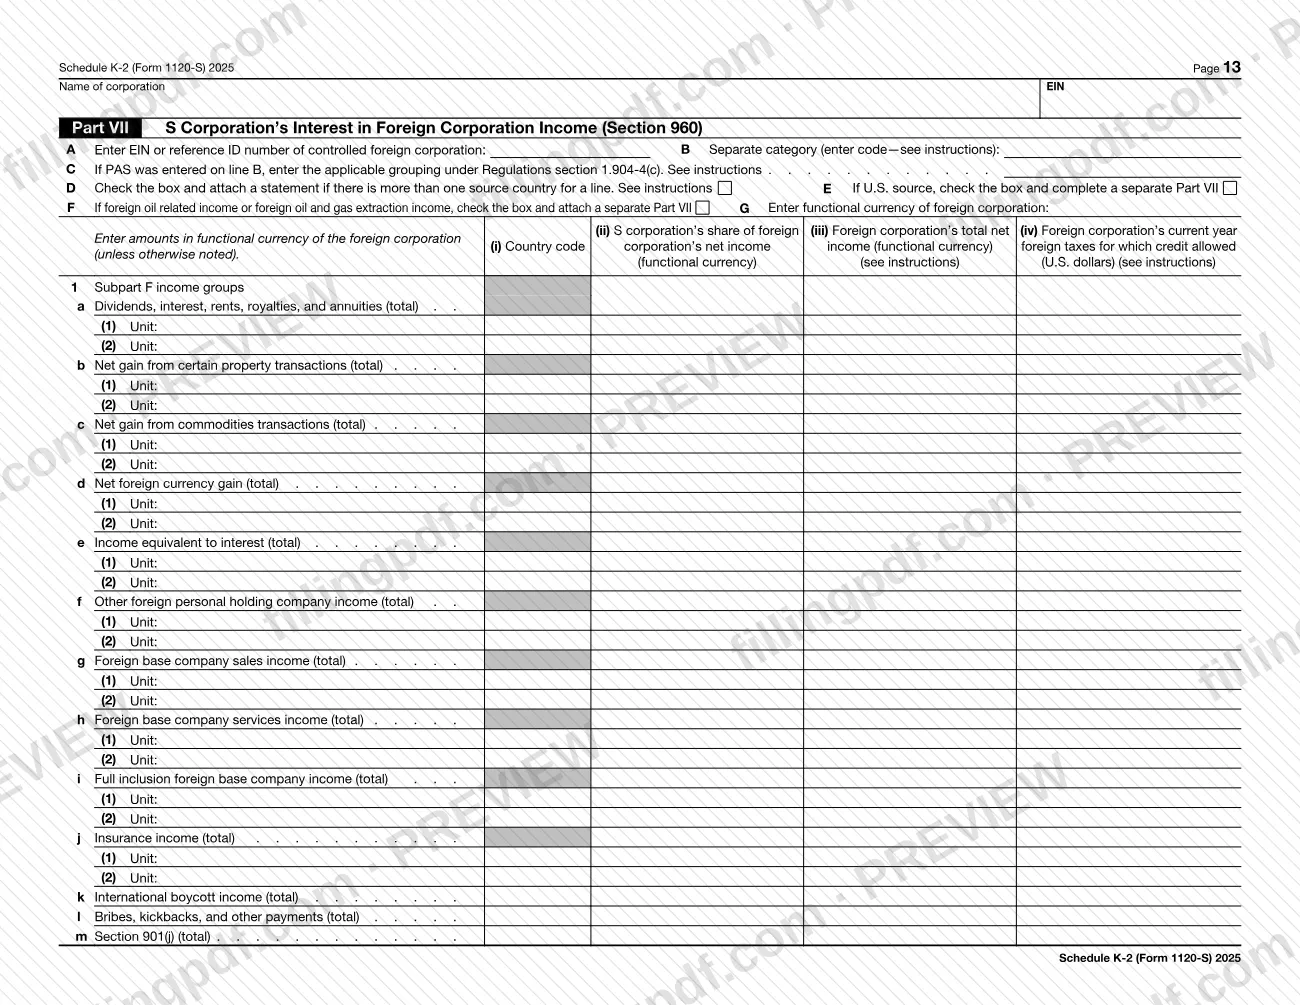
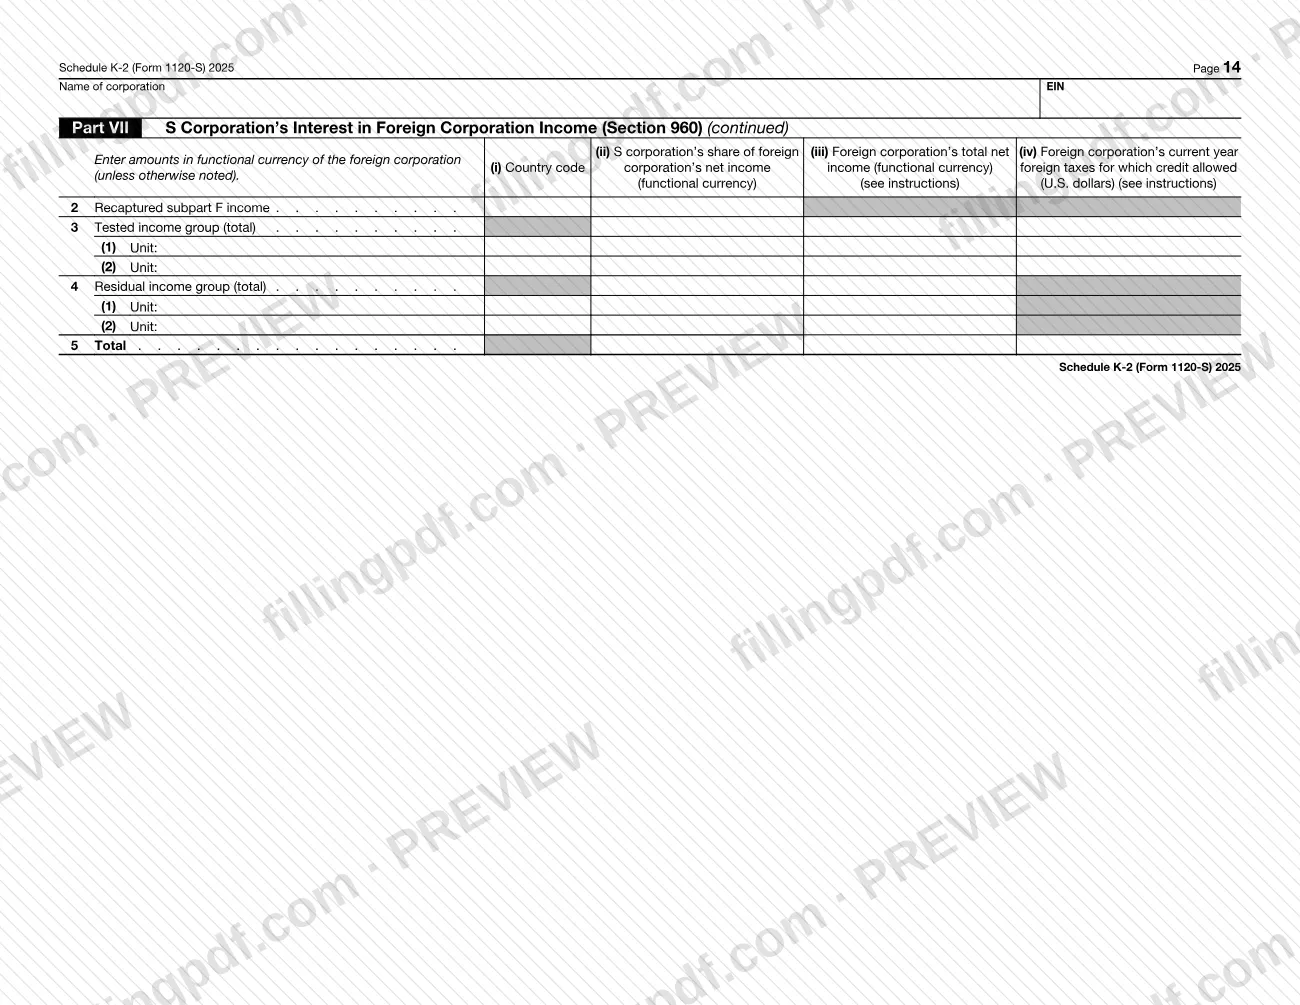
- Part VII, S Corporation’s Interest in Foreign Corporation Income (Section 960).
It is a schedule of Form 1120-S and is not filed on its own.
Who needs to file Schedule K-2 (Form 1120-S)?
The main group is S corporations that file Form 1120-S and have international items to report. The form says to attach it to Form 1120-S and asks for the name of the corporation and its EIN.
You do not necessarily complete every part. Item A asks, for each of Parts I through VII, whether the part applies. If you answer Yes, you complete and attach that part; the form gives no instruction to attach a part that does not apply.
Which parts apply to a particular corporation depends on its foreign activity. For example, Part IV concerns distributions received from foreign corporations, Part V concerns inclusions from controlled foreign corporations (CFCs), and Part VI concerns PFICs. The form itself does not describe who may sign or file for the corporation, so refer to the IRS instructions for Form 1120-S at www.irs.gov/Form1120S for eligibility questions.
When to file Schedule K-2 (Form 1120-S)
Schedule K-2 is completed and attached whenever the Form 1120-S it belongs to is prepared for the 2025 tax year. The form prints no due date of its own, so it travels with Form 1120-S; for the deadline that applies to Form 1120-S, check the IRS instructions at www.irs.gov/Form1120S.
If you are correcting a schedule you already submitted, check the Amended K-2 box in item B.
Documents you need
- Form 1120-S itself is not listed here: the schedule is attached to it, and every part you answer Yes to in item A is completed and attached.
- For Part I box 4, Foreign tax translation: a description and statement attached to the schedule.
- For Part III, Section 2, lines 7 and 8 (basis in stock of 10%-owned noncontrolled foreign corporations and of CFCs): the attachment the form calls for, see instructions.
- For Part V line b: a separate Part V for each separate category when the income is U.S. source, with the box checked.
- For Part VII line D: a statement attached when there is more than one source country for a line.
- For Part VII lines E and F: a separate Part VII when the income is U.S. source, or when it is foreign oil related income or foreign oil and gas extraction income.
How to fill out Schedule K-2 (Form 1120-S)
Enter corporation name and EIN
At the top of page 1, enter the name of the corporation and its employer identification number (EIN). The same two entries repeat on every page.
Mark which parts apply
In item A, answer Yes or No on lines 1 to 7 for Parts I through VII. Complete and attach each part you answer Yes to. Check the Amended K-2 box in item B if this is an amended schedule.
Complete Part I
Check the box or boxes for the additional specified attachments that apply, numbered 1 to 13 on the form. If you check box 4, Foreign tax translation, attach a description and statement.
Report gross income in Part II
In Section 1, enter income on lines 1 to 23 in columns (a) to (g): U.S. source, foreign branch, passive, general, other (with category code), sourced by shareholder, and total. Line 24 is the total of lines 1 through 23.
Report deductions in Part II
In Section 2, enter deductions on lines 25 to 53, using the SIC code lines under line 32 for R&E expenses. Line 54 is the total of lines 25 through 53, and line 55 is line 24 minus line 54.
Complete Part III apportionment factors
In Section 1, enter gross receipts by SIC code and the R&E expense by activity location on lines 2A and 2B. In Section 2, enter the asset and basis amounts on lines 1 to 8, including the attachments the form calls for on lines 7 and 8.
Enter foreign taxes in Part III
In Section 3, list direct foreign taxes paid or accrued on line 1, reductions of taxes on lines 2A to 2G, and foreign tax redeterminations on line 3 with the related tax year and date tax paid.
Complete Part IV distributions
For each distributing foreign corporation, enter the name, EIN or reference ID number, date of distribution, functional currency, amounts in functional currency and U.S. dollars, the spot rate and whether it is a qualified foreign corporation.
Complete Part V inclusions
Enter the separate category code on line a and check the line b box if the income is U.S. source. For each CFC, enter the name, EIN or reference ID number, tax year end and the aggregate share amounts in columns (d) to (n), with totals on line 1.
Complete Part VI for PFICs
In Section 1, give each PFIC's name, EIN or reference ID number, address, tax year dates, share details and election checkboxes. In Section 2, enter the QEF, mark-to-market and section 1291 information.
Complete Part VII for section 960
Enter the CFC's EIN or reference ID number, separate category code and functional currency in lines A to G. Then enter the country code and amounts for each income group on lines 1 to 5 in columns (i) to (iv).
Review, download and attach
Check that every part marked Yes is complete, that totals agree and that any statements or separate parts are included. Download or print the completed PDF from FillingPDF and attach it to Form 1120-S.
How to submit Schedule K-2 (Form 1120-S)
Schedule K-2 (Form 1120-S) is submitted as an attachment to Form 1120-S; it has no separate filing channel, address or portal printed on it.
- With Form 1120-S: attach the completed schedule, with each part you answered Yes to in item A, to Form 1120-S and send the package the way you submit that form.
- Additional attachments: some entries call for statements or separate parts, such as the foreign tax translation statement in Part I or a separate Part VII. Include them with the schedule.
- Instructions and updates: the form directs you to www.irs.gov/Form1120S for instructions and the latest information.
FillingPDF lets you fill out and download the PDF; submission follows the IRS channels that apply to Form 1120-S.
Common mistakes to avoid
- Filing the schedule without attaching it to Form 1120-S; the form states it is to be attached to Form 1120-S.
- Answering Yes to a part in item A (lines 1 to 7) but not completing and attaching that part.
- Not checking the Amended K-2 box in item B when the schedule corrects one already submitted.
- Checking Part I box 4, Foreign tax translation, without attaching the description and statement the form asks for.
- Leaving out the statement required on Part VII line D when a line has more than one source country.
- Entering U.S. source amounts in Part V or Part VII without completing a separate Part V or Part VII and checking the box.
- Entering Part VII amounts in U.S. dollars where the form says to use the foreign corporation's functional currency; only column (iv) is in U.S. dollars unless otherwise noted.
- Totaling line 24 or line 54 incorrectly: line 24 combines lines 1 through 23, and line 54 combines lines 25 through 53.
- Computing line 55 in the wrong direction; the form says to subtract line 54 from line 24.
Frequently asked questions
What is Schedule K-2 (Form 1120-S)?
Schedule K-2 (Form 1120-S), Shareholders’ Pro Rata Share Items—International, is an IRS schedule attached to Form 1120-S. It reports an S corporation's international items in Parts I to VII, including the foreign tax credit limitation in Part II and information on foreign corporations.
Do I have to complete every part of Schedule K-2?
No. Item A asks on lines 1 to 7 whether each of Parts I through VII applies. You complete and attach only the parts you answer Yes to. Which parts apply depends on the corporation's international activity; the IRS instructions explain each part.
Is Schedule K-2 filed separately from Form 1120-S?
No. The form says to attach it to Form 1120-S, so it is submitted with that return. It prints no separate address or due date. Instructions and the latest information are at www.irs.gov/Form1120S.
When is Schedule K-2 (Form 1120-S) due?
It has no due date of its own: it is attached to Form 1120-S and travels with it for the 2025 tax year. Check the IRS instructions for Form 1120-S at www.irs.gov/Form1120S for the deadline that applies to the return.
How do I amend a Schedule K-2?
Check the Amended K-2 box in item B at the top of page 1 and complete the schedule with the corrected information. The form gives no separate amendment procedure, so see the IRS instructions for Form 1120-S.
What goes on line 55 of Schedule K-2?
Line 55, Net income (loss), is line 54 subtracted from line 24. Line 24 is total gross income (lines 1 through 23) and line 54 is total deductions (lines 25 through 53), each reported by column in Part II.
Where do PFICs and controlled foreign corporations appear on the schedule?
PFIC information goes in Part VI. Shareholders' section 951(a)(1) and section 951A inclusions from controlled foreign corporations go in Part V, and the S corporation's section 960 interest in a foreign corporation's income goes in Part VII.
Can I fill out Schedule K-2 (Form 1120-S) online?
Yes. You can fill out the fillable PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the schedule with the IRS; you submit it with Form 1120-S through the IRS channels.
Ready to fill out Schedule K-2 (Form 1120-S)?
Fill out Schedule K-2 (Form 1120-S) now