
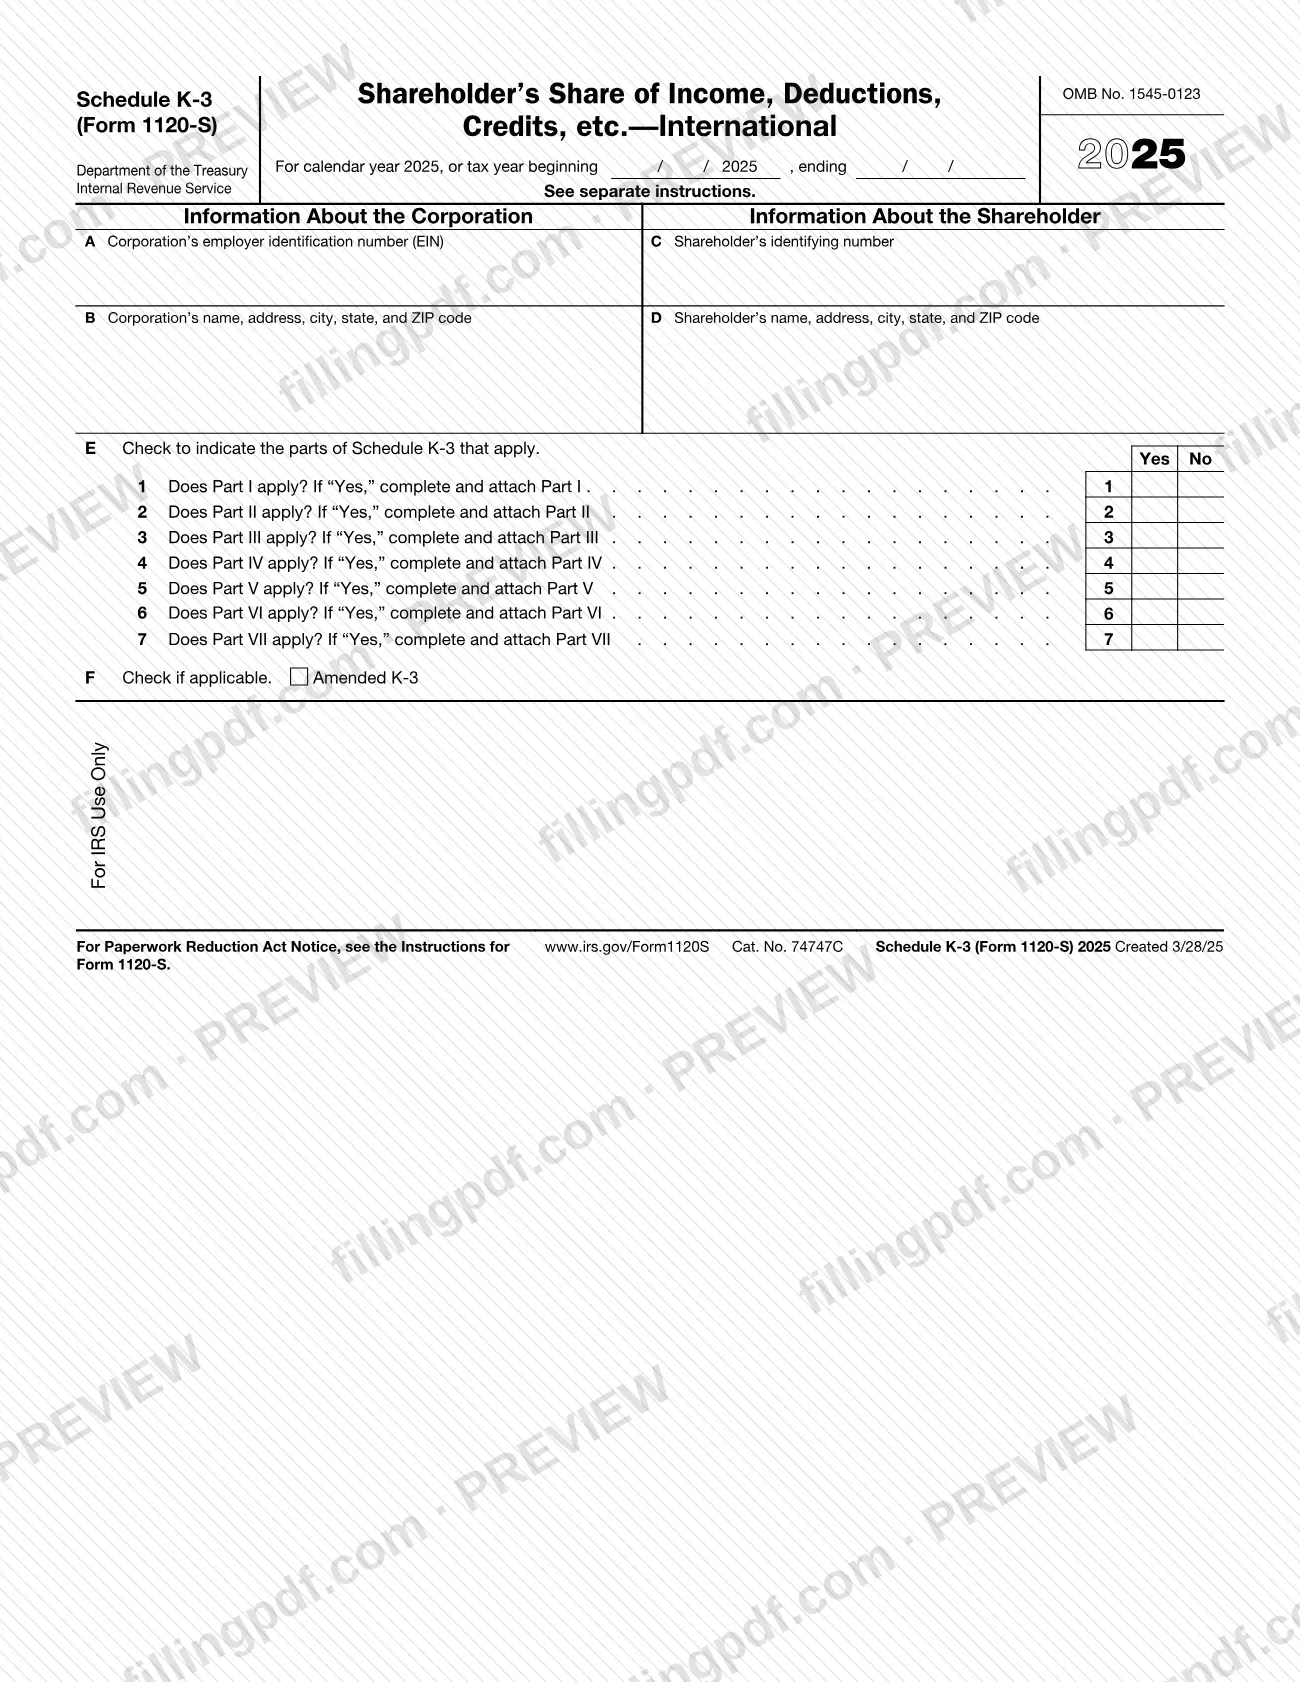
Schedule K-3 (Form 1120-S), Shareholder's Share of Income, Deductions, Credits, etc. - International, is the Internal Revenue Service (IRS) schedule that extends Schedule K-1 (Form 1120-S) with a shareholder's share of the S corporation's international tax items. S corporations complete it for shareholders, and shareholders use it for the foreign tax credit, controlled foreign corporation (CFC) inclusions and passive foreign investment company (PFIC) reporting. On this page you can fill out the form online on FillingPDF and download or print the completed PDF; the form and its instructions are published by the IRS.
Last updated
What is Schedule K-3 (Form 1120-S)?
Schedule K-3 (Form 1120-S), Shareholder's Share of Income, Deductions, Credits, etc. - International, is the IRS schedule an S corporation uses to report to each shareholder that shareholder's share of items with international tax consequences, as an extension of Schedule K-1 (Form 1120-S).
The IRS shareholder instructions explain that the schedule generally reports to shareholders their shares of the items reported on Schedule K-2. It carries OMB No. 1545-0123 and this edition is for calendar year 2025, or a tax year beginning in 2025. It is the Form 1120-S schedule, issued by the S corporation to its shareholders, and a shareholder uses only the parts that apply.
The form has seven parts:
- Part I: other current year international information, shown as boxes 1 through 13.
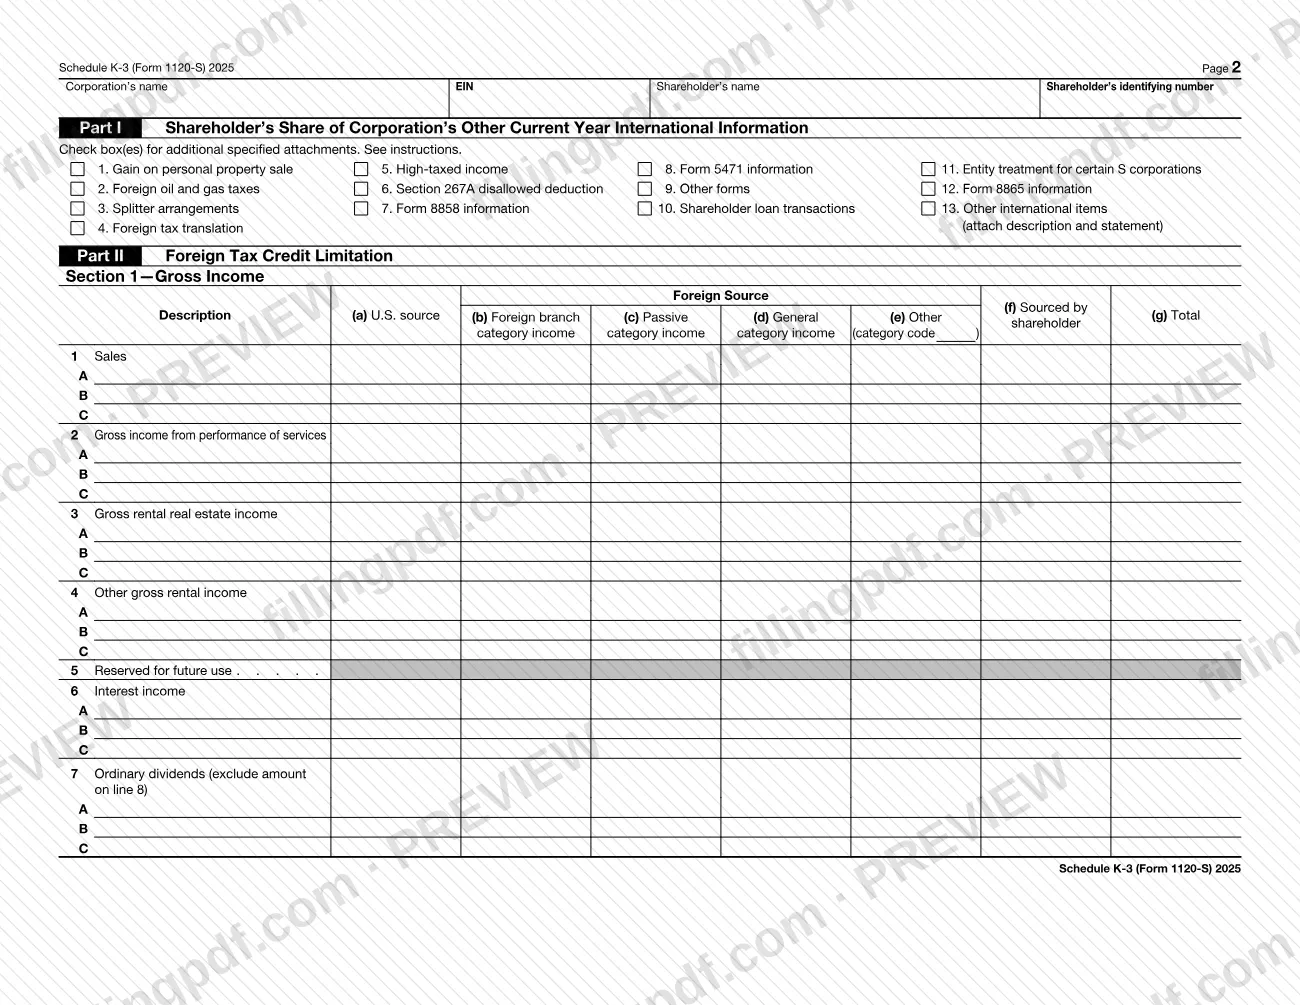
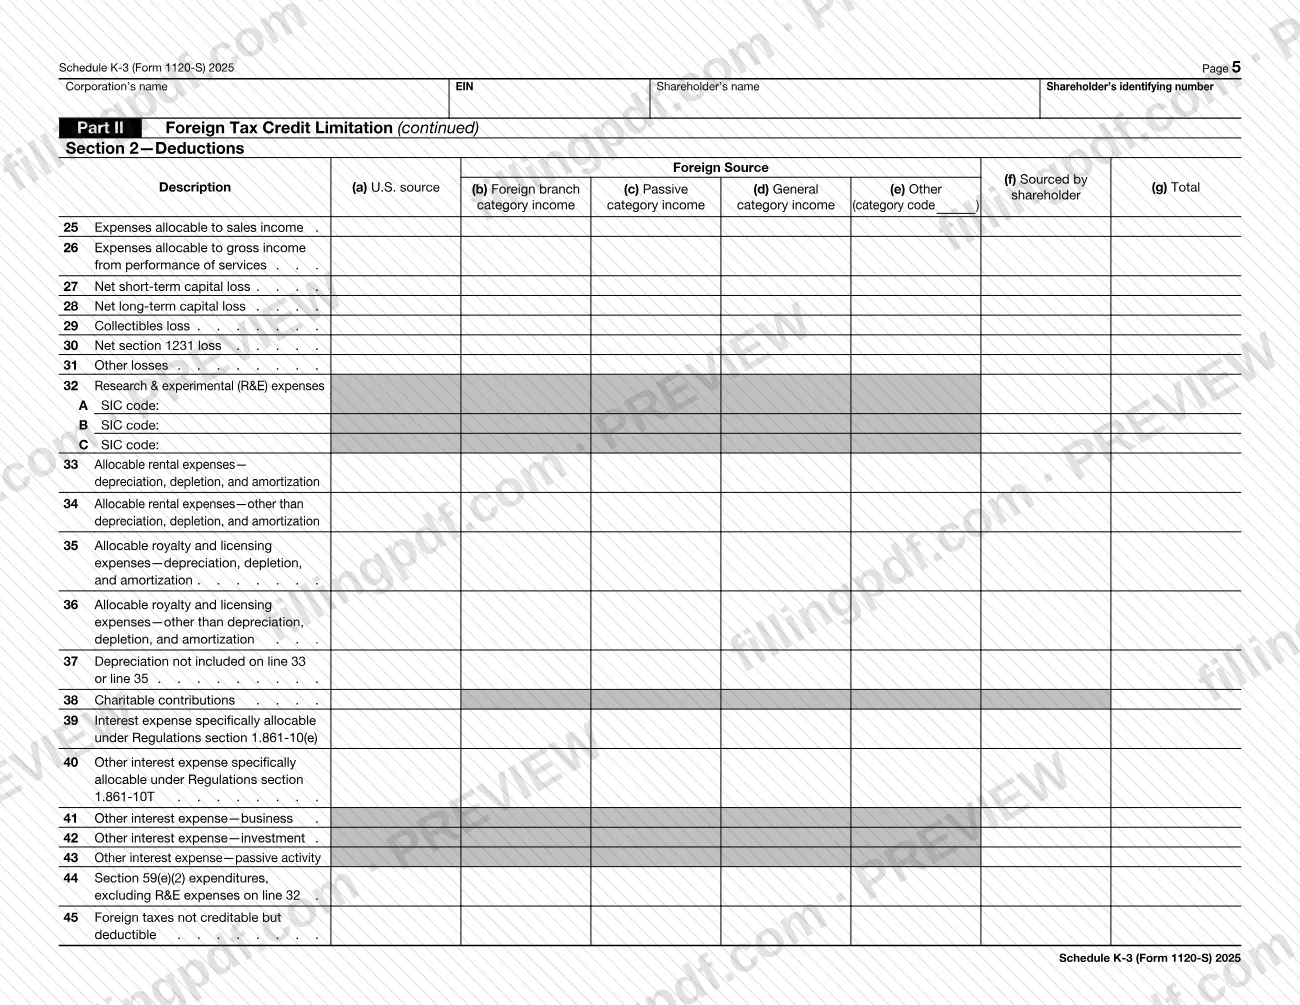
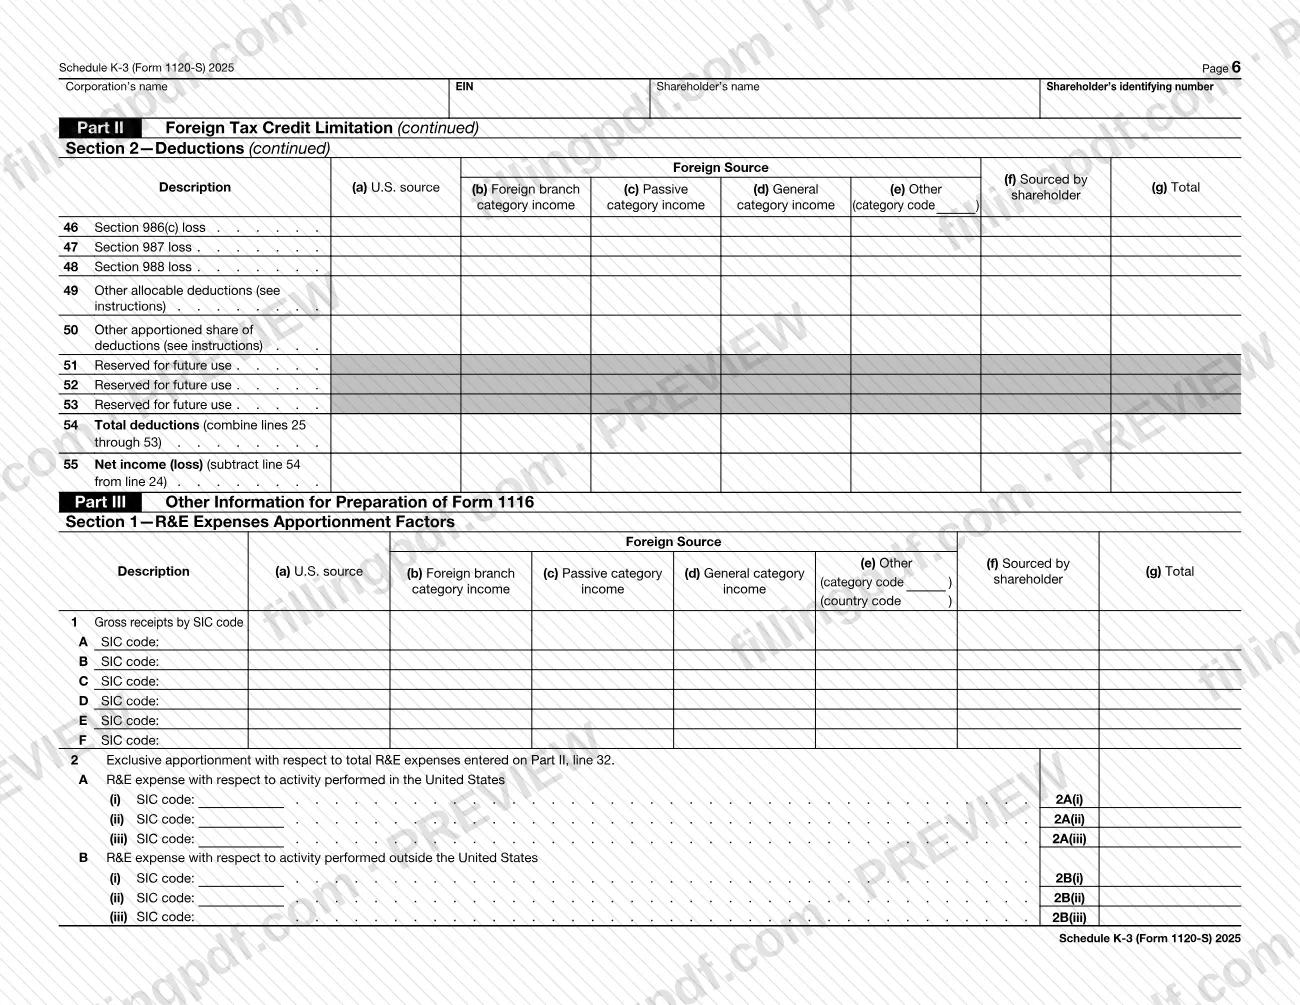
- Part II: foreign tax credit limitation, with gross income (lines 1-24), deductions (lines 25-54) and net income (line 55).
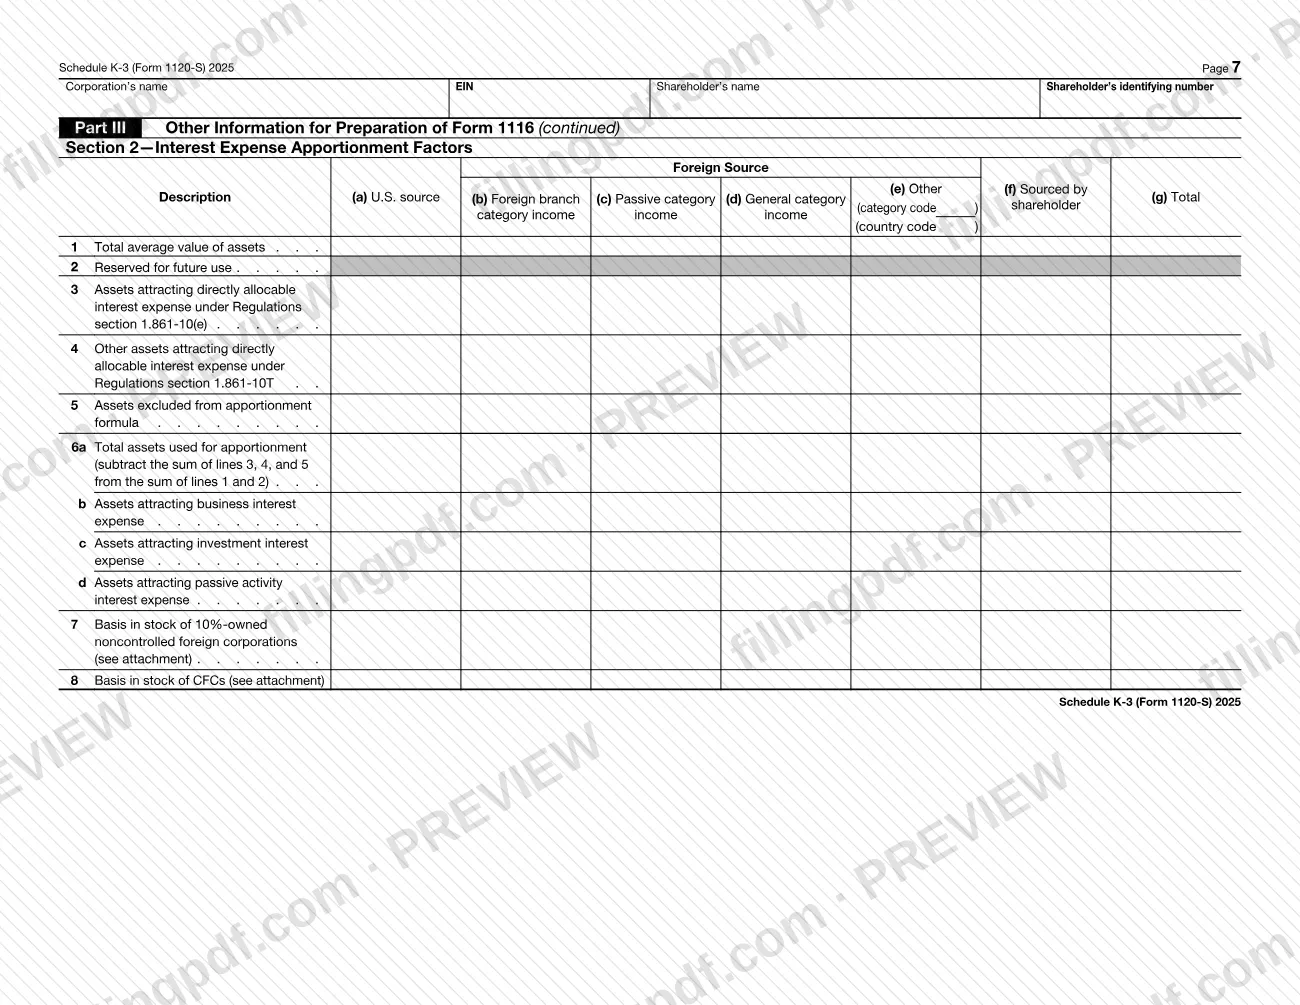
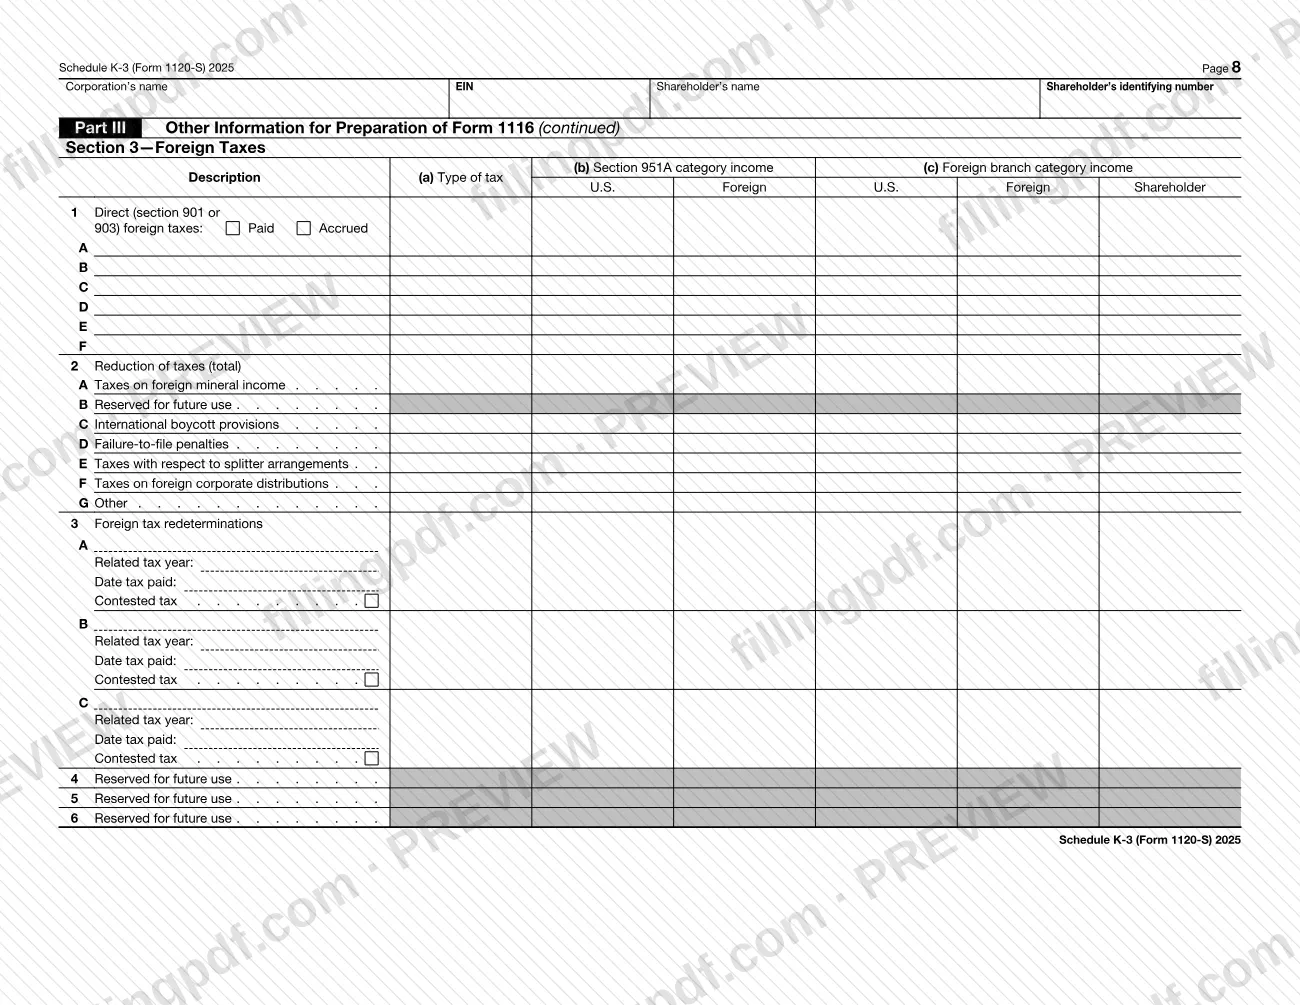
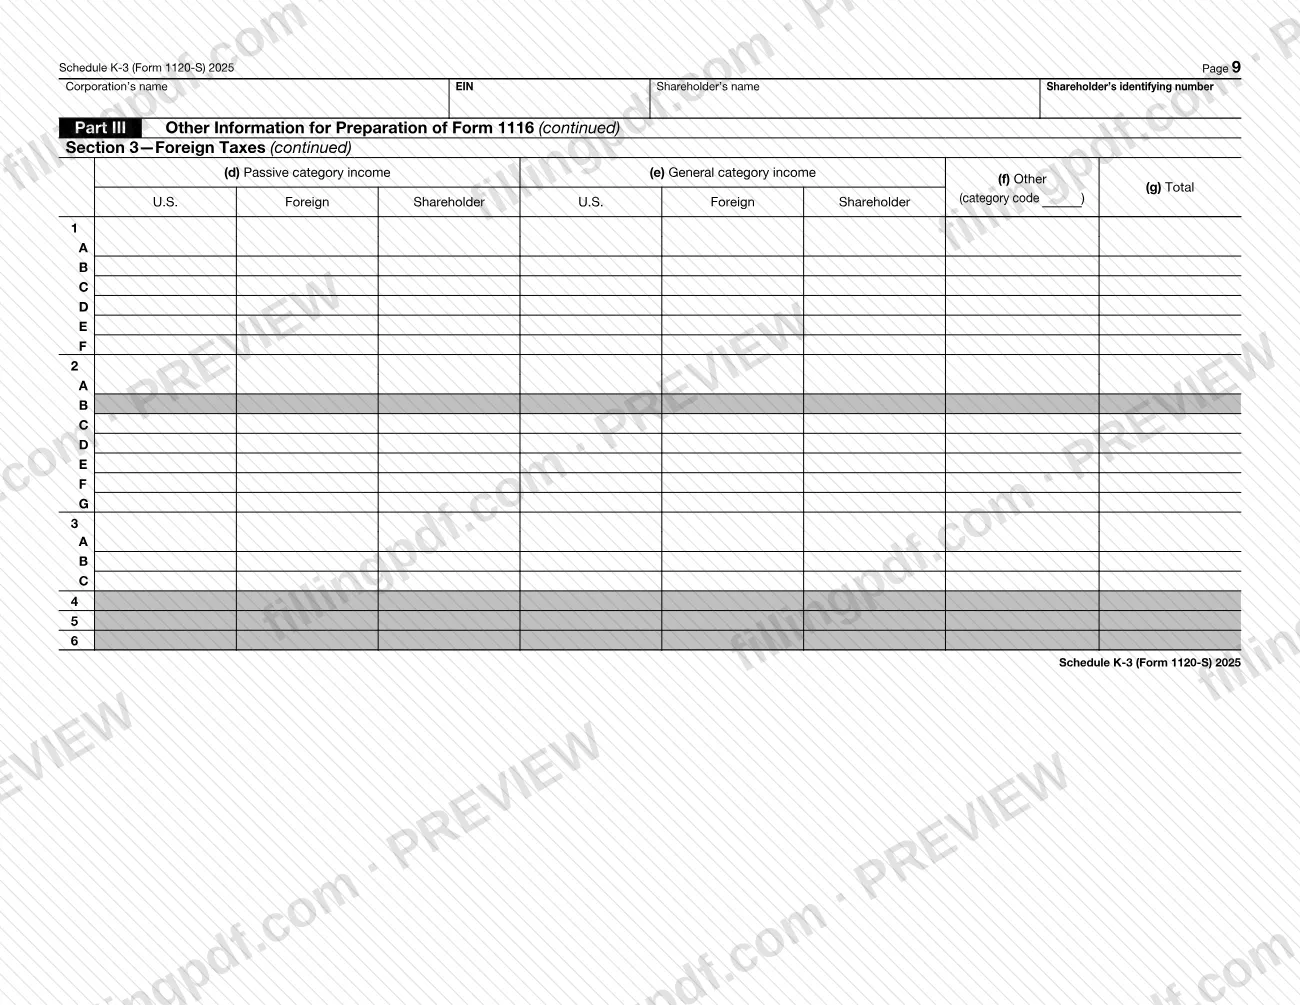
- Part III: other information for preparing Form 1116, covering R&E expense and interest expense apportionment factors and foreign taxes.
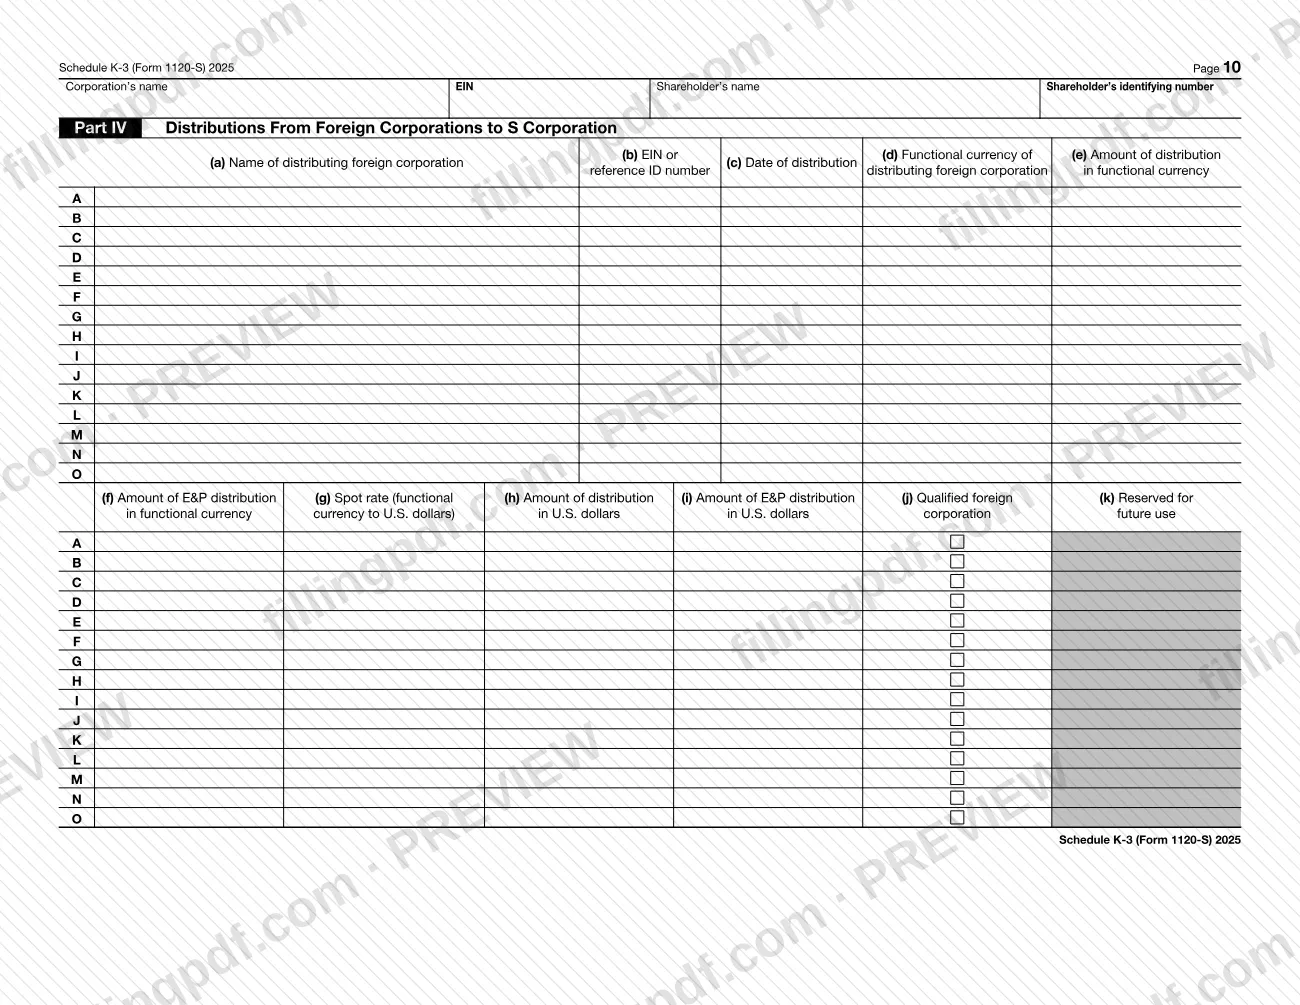
- Part IV: distributions from foreign corporations to the S corporation.
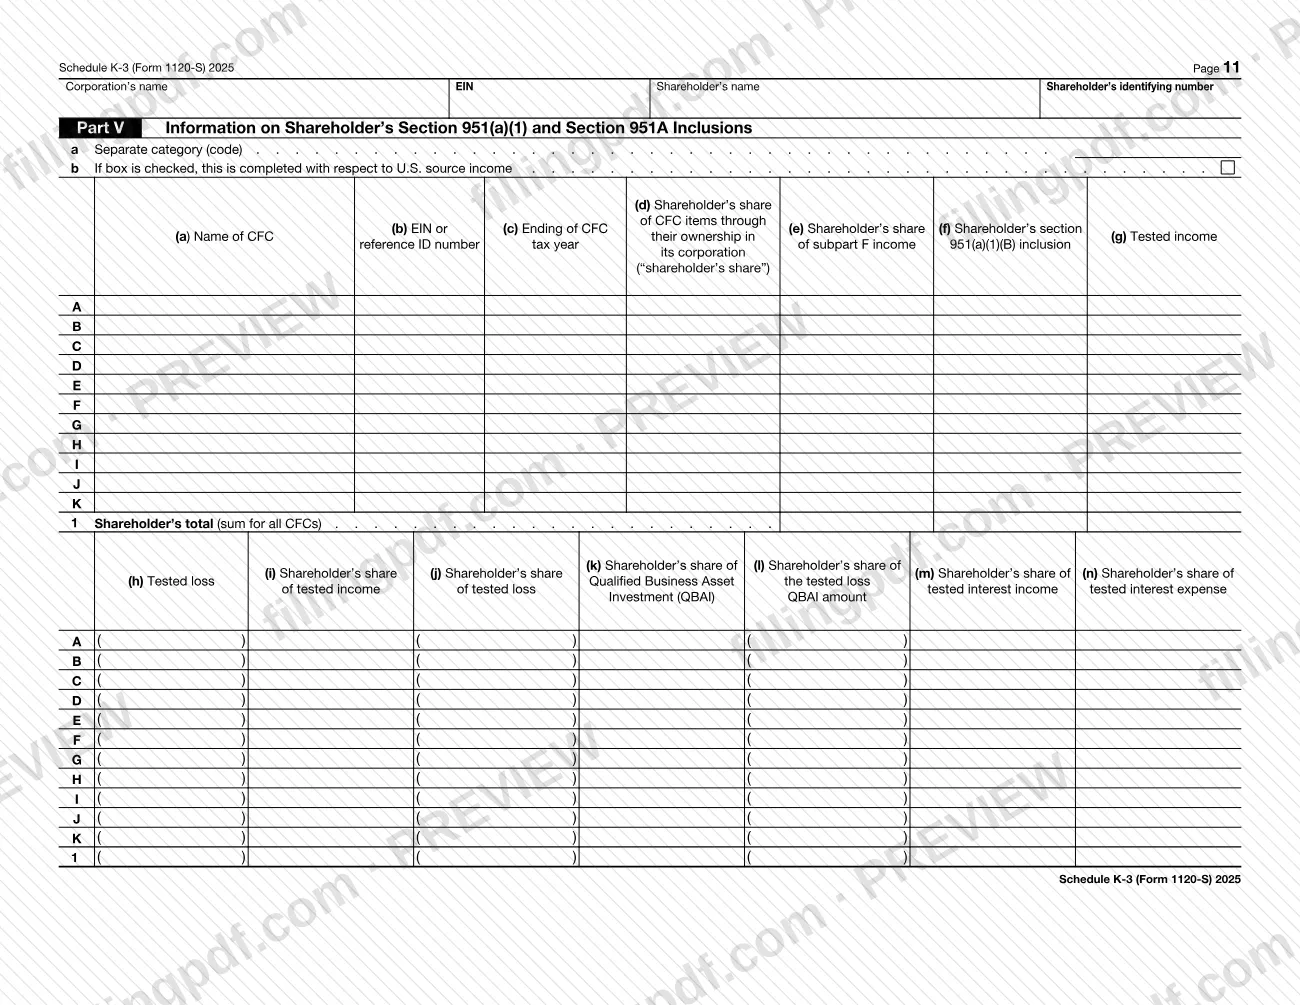
- Part V: shareholder's section 951(a)(1) and section 951A inclusions.
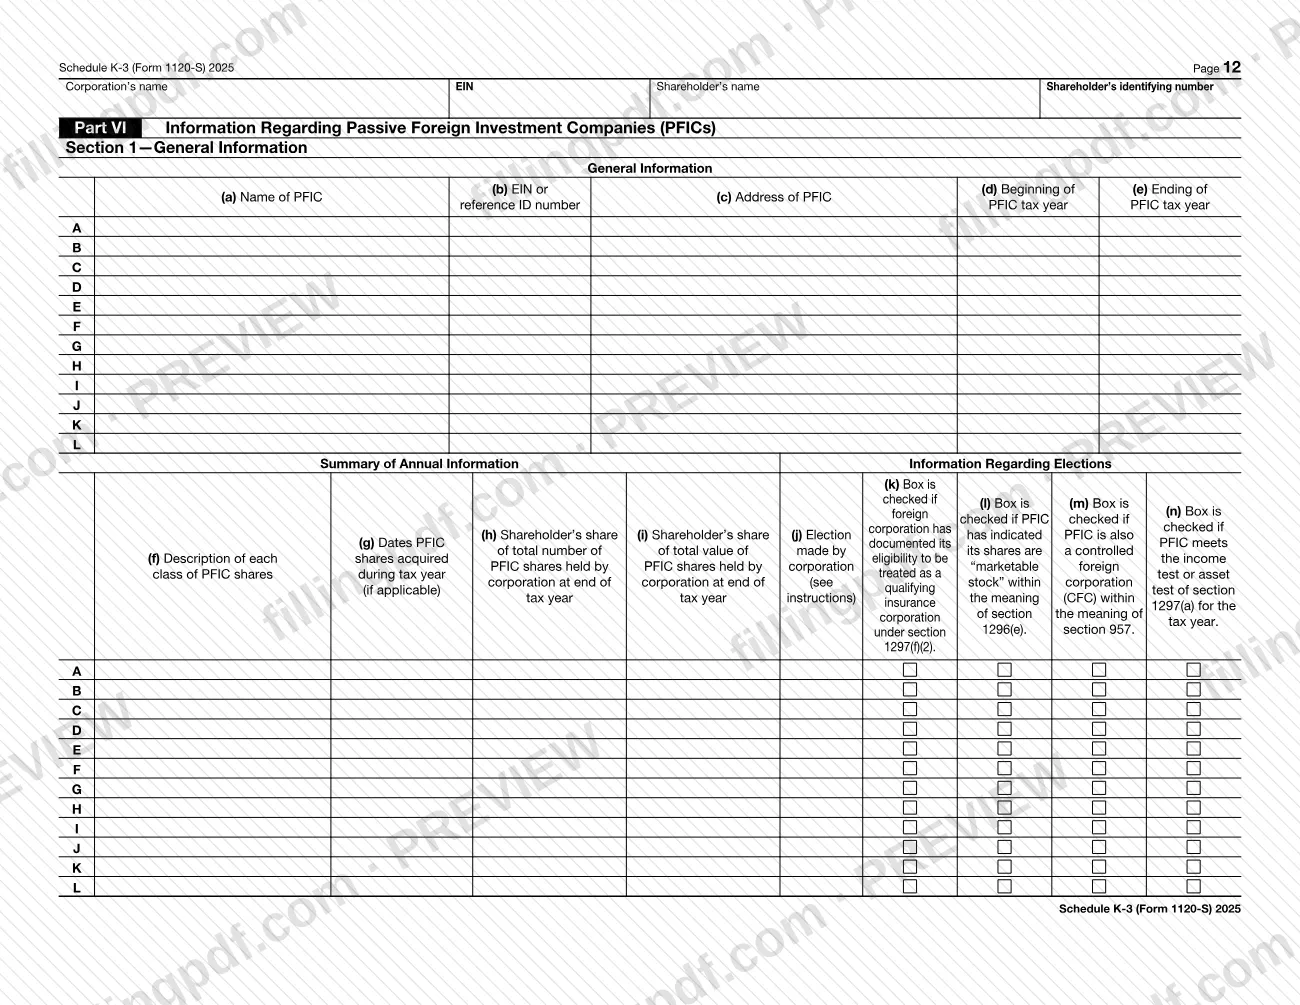
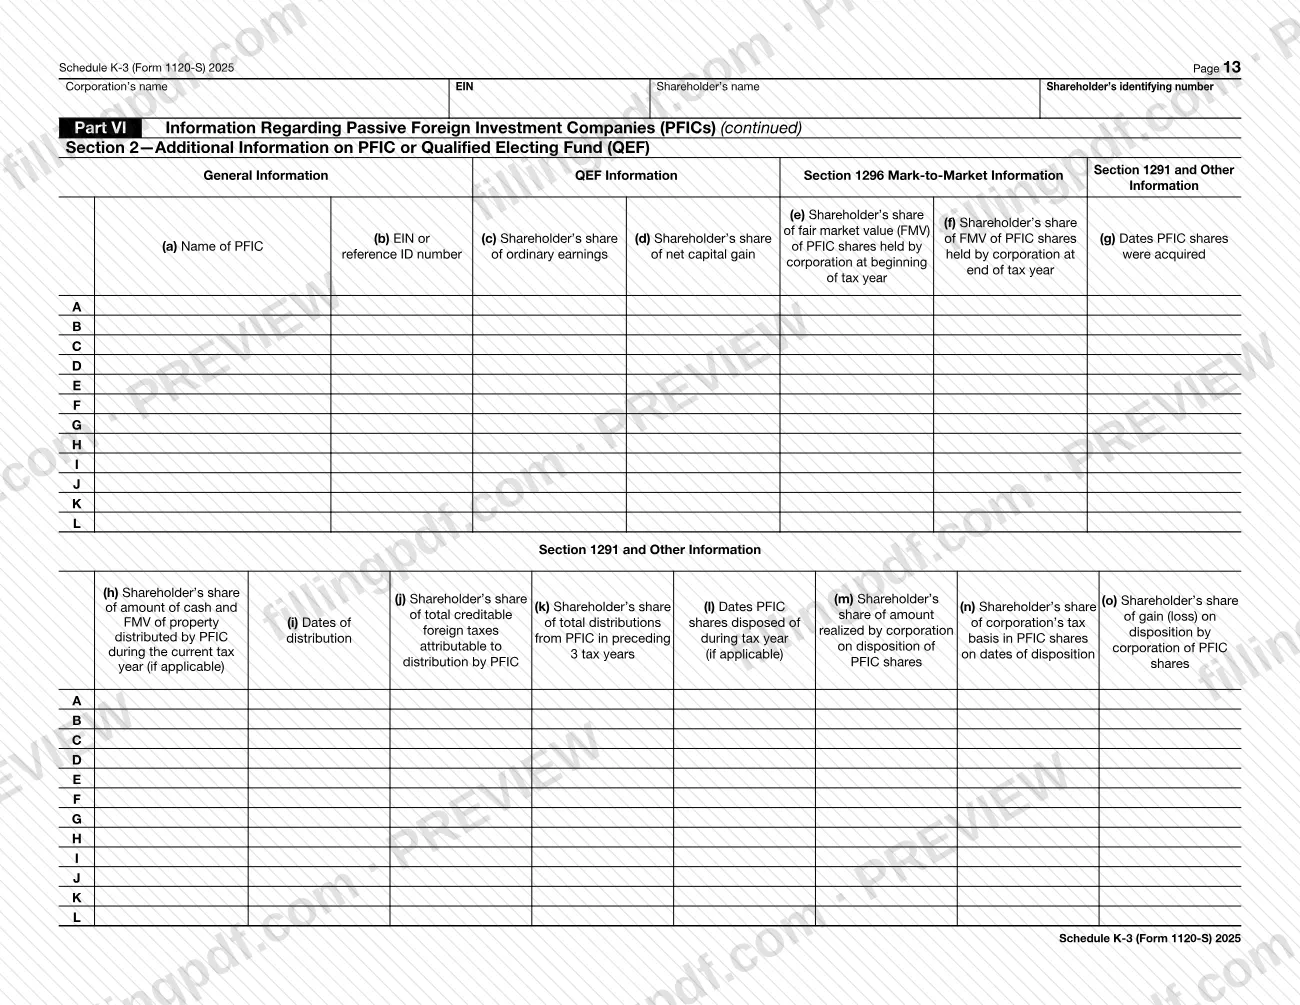
- Part VI: information on passive foreign investment companies (PFICs).
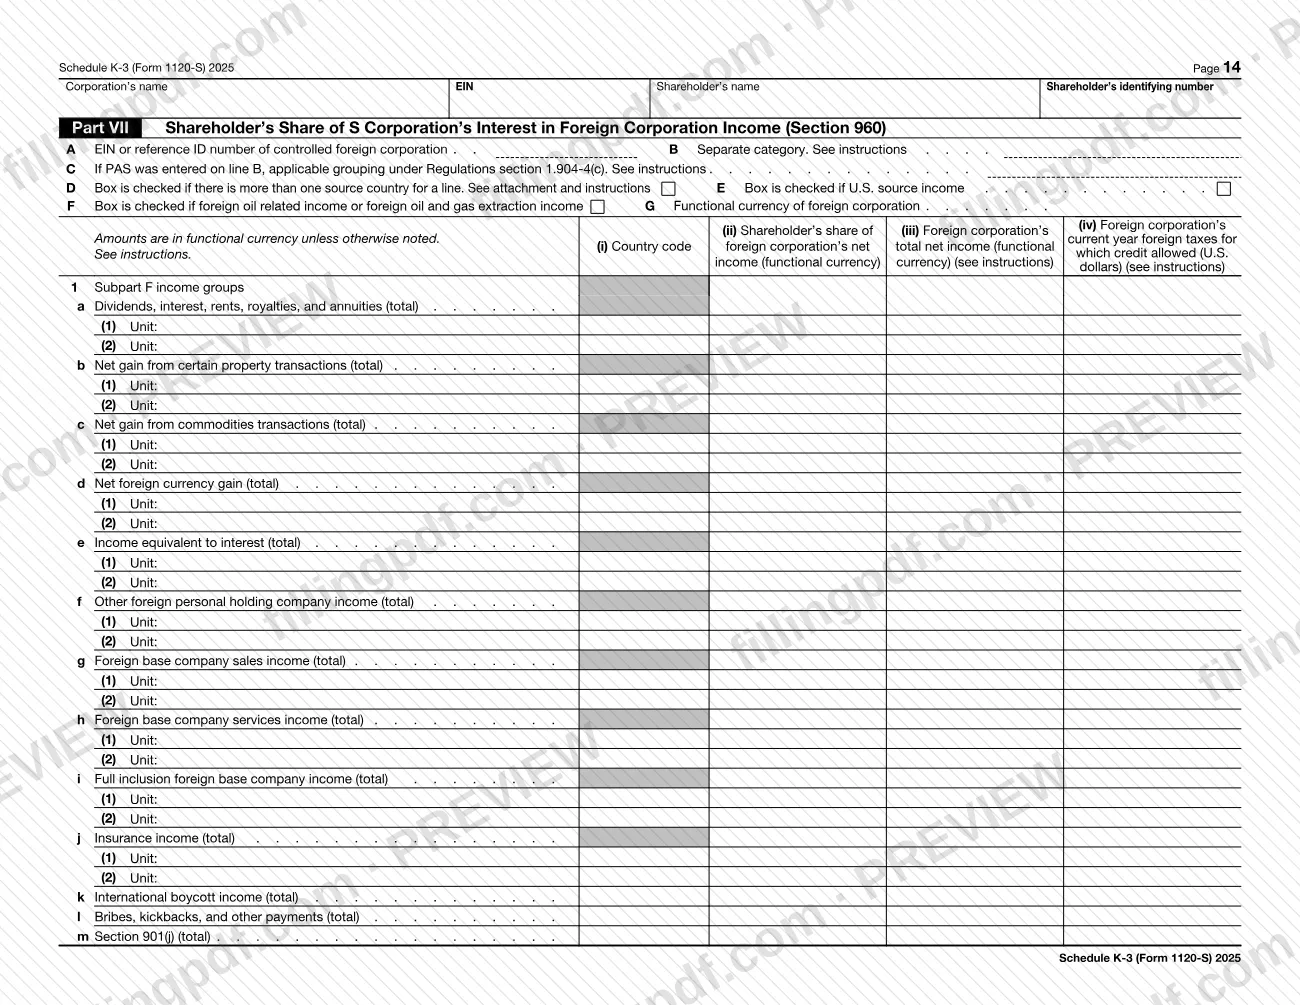
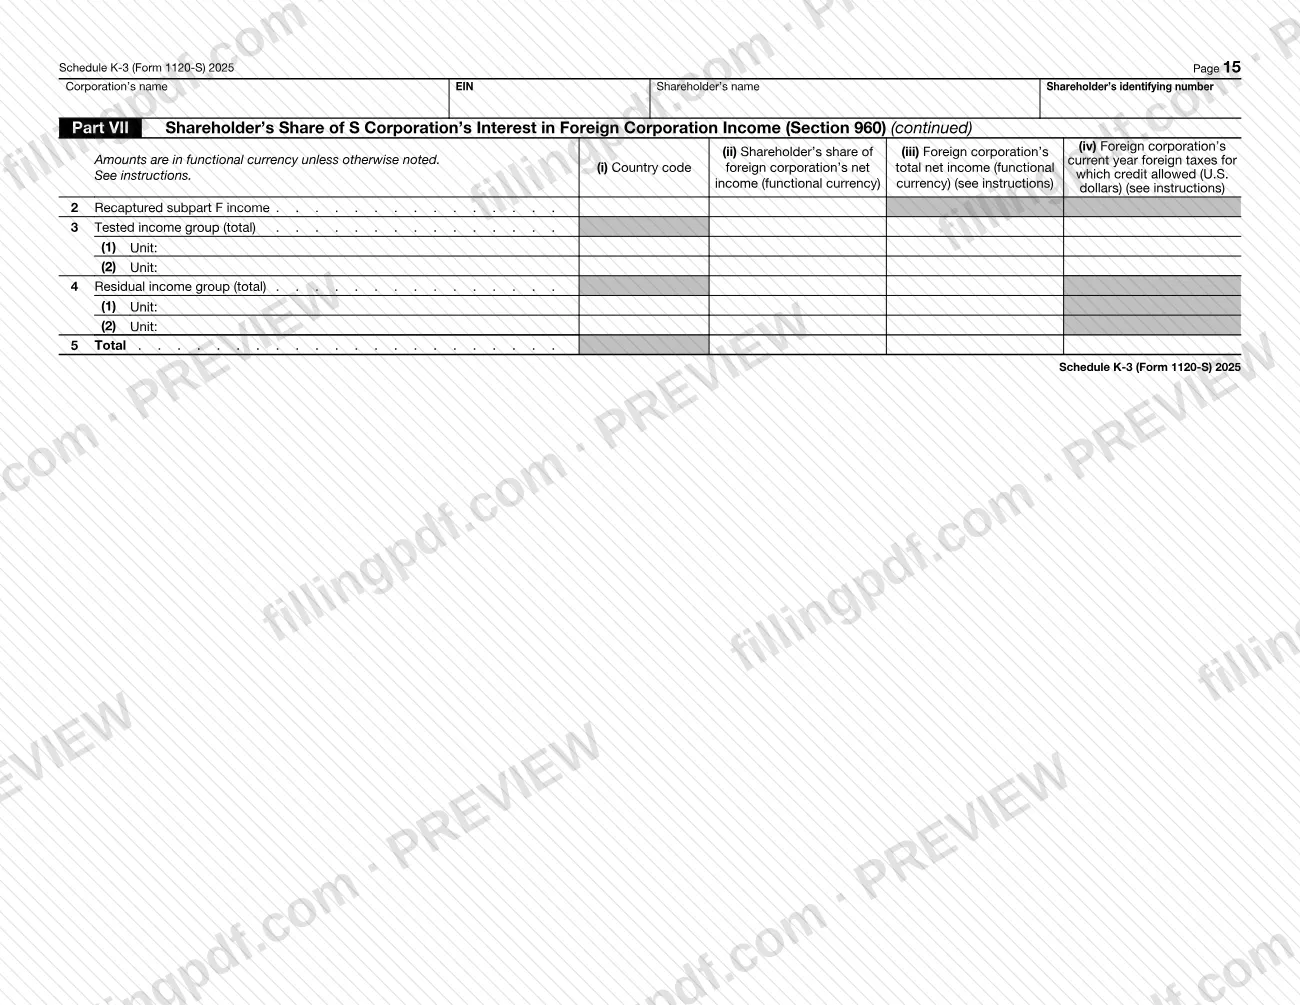
- Part VII: the shareholder's share of the S corporation's interest in foreign corporation income (section 960).
Shareholders carry the figures to Form 1116, Form 1118, Form 8992, Form 8621 and Form 1040, as the IRS instructions direct for each part.
Who needs to file Schedule K-3 (Form 1120-S)?
The main users are S corporations that report international items to their shareholders on Schedule K-3 (Form 1120-S), and the shareholders who receive it. The IRS shareholder instructions say you need only the parts that apply to you.
Shareholders use it in these situations:
- Individuals, and U.S. citizen or resident beneficiaries of certain domestic estates and trusts, who claim a foreign tax credit use Parts II and III with Form 1116.
- Shareholders who make a section 962 election also use Form 1118 for deemed paid credits, with Part VII.
- U.S. shareholders of listed controlled foreign corporations use Part V.
- Shareholders with PFICs held through the S corporation use Part VI with Form 8621.
An S corporation with no foreign source income, no assets generating foreign source income and no foreign taxes paid or accrued may still report on Schedule K-3. You might not receive the schedule if the S corporation met the domestic filing exception. You also do not need Parts II and III if you are not required to complete Form 1116, for example because you qualify for an exception to filing it. A shareholder who must file Form 1116 may request the schedule.
When to file Schedule K-3 (Form 1120-S)
Schedule K-3 (Form 1120-S) is completed for each tax year in which the S corporation has items to report to its shareholders; this edition covers calendar year 2025, or a tax year beginning in 2025 and ending in 2025. The form prints no separate due date, so its timing follows the S corporation's Form 1120-S and the Schedule K-1 it extends; the Instructions for Form 1120-S at www.irs.gov/Form1120S cover that return.
If the S corporation qualified for the domestic filing exception, it may not have prepared a Schedule K-3 for you. A shareholder who must complete Form 1116 can request one. The IRS instructions' Example 2 shows a shareholder making that request by the "1-month date," and a shareholder who does not request it receives none.
Check the Amended K-3 box in Item F when the schedule corrects one previously issued.
Documents you need
- Statements and attachments for each Part I box the S corporation checks: for example the box 3 splitter arrangement statement, the box 4 foreign tax translation statement and the box 6 statement titled "Section 267A Disallowed Deduction."
- A partially completed Schedule I (Form 1118), Reduction of Foreign Oil and Gas Taxes, attached by the S corporation when it checks box 2 for foreign oil and gas taxes.
- Attachment(s) 1 and/or 2 when box 5 (high-taxed income) is checked, and an attachment describing the items when box 13 (other international items) is checked.
- Relevant portions of Form 5471, Form 5713 or other international forms, attached to Schedule K-1 or Schedule K-3 where applicable; Forms 8858 and 8621 are covered by boxes 7 and 9.
- A statement expanding Part II when a type of income is sourced from more than three countries, since the form has only rows A, B and C.
- The attachment referenced in Part III, Section 2, lines 7 and 8 (basis in stock of 10%-owned noncontrolled foreign corporations and CFCs), and in Part VII, Item D when a line has more than one source country.
How to fill out Schedule K-3 (Form 1120-S)
Enter tax year and corporation details
At the top, enter the calendar year 2025 or the tax year beginning and ending dates. In Item A enter the corporation's employer identification number (EIN), and in Item B its name, address, city, state, and ZIP code.
Enter the shareholder's details
In Item C enter the shareholder's identifying number, and in Item D the shareholder's name, address, city, state, and ZIP code. Prepare a separate schedule for each shareholder.
Mark which parts apply in Item E
For lines 1 through 7 of Item E, check Yes or No for whether Parts I through VII apply. Check Yes only for a part you complete and attach.
Check the amended box if needed
Check Item F, Amended K-3, only if applicable. The page headers repeat the corporation's name, EIN, shareholder's name and identifying number.
Complete Part I boxes 1 through 13
Check each box that applies, such as gain on personal property sale, foreign oil and gas taxes, splitter arrangements, foreign tax translation, Form 5471, 8858, 8865 information or other international items. Attach the statements that the checked boxes call for.
Report gross income in Part II, Section 1
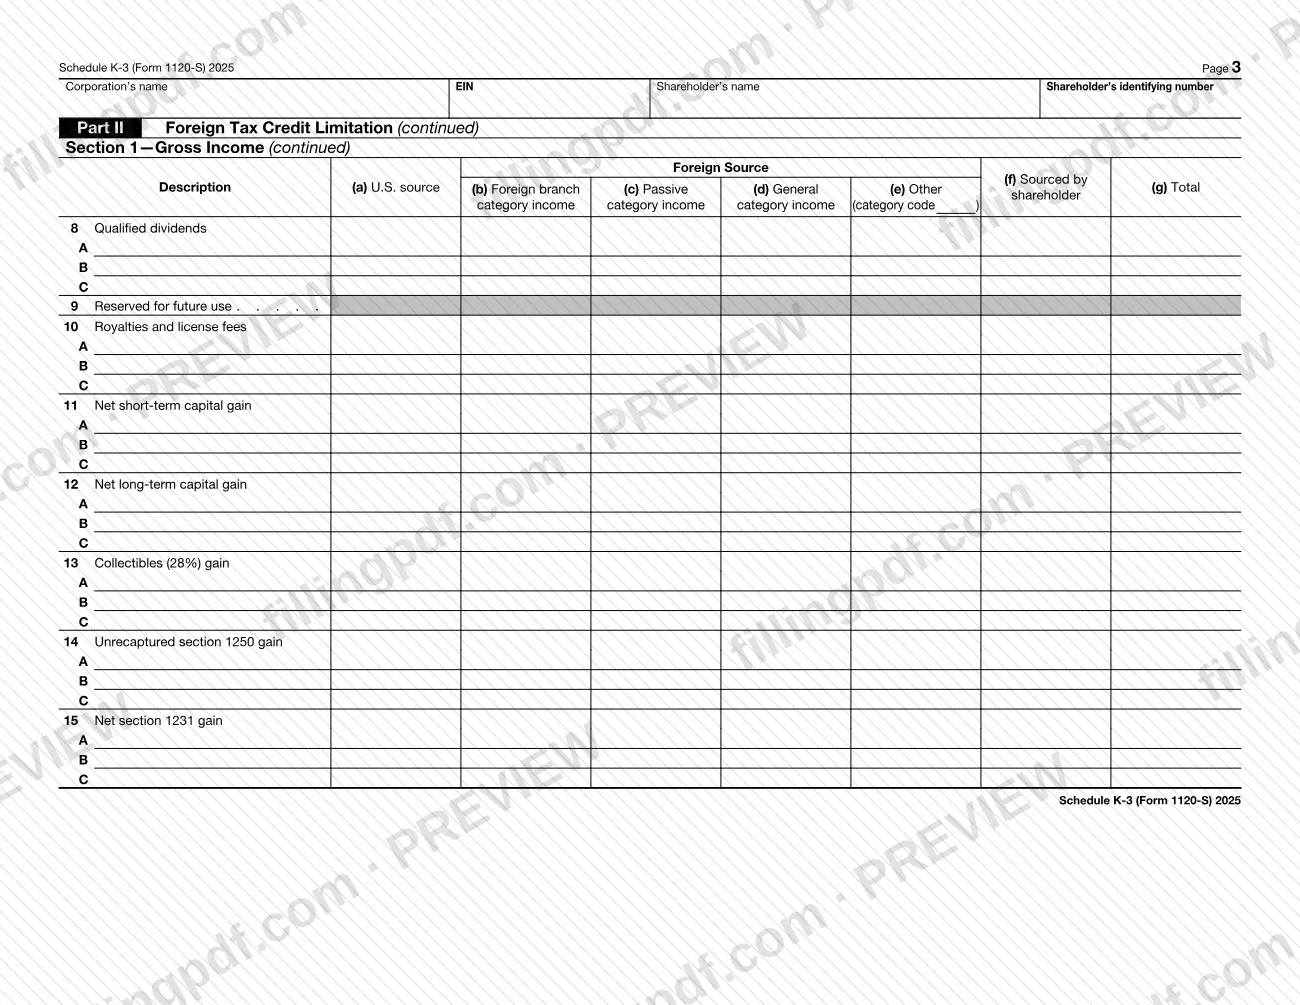
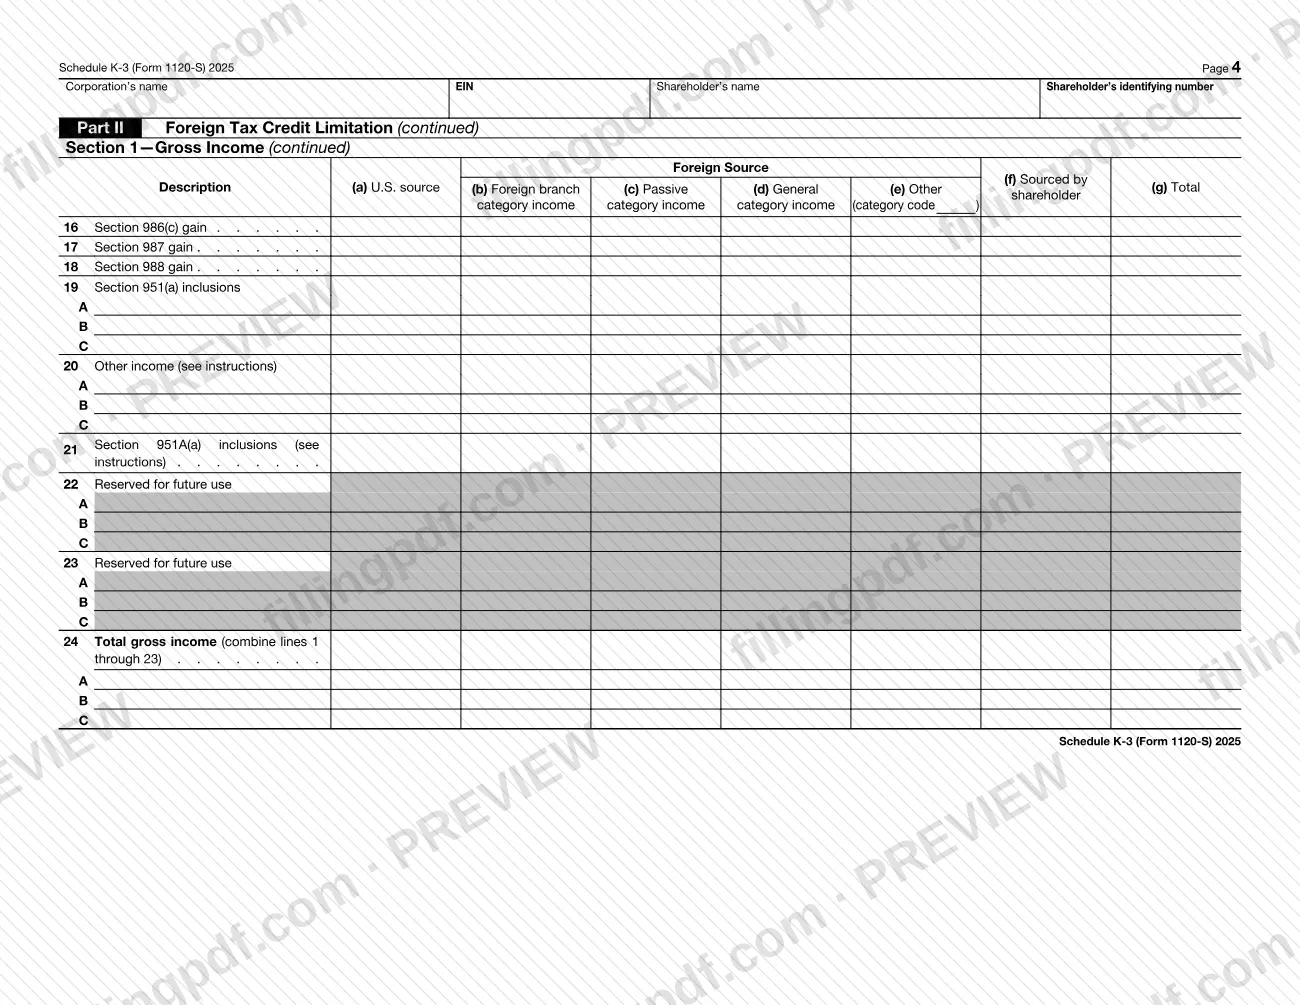
For lines 1 through 23, enter each type of income by column: (a) U.S. source, (b) foreign branch, (c) passive, (d) general, (e) other with its category code, (f) sourced by shareholder, and (g) total. Use rows A, B and C for the two-letter country code, and XX when the country cannot be determined. Combine lines 1 through 23 on line 24.
Report deductions in Part II, Section 2
Enter lines 25 through 53 in the same columns, including R&E expenses with SIC codes on line 32 and interest expense on lines 39 through 43. Line 54 combines lines 25 through 53, and line 55 is line 24 minus line 54.
Complete Part III, Sections 1 and 2
In Section 1, enter gross receipts by SIC code on line 1 and the R&E expense by activity location on line 2. In Section 2, enter asset values on lines 1 through 8; line 6a is the sum of lines 1 and 2 less the sum of lines 3, 4 and 5.
Report foreign taxes in Part III, Section 3
On line 1, list direct foreign taxes paid or accrued by type of tax and category of income. Line 2 covers reductions of taxes (lines A through G), and line 3 foreign tax redeterminations, with the related tax year, the date tax paid and the Contested tax box.
List foreign distributions in Part IV
For each distributing foreign corporation (rows A through O), enter its name, EIN or reference ID number, date of distribution, functional currency, amounts in functional currency and U.S. dollars, the spot rate and whether it is a qualified foreign corporation in column (j).
Complete the Part V CFC inclusions
Enter the separate category code on line a, check box b if completed for U.S. source income, then list each controlled foreign corporation (CFC) with its subpart F, section 951(a)(1)(B), tested income, tested loss and QBAI items. Line 1 totals all CFCs.
Enter the Part VI PFIC information
In Section 1, enter each PFIC's name, EIN or reference ID number, address, tax year, share information and election boxes. In Section 2, enter the QEF, section 1296 mark-to-market and section 1291 information on the same line for each PFIC.
Complete Part VII section 960 information
Enter the CFC's EIN or reference ID number in Item A, the separate category in Item B, and Items C through G as they apply. Then complete lines 1 through 5 by country code, with amounts in functional currency unless otherwise noted.
Review and download the completed PDF
Check that Item E matches the parts you completed, that every attachment required by a checked box is ready, and that all amounts are in U.S. dollars unless a part says otherwise. Download or print the completed PDF from FillingPDF.
How to submit Schedule K-3 (Form 1120-S)
Schedule K-3 (Form 1120-S) has no filing channel of its own: the form prints no mailing address, online portal or appointment rule. It is a schedule of the S corporation's Form 1120-S, so how the return is filed is covered in the Instructions for Form 1120-S at www.irs.gov/Form1120S.
- From the S corporation to the shareholder: the S corporation completes a schedule for each shareholder, with the corporation's information in Items A and B and the shareholder's in Items C and D. Where a box is checked or a column asks for an attachment, the statement or form must accompany the schedule.
- By the shareholder: you do not file Schedule K-3 on its own. You carry its figures to your own return and forms, such as Form 1116, Form 1118, Form 8992, Form 8621 and Form 1040, following the part-by-part instructions.
If you need details that are not on the schedule, such as information from Form 8858 or Form 8621, the instructions say to request it from the S corporation. FillingPDF lets you fill out and download the PDF; submission follows the IRS channels that apply to Form 1120-S.
Common mistakes to avoid
- Reporting amounts from Part II, column (a) U.S. source on Form 1116 or Form 1118; the instructions say not to do so unless you elect to re-source the income under an applicable U.S. income tax treaty.
- Treating all S corporation income as U.S. source and all expenses as reducing U.S. source income; column (f) amounts are sourced by the shareholder, and some expenses are allocated and apportioned by the shareholder.
- Putting charitable contributions (Part II, line 38) on Form 1116; the instructions say they are allocable to U.S. source income.
- Claiming a Form 1116 foreign tax credit for line 45 amounts (foreign taxes not creditable but deductible); you may deduct them but not credit them.
- Deducting an amount listed in the box 6 statement as a disallowed section 267A deduction, for example on lines 41 through 43.
- Ignoring a splitter arrangement because box 3 is unchecked; the instructions say the shareholder must identify one even if the S corporation did not.
- Including gains from lines 13, 14 or 15 in line 12, or losses from line 29 in line 28; the instructions say those lines exclude them.
- Entering country information in the wrong format: use the two-letter code from IRS.gov/CountryCodes, or XX when the country cannot be determined.
- Not filing Form 8082 when the actual treatment of an item differs from what the S corporation assumed, for example on ownership thresholds.
Frequently asked questions
What is Schedule K-3 (Form 1120-S)?
Schedule K-3 (Form 1120-S) is the IRS schedule an S corporation uses to report to each shareholder the shareholder's share of international items. It extends Schedule K-1 (Form 1120-S) and generally reports the shareholder's share of the items reported on Schedule K-2.
Do I need Schedule K-3 if my S corporation has no foreign activity?
Not always. The IRS instructions say you may not receive one if the S corporation met the domestic filing exception. But if you must complete Form 1116 to claim a foreign tax credit, you generally need the information in Parts II and III and may request the schedule.
How do I know which parts of Schedule K-3 apply?
Check Item E on page 1. The S corporation marks Yes for each part that applies and completes and attaches it, and No for the others. The instructions say you only need to use the parts that apply to you.
What do I do with Part II of Schedule K-3 on Form 1116?
Add the foreign source amounts in columns (b) through (e) to your other income in each separate category. Those completing Form 1116 report line 24, after any section 904(b)(2) and PTEP adjustments, by country on Form 1116, Part I, line 1a, as the instructions describe.
What does column (f), Sourced by shareholder, mean?
It holds income for which you determine the source and separate category. The instructions say it generally concerns sales of personal property other than inventory, depreciable property and certain intangibles, sourced under section 865, and can include section 988 foreign currency gain.
What is Part VII of Schedule K-3 used for?
Part VII reports the shareholder's share of the S corporation's interest in foreign corporation income under section 960. Shareholders who make a section 962 election use it to figure deemed paid foreign tax credits on Form 1118, Schedules C and D.
What if my actual tax treatment differs from what the S corporation reported?
Treat the items according to your actual facts. The instructions say that if the S corporation's assumptions, such as ownership thresholds or relatedness, were incorrect, you must file Form 8082, Notice of Inconsistent Treatment or Administrative Adjustment Request (AAR), to identify and explain the inconsistency.
Can I fill out Schedule K-3 (Form 1120-S) online?
Yes. You can fill out the fillable PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the schedule with the IRS; filing follows the channels in the Instructions for Form 1120-S.
Ready to fill out Schedule K-3 (Form 1120-S)?
Fill out Schedule K-3 (Form 1120-S) now