
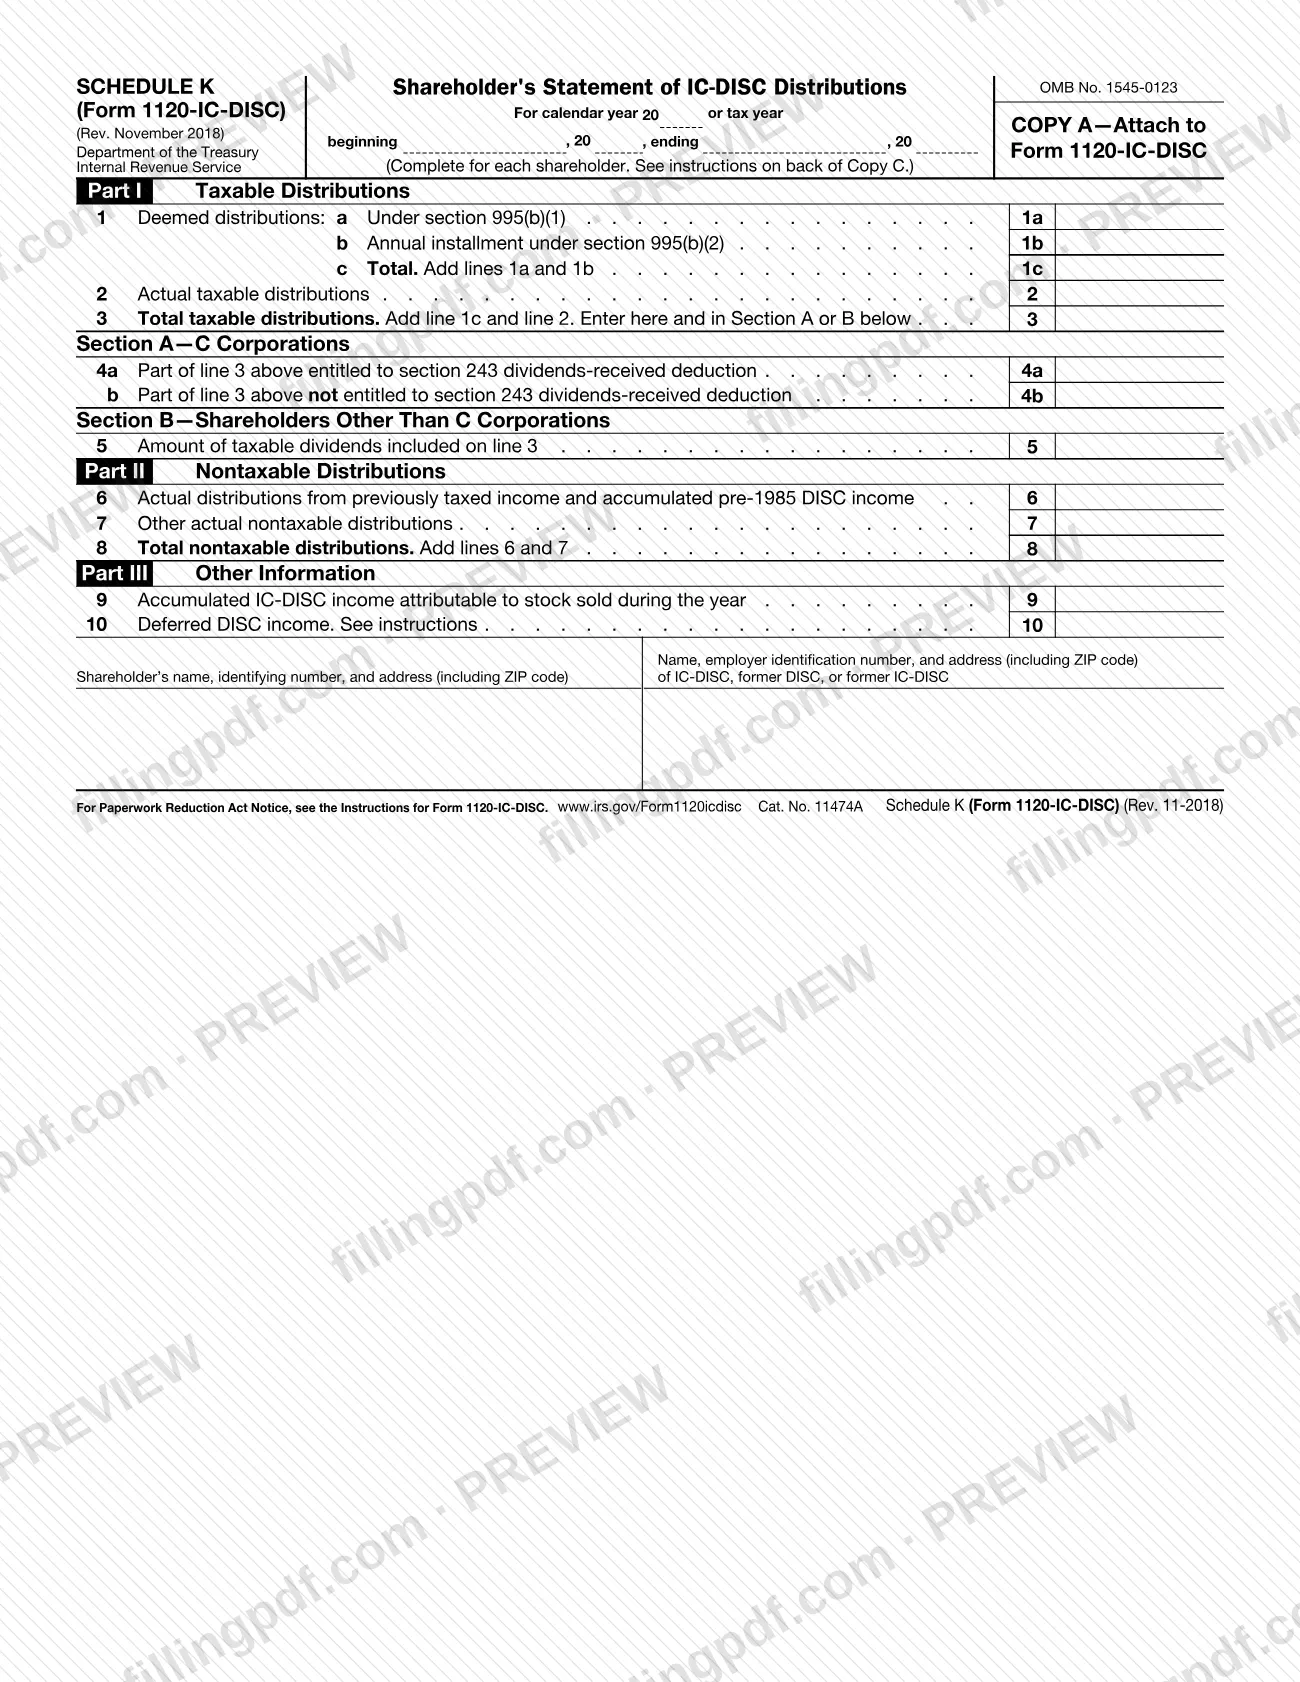
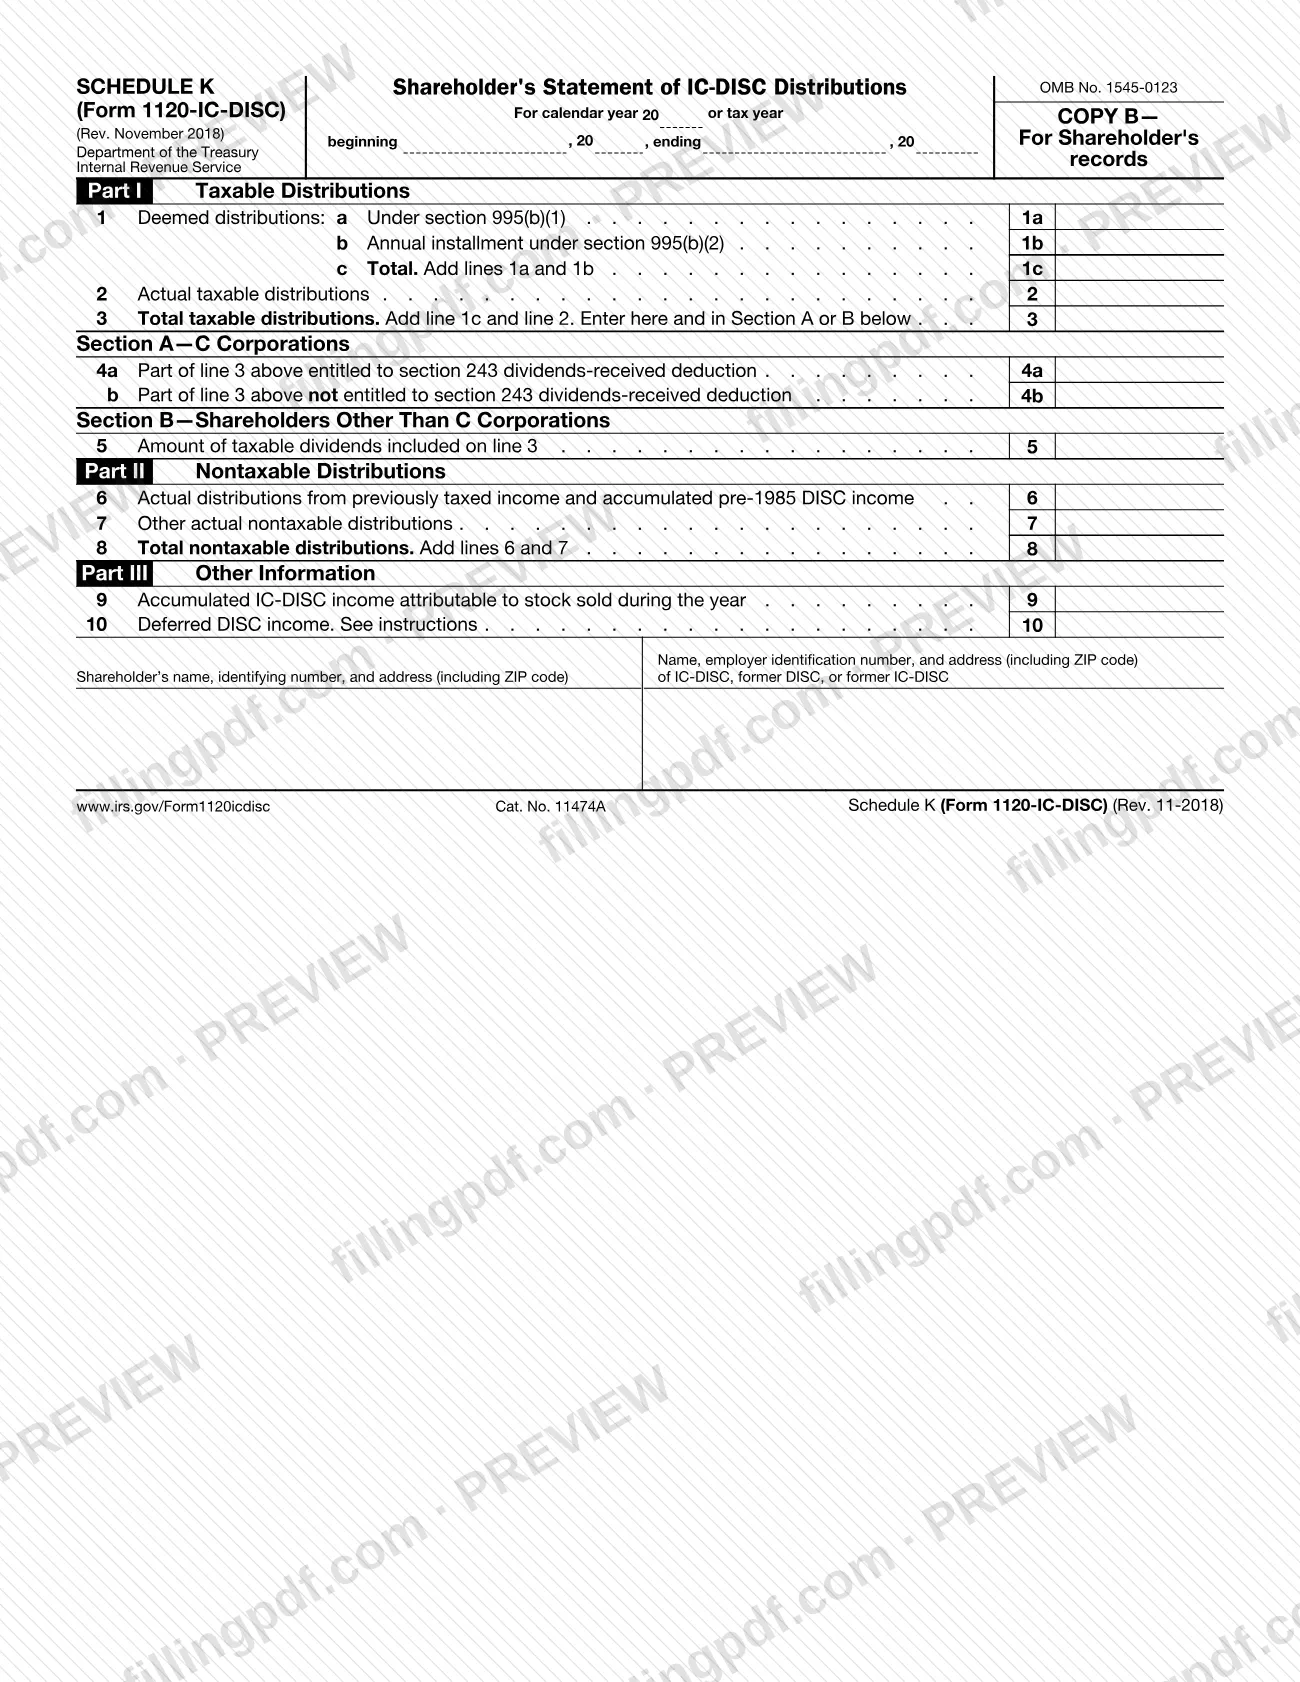
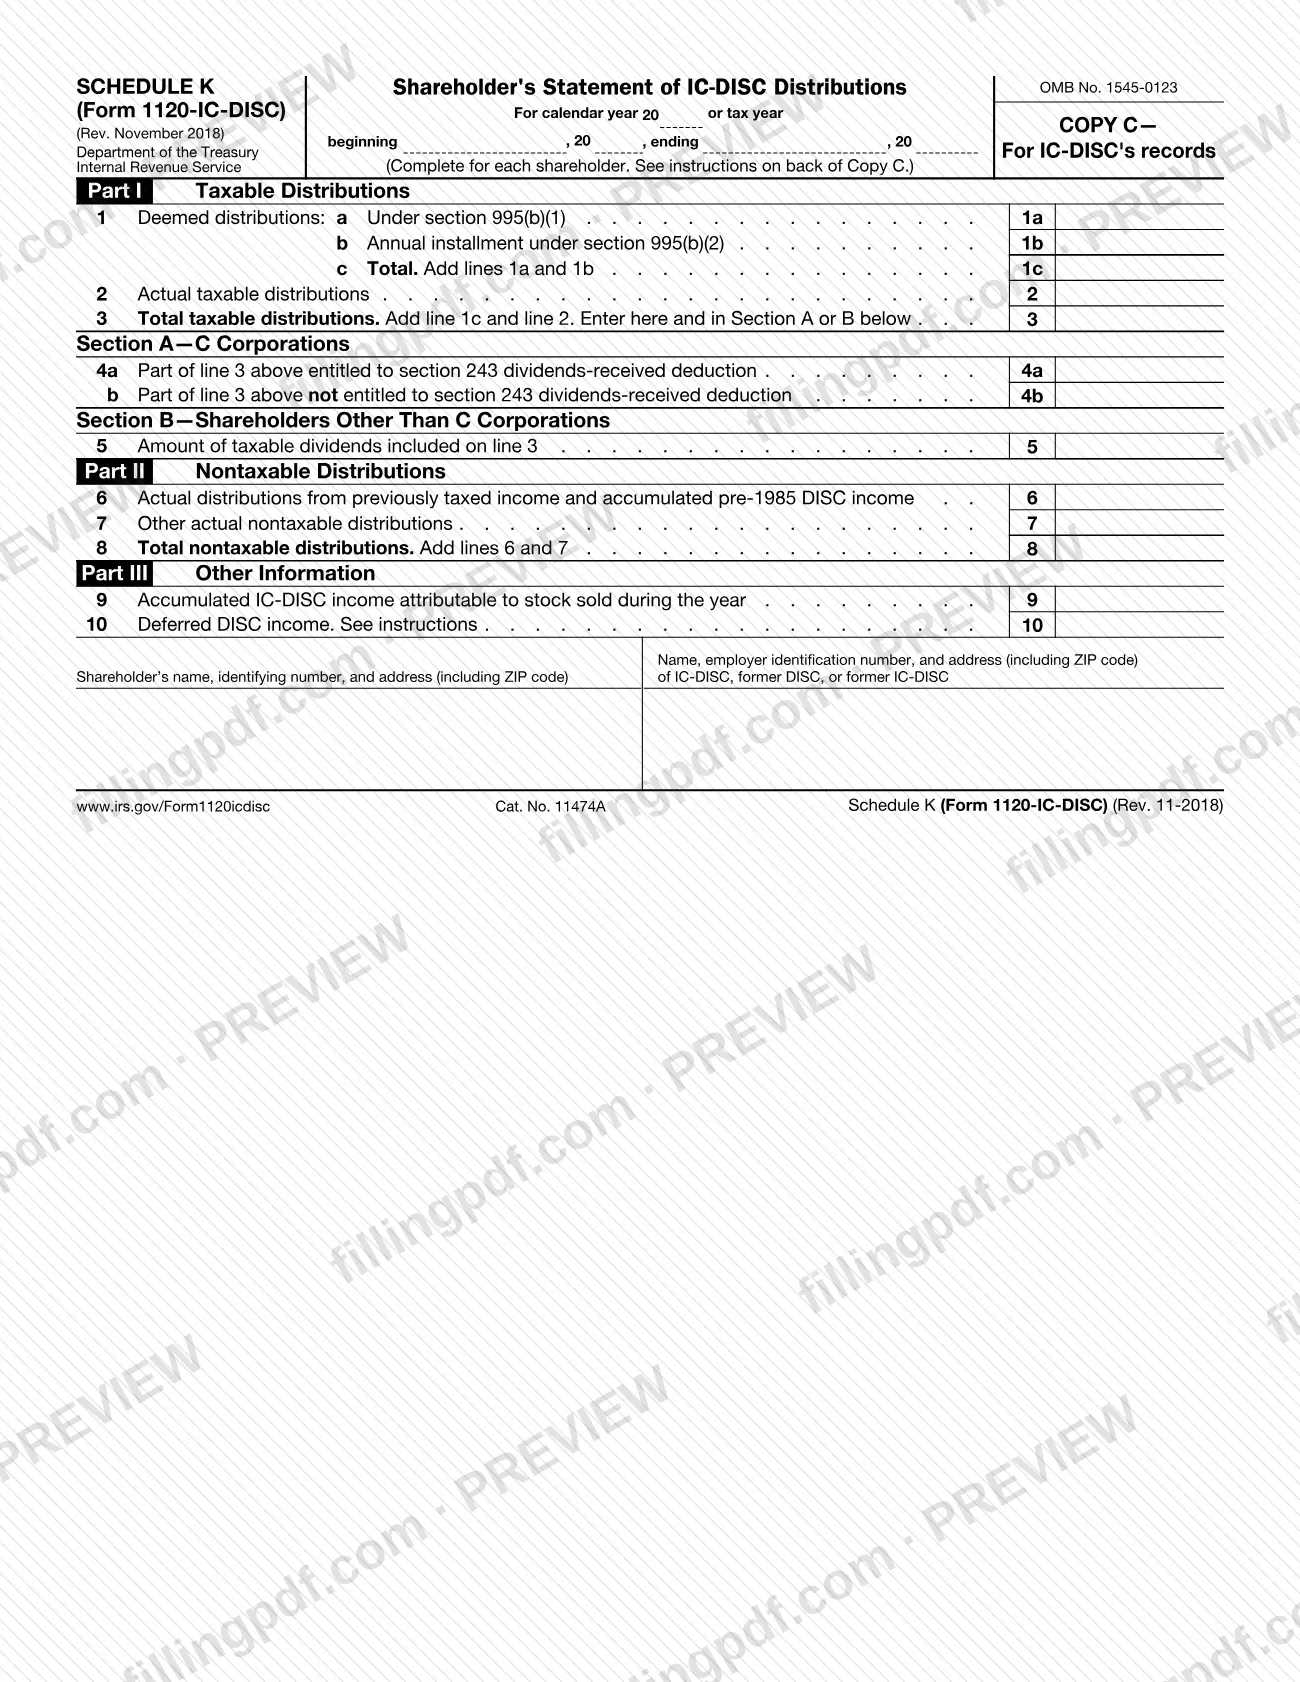
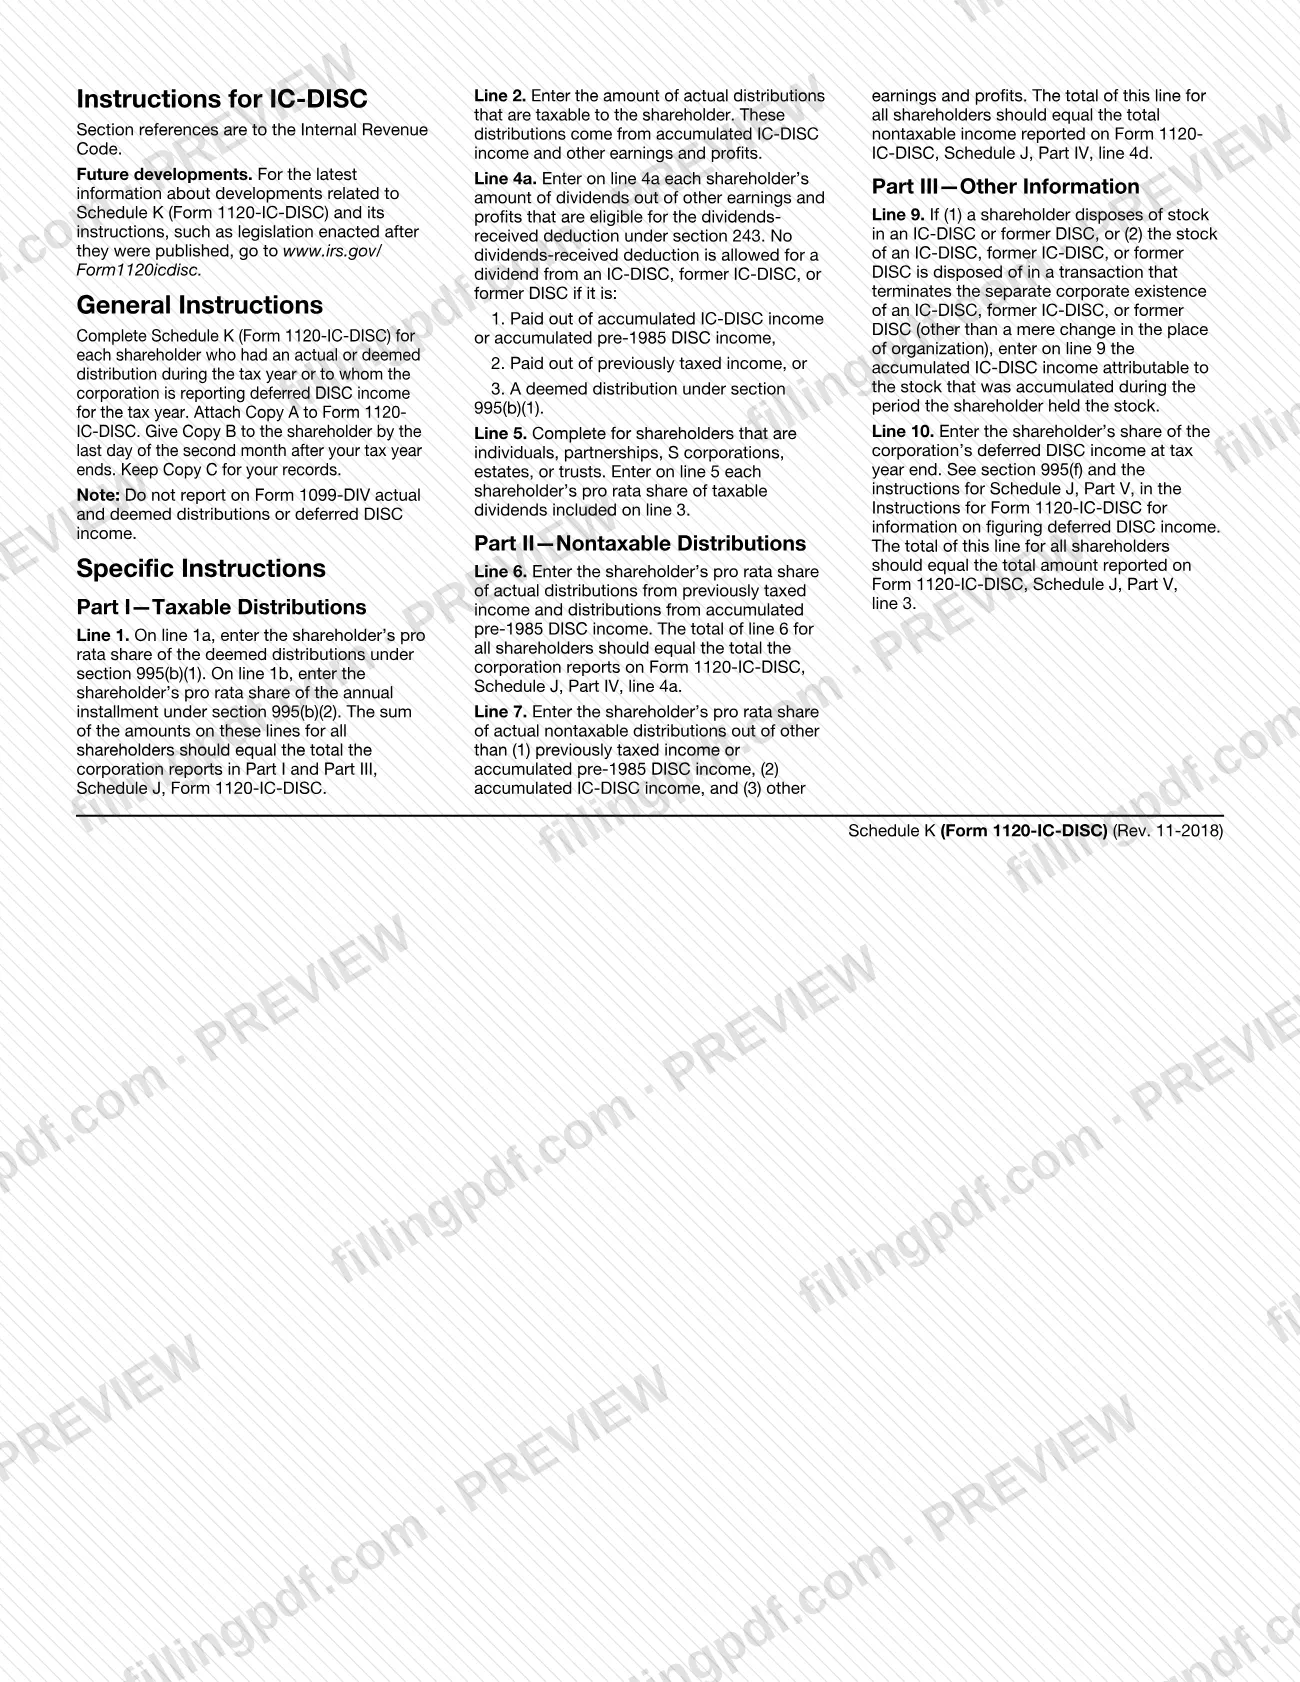
Schedule K (Form 1120-IC-DISC), Shareholder's Statement of IC-DISC Distributions, is the Internal Revenue Service (IRS) schedule that reports each shareholder's actual and deemed distributions from an IC-DISC, former IC-DISC or former DISC, and any deferred DISC income. The IC-DISC completes one for each shareholder and files Copy A with Form 1120-IC-DISC; the shareholder receives Copy B. On this page you can fill out the form online on FillingPDF and download or print the completed PDF. The official PDF is published by the IRS at irs.gov.
Last updated
What is Schedule K (Form 1120-IC-DISC)?
Schedule K (Form 1120-IC-DISC), Shareholder's Statement of IC-DISC Distributions, is the IRS schedule on which an IC-DISC reports, for one shareholder, the taxable and nontaxable distributions made during the year and the shareholder's share of deferred DISC income.
The schedule is part of Form 1120-IC-DISC (OMB No. 1545-0123) and is identified by that form number. It is printed in three copies:
- Copy A is attached to Form 1120-IC-DISC.
- Copy B is for the shareholder's records.
- Copy C is for the IC-DISC's records.
The form has three parts. Part I, Taxable Distributions covers deemed distributions under section 995(b)(1) and the annual installment under section 995(b)(2) (line 1), actual taxable distributions (line 2), the total (line 3), and a split by shareholder type: Section A for C corporations (lines 4a and 4b, the section 243 dividends-received deduction) and Section B for other shareholders (line 5, taxable dividends). Part II, Nontaxable Distributions has lines 6 to 8. Part III, Other Information reports accumulated IC-DISC income attributable to stock sold during the year (line 9) and deferred DISC income (line 10).
The totals for all shareholders must agree with Schedule J of Form 1120-IC-DISC. Distributions and deferred DISC income reported here are not reported on Form 1099-DIV.
Who needs to file Schedule K (Form 1120-IC-DISC)?
The IC-DISC completes Schedule K (Form 1120-IC-DISC) for each shareholder who had an actual or deemed distribution during the tax year, or for whom the corporation is reporting deferred DISC income for the year. One schedule is prepared per shareholder, not one for the whole corporation.
Which section the shareholder uses depends on type:
- C corporations use Section A, lines 4a and 4b.
- Individuals, partnerships, S corporations, estates and trusts use Section B, line 5.
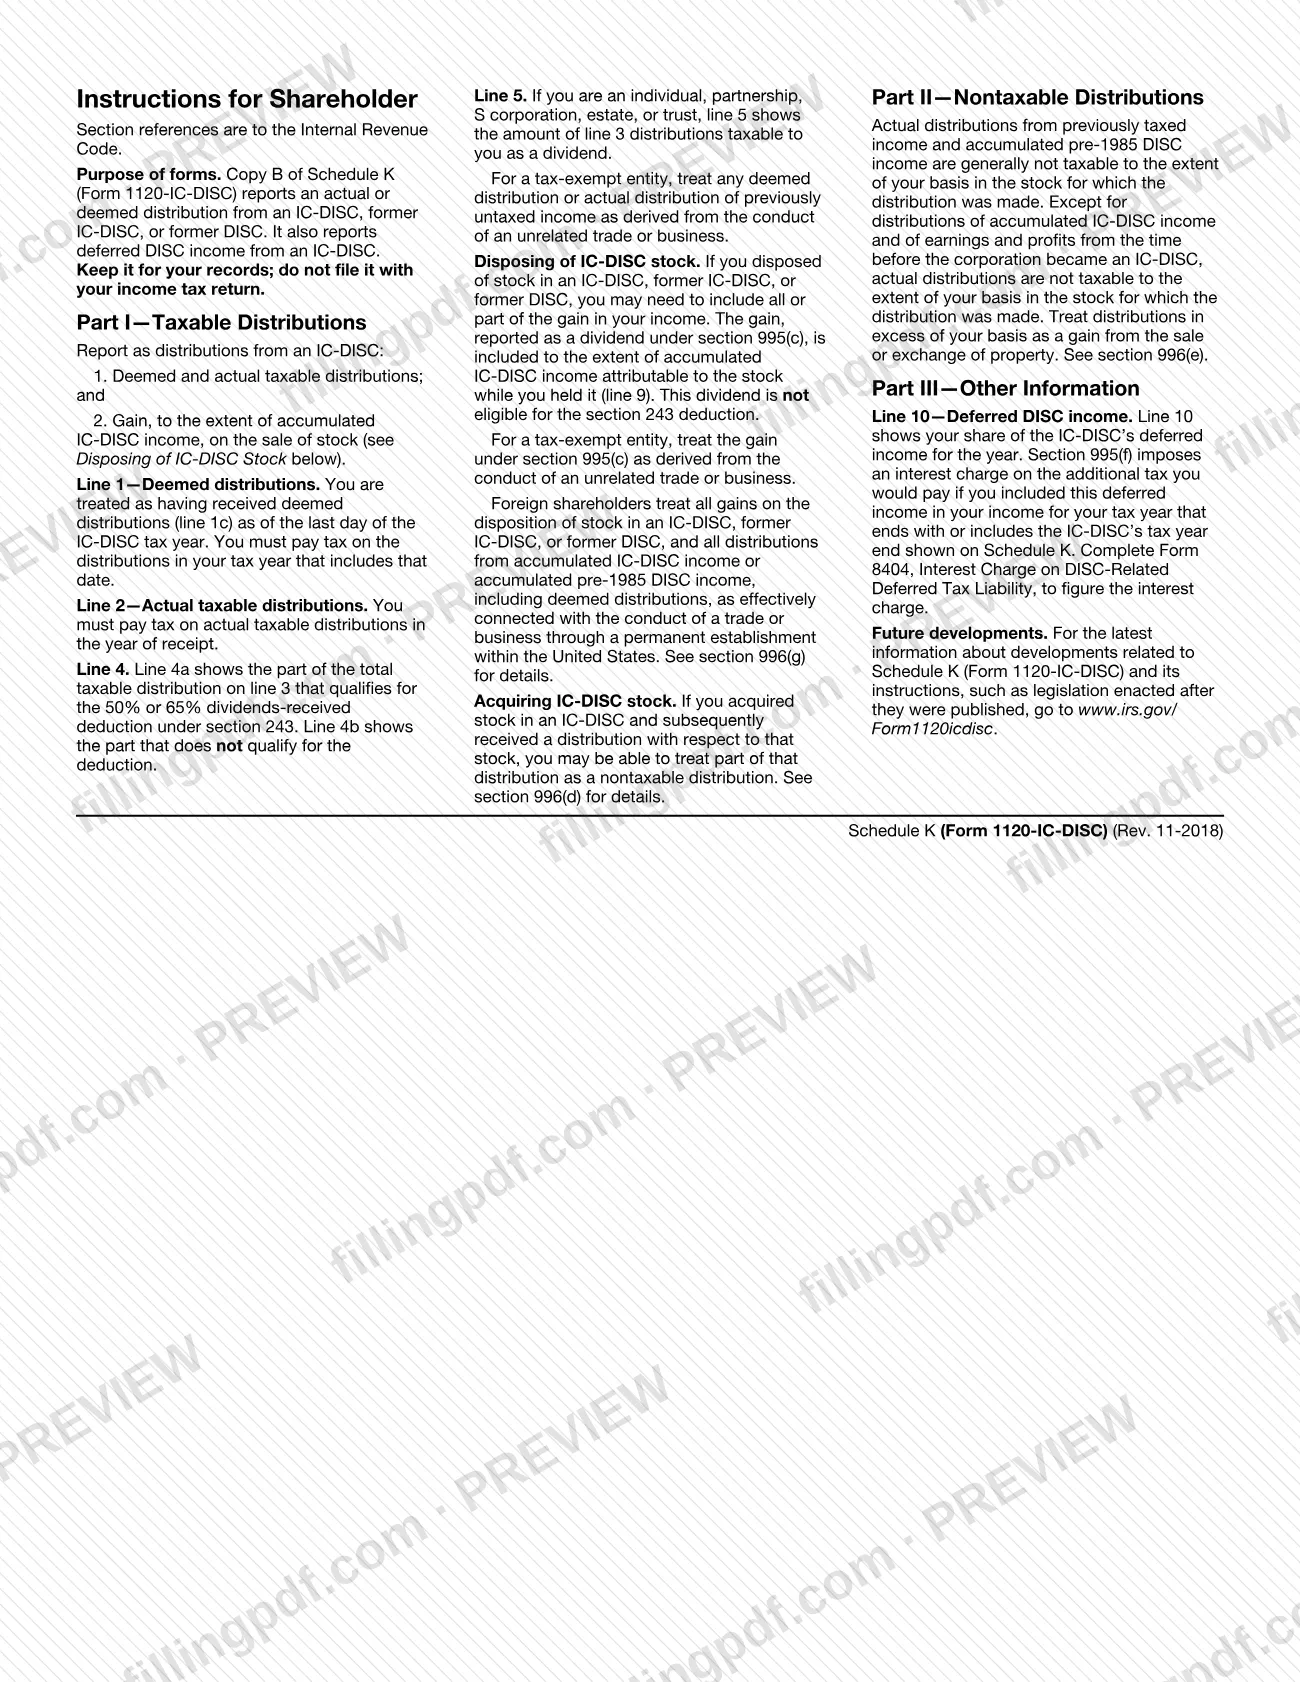
Shareholders are the recipients of Copy B. The shareholder instructions on the form say Copy B reports an actual or deemed distribution from an IC-DISC, former IC-DISC or former DISC, and deferred DISC income from an IC-DISC. Shareholders who disposed of stock, who are tax-exempt entities or who are foreign shareholders should read the shareholder instructions printed on the back of Copy B, because they describe special treatment of gain and distributions.
A shareholder with no distribution and no deferred DISC income for the year does not need a schedule.
When to file Schedule K (Form 1120-IC-DISC)
Schedule K is completed with Form 1120-IC-DISC for the tax year in which a shareholder had an actual or deemed distribution, or for which deferred DISC income is reported. Copy A is attached to the Form 1120-IC-DISC, so it travels with the return and has no separate filing date.
Give Copy B to the shareholder by the last day of the second month after the IC-DISC's tax year ends. Keep Copy C for the corporation's records.
For the shareholder, deemed distributions on line 1c are treated as received on the last day of the IC-DISC tax year, and tax is due in the shareholder's tax year that includes that date. Actual taxable distributions on line 2 are taxed in the year of receipt.
How to fill out Schedule K (Form 1120-IC-DISC)
Enter the tax year and names
Fill in the calendar year, or the tax year beginning and ending dates. Enter the shareholder's name, identifying number and address (including ZIP code) and the name, identifying number and address of the IC-DISC, former DISC or former IC-DISC in the blocks the form provides.
Report deemed distributions on line 1
On line 1a enter the shareholder's pro rata share of deemed distributions under section 995(b)(1). On line 1b enter the pro rata share of the annual installment under section 995(b)(2), then add them on line 1c.
Enter actual taxable distributions
On line 2 enter actual distributions taxable to the shareholder. They come from accumulated IC-DISC income and other earnings and profits.
Total the taxable distributions
On line 3 add line 1c and line 2, then carry the result into Section A or Section B, depending on the shareholder type.
Complete Section A for C corporations
On line 4a enter the part of line 3 eligible for the section 243 dividends-received deduction. On line 4b enter the part that is not.
Complete Section B for other shareholders
For an individual, partnership, S corporation, estate or trust, enter on line 5 the shareholder's pro rata share of taxable dividends included on line 3.
Enter nontaxable distributions
Line 6: pro rata share of actual distributions from previously taxed income and accumulated pre-1985 DISC income. Line 7: other actual nontaxable distributions, apart from those on line 6 and from accumulated IC-DISC income. Add lines 6 and 7 on line 8.
Report stock-sale income on line 9
Complete line 9 if the shareholder disposed of stock, or the stock was disposed of in a transaction that ended the corporation's separate existence. Enter the accumulated IC-DISC income attributable to the stock for the period the shareholder held it.
Enter deferred DISC income on line 10
Enter the shareholder's share of the corporation's deferred DISC income at tax year end. See the Schedule J, Part V instructions in the Instructions for Form 1120-IC-DISC.
Check totals against Schedule J
Add each line for all shareholders and compare the totals with the Schedule J amounts named in the instructions for lines 1, 6, 7 and 10.
Review and download the completed PDF
Check each line, then download or print the completed PDF from FillingPDF. Attach Copy A to Form 1120-IC-DISC, give Copy B to the shareholder and keep Copy C.
How to submit Schedule K (Form 1120-IC-DISC)
Schedule K (Form 1120-IC-DISC) has no filing channel of its own; each of its three copies goes to a different place.
- Copy A: attach it to Form 1120-IC-DISC and send it with that return. The schedule prints no mailing address or portal; for how and where the return is filed, see the Instructions for Form 1120-IC-DISC at www.irs.gov/Form1120icdisc.
- Copy B: give it to the shareholder by the last day of the second month after your tax year ends. The shareholder keeps it and does not file it with an income tax return.
- Copy C: keep it with the IC-DISC's records.
Do not report these distributions or deferred DISC income on Form 1099-DIV. A shareholder who has deferred DISC income completes Form 8404, Interest Charge on DISC-Related Deferred Tax Liability, to figure the interest charge.
FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Preparing one Schedule K for the whole corporation instead of one for each shareholder with an actual or deemed distribution or deferred DISC income.
- Filing Copy B with the shareholder's income tax return; the instructions say the shareholder keeps it for records.
- Reporting these distributions or deferred DISC income on Form 1099-DIV, which the instructions say not to do.
- Giving Copy B to the shareholder after the last day of the second month following the end of the IC-DISC's tax year.
- Forgetting to attach Copy A to Form 1120-IC-DISC.
- Completing line 5 for a C corporation, or lines 4a and 4b for an individual, partnership, S corporation, estate or trust; Section A and Section B are for different shareholders.
- Using line 4a for a dividend that gets no section 243 deduction, such as one paid out of accumulated IC-DISC income, previously taxed income or accumulated pre-1985 DISC income.
- Entering shareholder amounts on lines 1, 6, 7 or 10 whose totals do not match the related Schedule J lines of Form 1120-IC-DISC.
Frequently asked questions
What is Schedule K (Form 1120-IC-DISC)?
It is the IRS Shareholder's Statement of IC-DISC Distributions. The IC-DISC completes one for each shareholder to report taxable and nontaxable distributions, income from stock sold during the year and deferred DISC income. Copy A is attached to Form 1120-IC-DISC.
Do I file Schedule K with my own income tax return?
No. The shareholder instructions say Copy B is for your records and should not be filed with your income tax return. The IC-DISC attaches Copy A to its own Form 1120-IC-DISC.
When must the IC-DISC give Copy B to shareholders?
By the last day of the second month after the IC-DISC's tax year ends. Copy A goes with Form 1120-IC-DISC, and the IC-DISC keeps Copy C for its records.
Should I report IC-DISC distributions on Form 1099-DIV?
No. The instructions state that actual and deemed distributions and deferred DISC income are not reported on Form 1099-DIV. They are reported to the shareholder on Schedule K (Form 1120-IC-DISC).
Which line do I use as a C corporation or as an individual shareholder?
C corporations use Section A, lines 4a and 4b, to split line 3 by eligibility for the section 243 dividends-received deduction. Individuals, partnerships, S corporations, estates and trusts use Section B, line 5, for taxable dividends.
What is line 10, deferred DISC income, and is there an interest charge?
Line 10 shows the shareholder's share of the IC-DISC's deferred DISC income at tax year end. Section 995(f) imposes an interest charge on the added tax from including it, and the shareholder figures it on Form 8404.
Can I fill out Schedule K (Form 1120-IC-DISC) online?
Yes. You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the schedule with the IRS; Copy A goes in with Form 1120-IC-DISC.
Ready to fill out Schedule K (Form 1120-IC-DISC)?
Fill out Schedule K (Form 1120-IC-DISC) now