
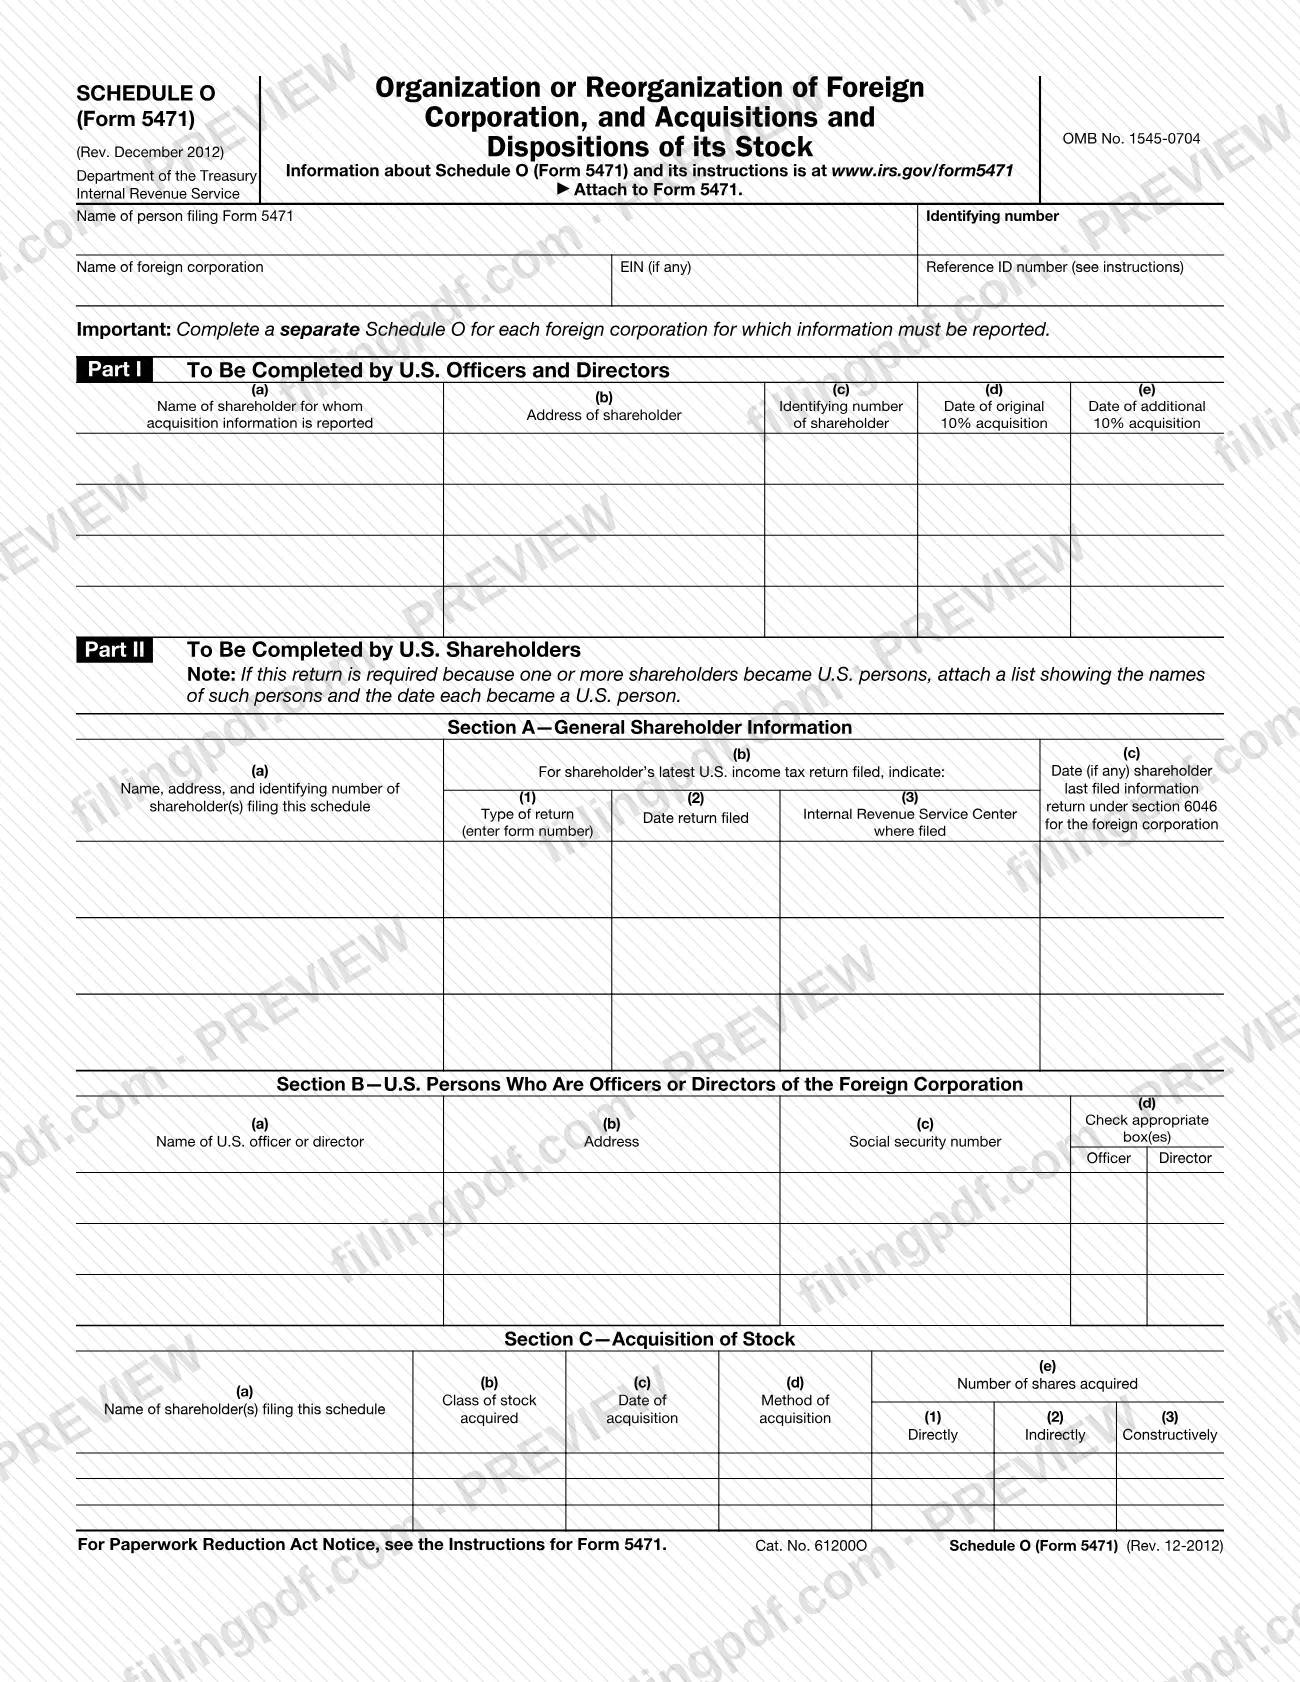
Schedule O (Form 5471), Organization or Reorganization of Foreign Corporation, and Acquisitions and Dispositions of Its Stock, is an Internal Revenue Service (IRS) schedule that you attach to Form 5471. It records who owns 10% of a foreign corporation's stock, how stock was acquired or disposed of, and what was transferred when the corporation was organized or reorganized. U.S. officers and directors complete Part I; U.S. shareholders complete Part II. On this page you can fill out the form online on FillingPDF and download or print the completed PDF; the IRS publishes the form and its instructions at www.irs.gov/form5471.
Last updated
What is Schedule O (Form 5471)?
Schedule O (Form 5471) is the IRS schedule attached to Form 5471 on which U.S. officers, directors and shareholders report the organization or reorganization of a foreign corporation and the acquisitions and dispositions of its stock.
The Internal Revenue Service (IRS) issues it under OMB No. 1545-0704, and the revision printed on the form is Rev. December 2012. It is not a stand-alone return: the form says to attach it to Form 5471, and it asks for the name of the person filing Form 5471, an identifying number, the name of the foreign corporation, its EIN (if any) and a reference ID number (see instructions).
The schedule has two parts. Part I, To Be Completed by U.S. Officers and Directors, lists shareholders with the dates of original and additional 10% acquisitions. Part II, To Be Completed by U.S. Shareholders, has six sections:
- Section A: general shareholder information.
- Section B: U.S. persons who are officers or directors of the foreign corporation.
- Section C: acquisition of stock.
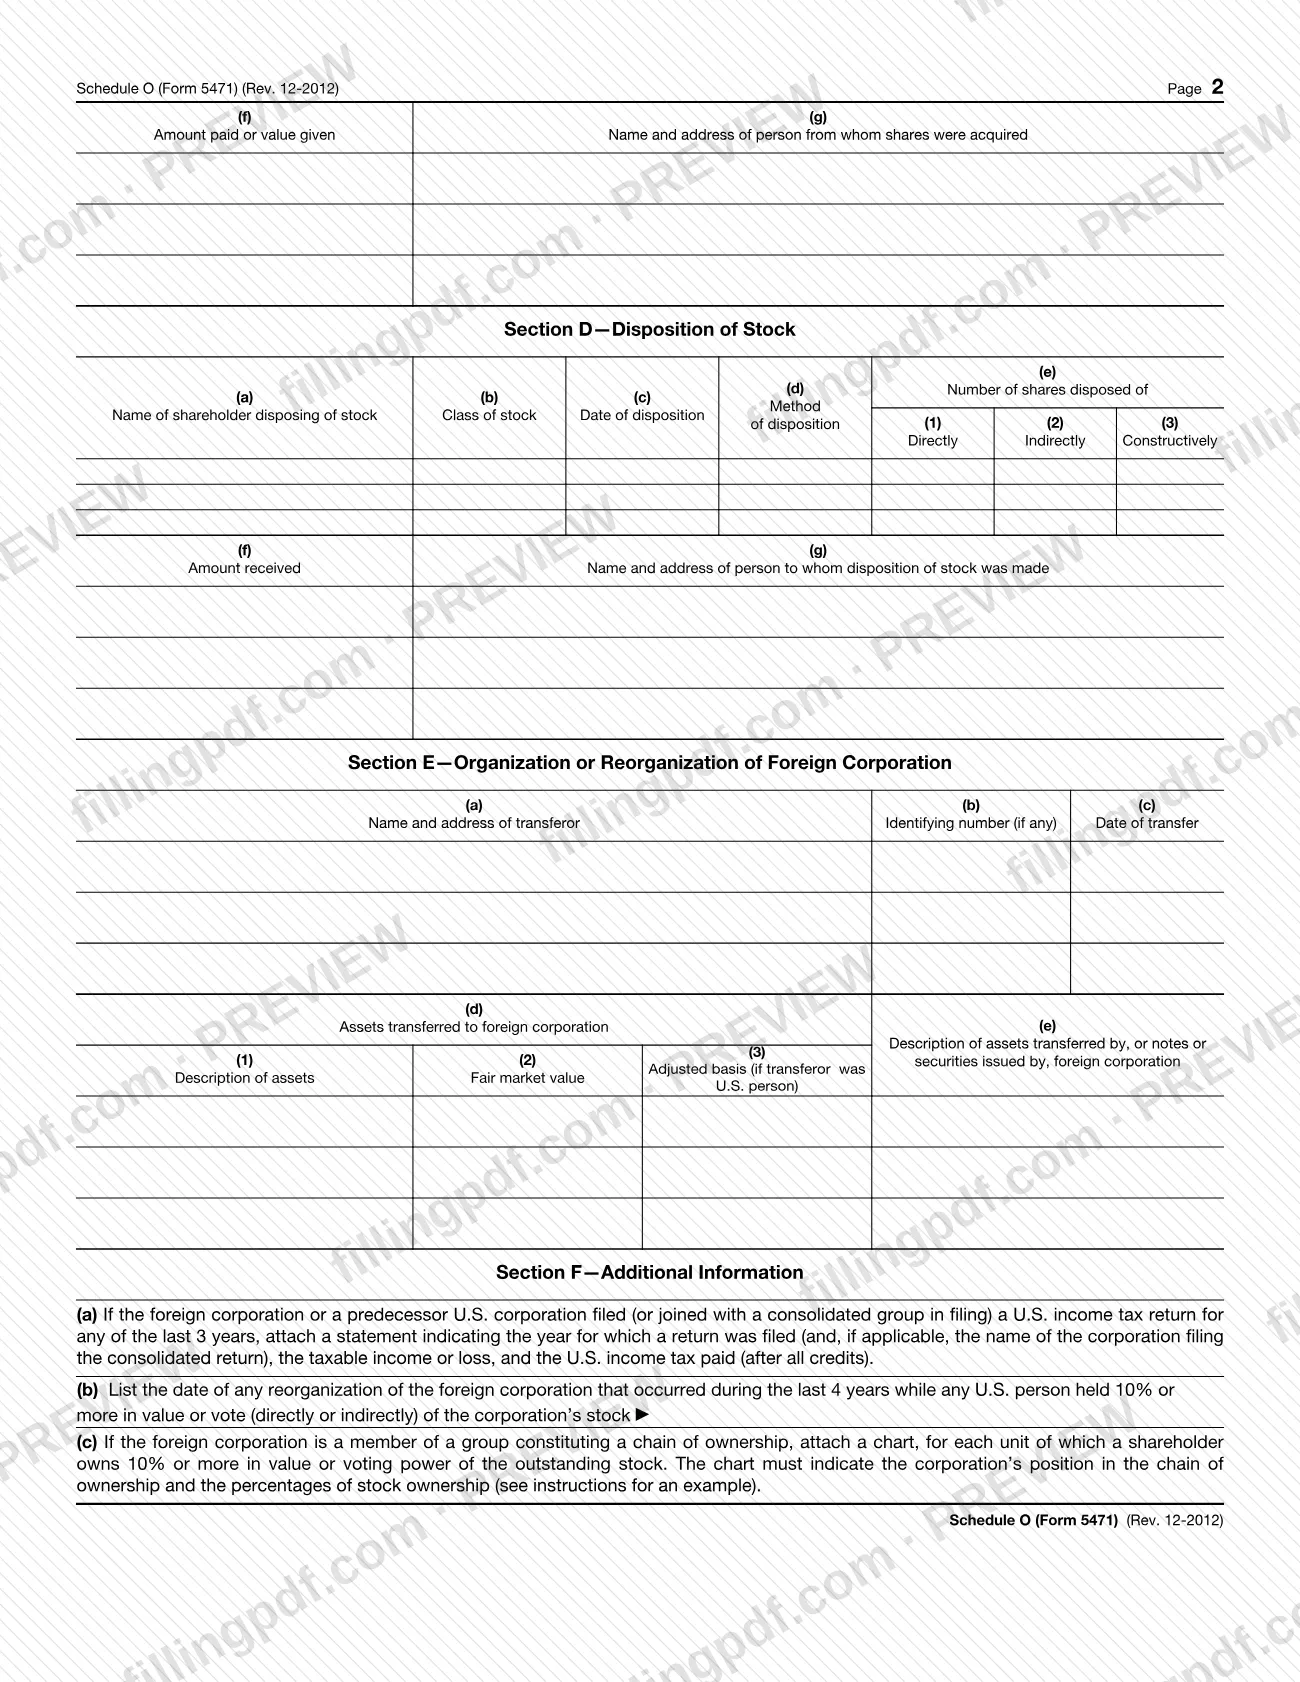
- Section D: disposition of stock.
- Section E: organization or reorganization of the foreign corporation.
- Section F: additional information, with statements and a chart of the ownership chain.
Because "Schedule O" is also the name of other IRS schedules, this page covers only Schedule O of Form 5471. The IRS publishes information about this schedule and its instructions at www.irs.gov/form5471.
Who needs to file Schedule O (Form 5471)?
The schedule is completed by people connected with a foreign corporation whose information is reported on Form 5471. The form splits the work by role:
- U.S. officers and directors complete Part I.
- U.S. shareholders complete Part II. Several shareholders can be listed as the shareholder(s) filing the schedule in Sections A, C and D.
- Section B lists U.S. persons who are officers or directors of the foreign corporation, with a box for Officer or Director.
The person filing Form 5471 is the one named at the top of the schedule. Complete a separate Schedule O for each foreign corporation for which information must be reported.
If Part II is required because one or more shareholders became U.S. persons, the form says to attach a list showing the names of those persons and the date each became a U.S. person.
The schedule is not filed on its own, so it does not apply to anyone who is not filing Form 5471. The form itself does not describe who may sign or file for another person; see the instructions for Form 5471 at www.irs.gov/form5471 for eligibility questions.
When to file Schedule O (Form 5471)
Schedule O (Form 5471) has no separate due date printed on it. The form says to attach it to Form 5471, so it is completed and submitted whenever Form 5471 is filed for the foreign corporation. Check the Instructions for Form 5471 for any deadline that applies to that form.
Some entries depend on dates you should have ready before you start: the dates of original and additional 10% acquisitions (Part I), the date of each stock acquisition or disposition (Sections C and D), the date of each transfer to the corporation (Section E), and any reorganization of the foreign corporation during the last 4 years while a U.S. person held 10% or more in value or vote (Section F, line (b)). Section F, line (a) looks back 3 years for any U.S. income tax return filed by the corporation or a predecessor U.S. corporation.
Documents you need
- A list of names and the date each became a U.S. person, attached only if Schedule O is required because one or more shareholders became U.S. persons (note under Part II).
- A statement for Section F, line (a), if the foreign corporation or a predecessor U.S. corporation filed (or joined a consolidated group in filing) a U.S. income tax return for any of the last 3 years: year filed, corporation filing the consolidated return if applicable, taxable income or loss, and U.S. income tax paid after all credits.
- A chart for Section F, line (c), if the foreign corporation is a member of a group constituting a chain of ownership: one for each unit of which a shareholder owns 10% or more in value or voting power, showing the corporation's position and the stock ownership percentages.
- Form 5471, to which the schedule is attached; a separate Schedule O for each foreign corporation reported.
How to fill out Schedule O (Form 5471)
Enter filer and corporation details
At the top, enter the name of the person filing Form 5471 and the identifying number. Then enter the name of the foreign corporation, its EIN (if any) and the reference ID number (see instructions).
Use one schedule per corporation
Complete a separate Schedule O for each foreign corporation for which information must be reported.
Complete Part I for 10% shareholders
U.S. officers and directors list, for each shareholder for whom information is reported: (a) name, (b) address, (c) identifying number, (d) date of original 10% acquisition and (e) date of additional 10% acquisition.
Complete Part II, Section A
In (a) enter name, address and identifying number of each shareholder filing the schedule. In (b) give the type of return (form number), the date filed and the IRS Service Center for the latest U.S. income tax return. In (c) give the date of the last information return under section 6046, if any.
List officers and directors in Section B
For each U.S. officer or director of the foreign corporation, enter the name (a), address (b) and social security number (c), and check Officer, Director or both in (d).
Report stock acquired in Section C
Enter the shareholder filing (a), class of stock acquired (b), date (c) and method of acquisition (d). Split shares into Directly, Indirectly and Constructively in (e)(1) to (e)(3), then give the amount paid or value given (f) and who the shares were acquired from (g).
Report stock disposed of in Section D
Enter the shareholder disposing (a), class (b), date (c) and method (d). Split shares into the three columns in (e), then give the amount received (f) and the name and address of the person to whom the stock was disposed (g).
Describe transfers in Section E
For each transferor, enter the name and address (a), identifying number if any (b) and date of transfer (c). In (d) give the description of assets, fair market value and, if the transferor was a U.S. person, adjusted basis; (e) describes assets or notes or securities issued by the foreign corporation.
Answer the Section F questions
For (a), attach a statement on any U.S. income tax return filed in the last 3 years. For (b), list the date of any reorganization in the last 4 years while a U.S. person held 10% or more. For (c), attach the ownership chart if the corporation is in a chain of ownership.
Attach the Part II list if required
If the return is required because shareholders became U.S. persons, attach a list with each name and the date that person became a U.S. person.
Review and download the PDF
Check names, identifying numbers, dates and share counts against your records, then download or print the completed PDF from FillingPDF and attach it to Form 5471.
How to submit Schedule O (Form 5471)
Schedule O (Form 5471) has one route: it is submitted as an attachment to Form 5471. The schedule prints no mailing address, portal or appointment rule of its own.
- Attach it to Form 5471. The form says "Attach to Form 5471." Send the schedule the way you submit Form 5471.
- One schedule per foreign corporation. If you report on more than one foreign corporation, prepare a separate Schedule O for each.
- Add the required attachments. Include the list of new U.S. persons (Part II note) and the Section F statement and chart, where they apply.
- Find the filing details. The form points to www.irs.gov/form5471 for information about the schedule and its instructions; the Instructions for Form 5471 govern where and how Form 5471 is filed.
FillingPDF lets you fill out and download the PDF; submission follows the IRS channels that apply to Form 5471.
Common mistakes to avoid
- Filing Schedule O (Form 5471) without attaching it to Form 5471; the form states it is to be attached to Form 5471.
- Combining several foreign corporations on one schedule instead of completing a separate Schedule O for each foreign corporation.
- Completing Part II when only Part I applies, or the reverse; Part I is for U.S. officers and directors and Part II for U.S. shareholders.
- Omitting the list of names and dates each person became a U.S. person when the return is required because shareholders became U.S. persons.
- Leaving out the Section F, line (a) statement of taxable income or loss and U.S. income tax paid when the corporation or a predecessor U.S. corporation filed a U.S. return in the last 3 years.
- Skipping the Section F, line (c) ownership chart when the foreign corporation is part of a chain of ownership in which a shareholder owns 10% or more.
- Not splitting the number of shares among Directly, Indirectly and Constructively in Sections C and D columns (e)(1) to (e)(3).
- Leaving the adjusted basis blank in Section E, column (d)(3), when the transferor was a U.S. person.
Frequently asked questions
What is Schedule O (Form 5471)?
Schedule O (Form 5471) is an IRS schedule attached to Form 5471. It reports the organization or reorganization of a foreign corporation and the acquisitions and dispositions of its stock, with Part I for U.S. officers and directors and Part II for U.S. shareholders.
Is Schedule O filed by itself?
No. The form says to attach it to Form 5471, so it is submitted with that form. It has no mailing address, portal or separate due date of its own; the Instructions for Form 5471 at www.irs.gov/form5471 cover how that form is filed.
Do I need a separate Schedule O for each foreign corporation?
Yes. The form states that you must complete a separate Schedule O for each foreign corporation for which information must be reported. Each schedule carries its own corporation name, EIN (if any) and reference ID number.
Who completes Part I and who completes Part II?
Part I is to be completed by U.S. officers and directors, and Part II by U.S. shareholders. Part II has Sections A to F; Section B lists U.S. persons who are officers or directors of the foreign corporation.
What do I attach to Schedule O (Form 5471)?
Attach only what applies: a list of new U.S. persons with the date each became one, a Section F(a) statement of any U.S. return filed in the last 3 years, and a Section F(c) chart if the corporation is in an ownership chain with a 10% shareholder.
Can I fill out Schedule O (Form 5471) online?
Yes. You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the form with the IRS; you submit it with Form 5471 through the IRS channels.
What is the difference between Directly, Indirectly and Constructively in Sections C and D?
They are three columns, (e)(1), (e)(2) and (e)(3), in which you split the number of shares acquired or disposed of by how the shareholder held or disposed of them. Enter the shares in the column that matches; the Instructions for Form 5471 explain each term.
Where can I find the instructions for Schedule O?
The form says information about Schedule O (Form 5471) and its instructions is at www.irs.gov/form5471, and its Paperwork Reduction Act notice refers to the Instructions for Form 5471.
Ready to fill out Schedule O (Form 5471)?
Fill out Schedule O (Form 5471) now