
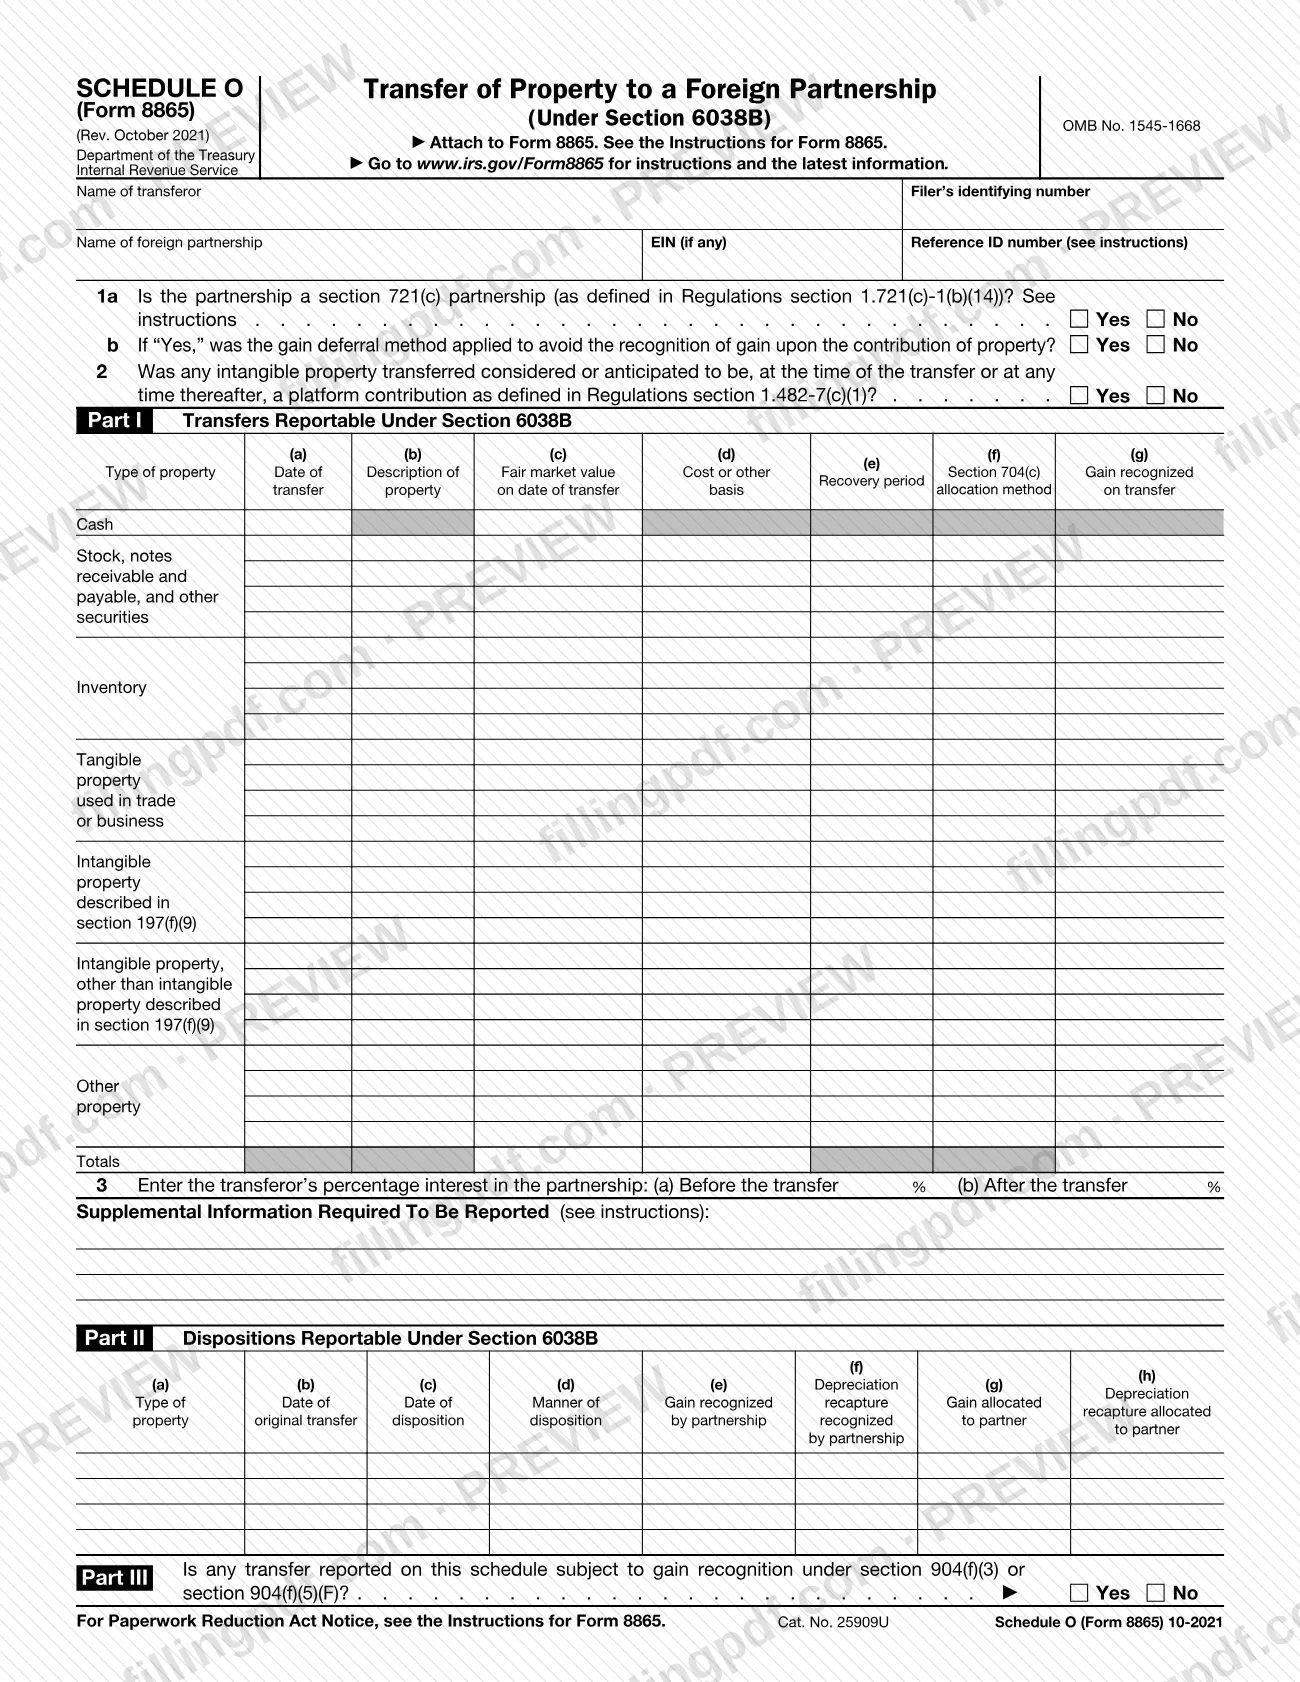
Schedule O (Form 8865), Transfer of Property to a Foreign Partnership (under section 6038B), is an Internal Revenue Service (IRS) schedule that you attach to Form 8865. It reports property a transferor contributes to a foreign partnership, the gain recognized on the transfer, and later dispositions of that property. On this page you can fill out the form online on FillingPDF and download or print the completed PDF. The original form and the Instructions for Form 8865 are published by the IRS at www.irs.gov/Form8865.
Last updated
What is Schedule O (Form 8865)?
Schedule O (Form 8865), Transfer of Property to a Foreign Partnership (under section 6038B), is the IRS schedule attached to Form 8865 that reports property transferred to a foreign partnership, the gain recognized on the transfer, and later dispositions of that property.
The schedule is printed under OMB No. 1545-1668 and carries the revision date Rev. October 2021. It identifies the transferor and the foreign partnership at the top, then asks three kinds of questions: whether the partnership is a section 721(c) partnership and whether the gain deferral method was applied (line 1a and 1b), and whether any intangible property transferred was a platform contribution (line 2).
The body has three parts:
- Part I, Transfers Reportable Under Section 6038B: a table by type of property (cash, stock and other securities, inventory, tangible property, intangible property and other property) with date, description, fair market value, cost or other basis, section 704(c) allocation method and gain recognized, plus line 3 for the transferor's percentage interest before and after the transfer.
- Part II, Dispositions Reportable Under Section 6038B: a table of later dispositions, including gain and depreciation recapture recognized by the partnership and allocated to the partner.
- Part III: a Yes or No question on gain recognition under section 904(f)(3) or section 904(f)(5)(F).
It is a schedule, not a stand-alone return: the form says to attach it to Form 8865 and to see the Instructions for Form 8865.
Who needs to file Schedule O (Form 8865)?
The main group is the transferor named at the top of the form: a person reporting, on Form 8865, a transfer of property to a foreign partnership that is reportable under section 6038B. The schedule is attached to Form 8865, so whoever completes that form for such a transfer completes this schedule with it.
Other situations the form covers:
- Filers reporting a transfer of intangible property that was, or is anticipated to become, a platform contribution under Regulations section 1.482-7(c)(1) answer line 2.
- Filers whose foreign partnership is a section 721(c) partnership, as defined in Regulations section 1.721(c)-1(b)(14), answer line 1a Yes and then line 1b on the gain deferral method.
- Filers reporting a disposition of previously transferred property complete Part II.
The form itself does not list who must file Form 8865 or who may sign for someone else; it points to the Instructions for Form 8865 and to www.irs.gov/Form8865 for that. Check those instructions before relying on this schedule alone.
When to file Schedule O (Form 8865)
The triggering event is the preparation of Form 8865: the schedule says to attach it to that form, so it is completed whenever you complete Form 8865 for a transfer of property to a foreign partnership that is reportable under section 6038B. No separate due date is printed on the schedule; it travels with Form 8865 and is submitted at the same time.
Part I covers the transfer itself, so it relates to the date of transfer you enter for each property type. Part II is used when a disposition of previously transferred property has to be reported, with the date of original transfer and the date of disposition. For any deadline or extension that applies to Form 8865, check the Instructions for Form 8865 at www.irs.gov/Form8865.
How to fill out Schedule O (Form 8865)
Identify the transferor and partnership
At the top, enter the name of transferor and the filer's identifying number, then the name of foreign partnership, its EIN (if any) and the Reference ID number (see instructions).
Answer the section 721(c) questions
On line 1a, check Yes or No for whether the partnership is a section 721(c) partnership as defined in Regulations section 1.721(c)-1(b)(14). If Yes, answer line 1b on whether the gain deferral method was applied to avoid recognizing gain on the contribution.
Answer the platform contribution question
On line 2, check Yes or No for whether any intangible property transferred was, or was anticipated to be, a platform contribution as defined in Regulations section 1.482-7(c)(1).
Complete the Part I property table
In Part I, use the row for each type of property transferred: cash, stock and other securities, inventory, tangible property, the two intangible property rows or other property. For each, enter the date of transfer, description, fair market value on the date of transfer, cost or other basis, section 704(c) allocation method and gain recognized on transfer.
Add the recovery period and totals
Enter the recovery period where the form asks for it, then complete the Totals row for the columns that are totaled.
Enter the percentage interest on line 3
On line 3, enter the transferor's percentage interest in the partnership (a) before the transfer and (b) after the transfer.
Add the supplemental information
Under Supplemental Information Required To Be Reported, enter the information the Instructions for Form 8865 require for your transfer.
Report dispositions in Part II
For each disposition, enter the type of property, date of original transfer, date of disposition and manner of disposition. Then enter the gain recognized by the partnership, the depreciation recapture recognized by the partnership, and the gain and depreciation recapture allocated to the partner.
Answer Part III and download the PDF
Check Yes or No in Part III on gain recognition under section 904(f)(3) or section 904(f)(5)(F). Review every part, then download or print the completed PDF from FillingPDF and attach it to Form 8865.
How to submit Schedule O (Form 8865)
Schedule O (Form 8865) has one submission channel: it goes in with Form 8865. The schedule prints no mailing address, portal or appointment rule of its own.
- Attach it to Form 8865. The form states "Attach to Form 8865." Put the completed schedule behind the form it supports.
- Submit the package the way Form 8865 is submitted. Where and how Form 8865 is filed is set out in the Instructions for Form 8865, which the schedule refers to.
- Find instructions and updates. The form directs you to www.irs.gov/Form8865 for instructions and the latest information.
Before sending, check that the name of transferor, the filer's identifying number and the name of the foreign partnership appear at the top. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Filing Schedule O (Form 8865) without attaching it to Form 8865; the form states it is to be attached to Form 8865.
- Answering line 1b when the answer to line 1a is not Yes; line 1b applies only if you answered "Yes" to line 1a.
- Leaving out the Totals row in Part I after listing the property types.
- Omitting line 3, which asks for the transferor's percentage interest in the partnership both before and after the transfer.
- Skipping the Supplemental Information Required To Be Reported; the form refers to the instructions for what must be included.
- Reporting a later disposition in Part I instead of Part II, which has its own columns for the date of original transfer and the date of disposition.
- Leaving Part III unanswered; it asks Yes or No whether any transfer reported on the schedule is subject to gain recognition under section 904(f)(3) or section 904(f)(5)(F).
- Omitting the name of transferor or the filer's identifying number at the top of the form.
Frequently asked questions
What is Schedule O (Form 8865)?
Schedule O (Form 8865), Transfer of Property to a Foreign Partnership (under section 6038B), is an IRS schedule attached to Form 8865. It reports property transferred to a foreign partnership, the gain recognized, the transferor's percentage interest before and after, and later dispositions.
Is Schedule O filed by itself?
No. The form says to attach it to Form 8865 and to see the Instructions for Form 8865, so it is submitted with that form. It has no separate address, portal or due date printed on it.
What is the difference between Part I and Part II of Schedule O?
Part I reports transfers of property to the foreign partnership under section 6038B, by type of property. Part II reports dispositions under section 6038B, with the date of original transfer, the date of disposition, and the gain and depreciation recapture recognized by the partnership and allocated to the partner.
What do lines 1a and 1b ask about?
Line 1a asks whether the partnership is a section 721(c) partnership as defined in Regulations section 1.721(c)-1(b)(14). If you answer Yes, line 1b asks whether the gain deferral method was applied to avoid recognizing gain on the contribution of property.
Where do I find the instructions for this schedule?
The form refers you to the Instructions for Form 8865 and to www.irs.gov/Form8865 for instructions and the latest information. Those instructions also explain the Reference ID number and the supplemental information the schedule requires.
Can I fill out Schedule O (Form 8865) online?
Yes. You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the schedule with the IRS; you submit it with Form 8865 through the IRS channels that apply to that form.
What does Part III ask?
Part III asks Yes or No whether any transfer reported on the schedule is subject to gain recognition under section 904(f)(3) or section 904(f)(5)(F). It is a single question at the end of the schedule.
Ready to fill out Schedule O (Form 8865)?
Fill out Schedule O (Form 8865) now