
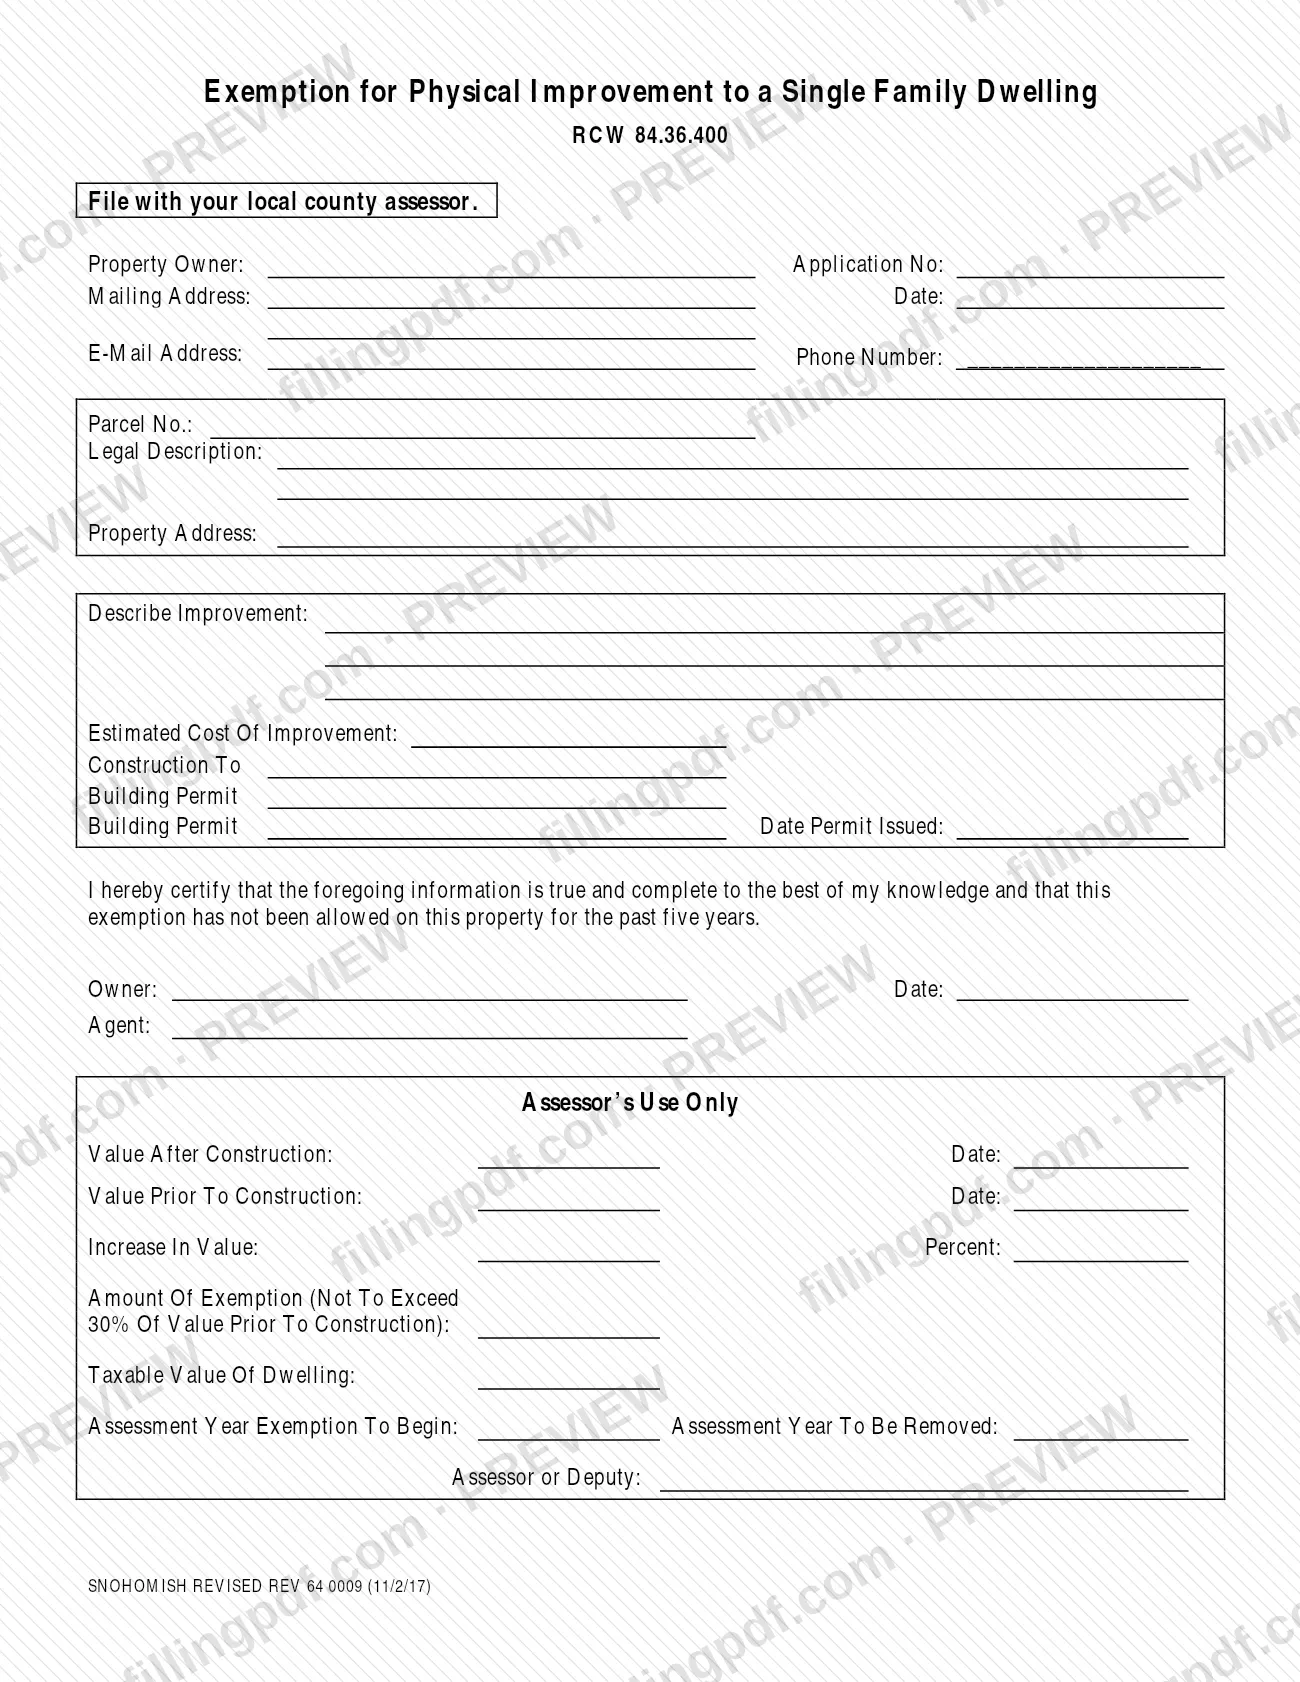
The Thirty Percent Home Improvement Exemption is a Snohomish County application, printed as "Exemption for Physical Improvement to a Single Family Dwelling" under RCW 84.36.400, that asks the county assessor to exempt a physical improvement to an existing single family dwelling from property tax. It is one of the Snohomish County property tax exemptions handled by the county's Exemption Division, and the claim must be filed before the improvement is completed. On FillingPDF you can fill out the form online and download or print the completed PDF; the county publishes the original at snohomishcountywa.gov.
Last updated
What is REV 64 0009?
The Thirty Percent Home Improvement Exemption is Snohomish County's application, titled "Exemption for Physical Improvement to a Single Family Dwelling" (RCW 84.36.400), for a property tax exemption on a physical improvement to an existing single family dwelling.
The form is filed with the county assessor. It collects the owner's details, the parcel number, legal description and property address, a description of the improvement, the estimated cost, the construction and building permit information, and a certification signed by the owner or an agent. The "Assessor's Use Only" block is completed by the assessor's office.
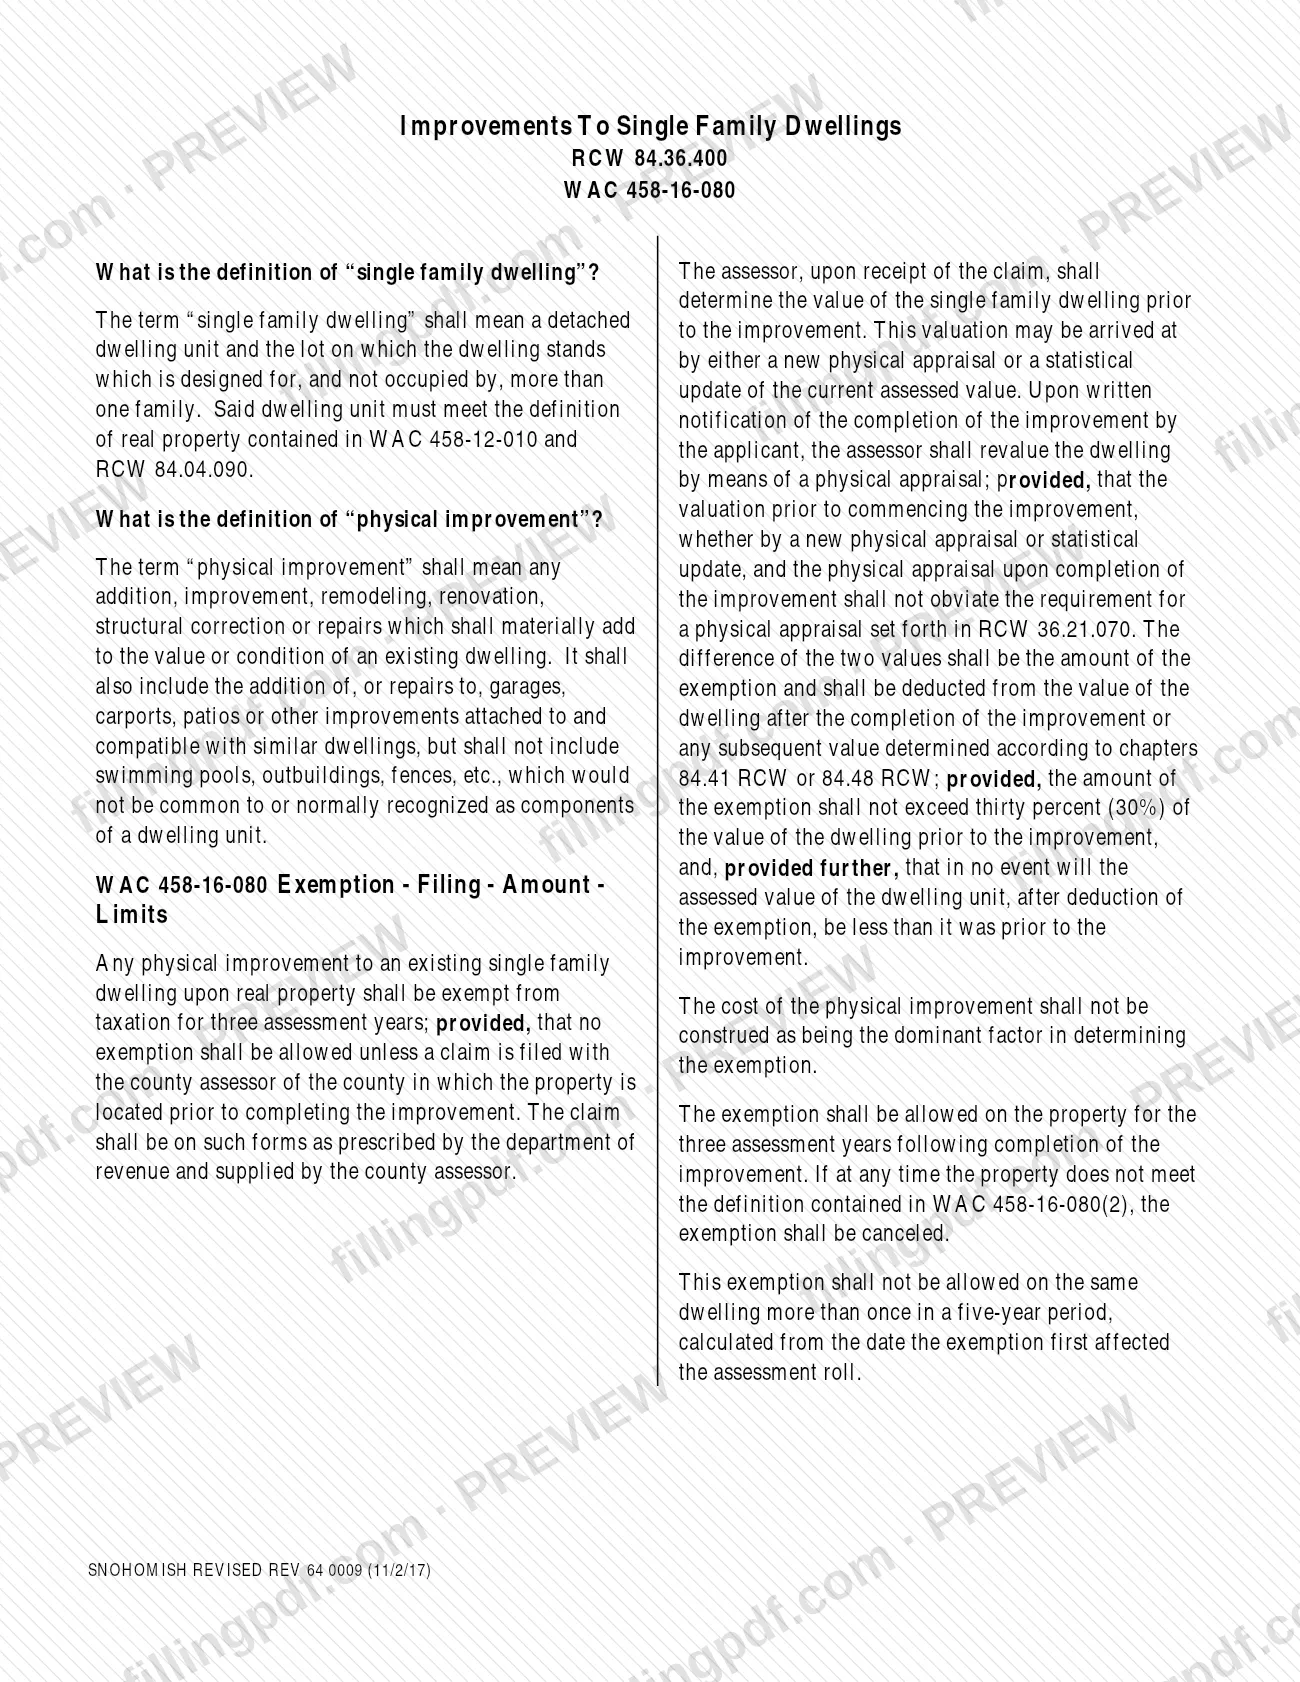
The rules behind the form are printed on its second page (RCW 84.36.400 and WAC 458-16-080). The assessor determines the value of the dwelling before the improvement, by a new physical appraisal or a statistical update. When the applicant gives written notice that the improvement is complete, the assessor revalues the dwelling by physical appraisal. The difference between the two values is the amount of the exemption, deducted from the value after completion. The exemption cannot exceed thirty percent (30%) of the value before the improvement, and the assessed value after the deduction can never be lower than it was before the improvement. The cost of the work is not the dominant factor.
The exemption is allowed for the three assessment years following completion. If the property stops meeting the definition in WAC 458-16-080(2), the exemption is canceled. The form is not a senior citizen or disability exemption: the county's Exemption Division lists those as separate programs.
Who needs to file REV 64 0009?
Owners of an existing single family dwelling who plan a physical improvement to it and want the exemption claim this on the form. An agent may sign for the owner: the certification has a line for the owner and a line for an agent.
The instructions define the terms:
- Single family dwelling: a detached dwelling unit and the lot it stands on, designed for, and not occupied by, more than one family. It must meet the definition of real property in WAC 458-12-010 and RCW 84.04.090.
- Physical improvement: any addition, improvement, remodeling, renovation, structural correction or repair that materially adds to the value or condition of an existing dwelling. It includes adding or repairing garages, carports, patios or other improvements attached to and compatible with similar dwellings.
The instructions exclude swimming pools, outbuildings, fences and similar items not normally recognized as components of a dwelling unit.
Do not use the form if the exemption has already been allowed on the same dwelling within five years. The exemption is not allowed more than once in a five-year period, counted from the date it first affected the assessment roll, and the owner certifies on the form that it has not been allowed on the property in the past five years.
When to file REV 64 0009
File the claim before you complete the improvement. WAC 458-16-080, printed with the form, says no exemption is allowed unless the claim is filed with the county assessor before the improvement is completed.
Once the work is finished, give the assessor written notification of completion. The assessor then revalues the dwelling by physical appraisal, and the exemption is allowed for the three assessment years following completion. The form has a line for the assessment year the exemption begins and one for the year it is removed; the assessor's office completes both.
Plan around the five-year rule as well. The exemption cannot be allowed on the same dwelling more than once in a five-year period, counted from the date it first affected the assessment roll. The form sets no other deadline and prints no processing time.
How to fill out REV 64 0009
Enter owner and contact details
Fill in the Property Owner, Mailing Address, E-Mail Address and Phone Number lines, and the Date. Application No. is in the same heading block; ask the Exemption Division if you are unsure who completes it.
Identify the property
Enter the Parcel No., the Legal Description and the Property Address of the single family dwelling.
Describe the improvement
On the Describe Improvement line, state the addition, remodeling, renovation, structural correction or repair. Do not list swimming pools, outbuildings or fences, which the instructions exclude.
Enter the estimated cost
Write the Estimated Cost Of Improvement. The cost is only information for the assessor; the instructions say it is not the dominant factor in setting the exemption.
Give construction and permit details
Complete the Construction To line and the Building Permit lines, including the date the permit was issued, as the form asks.
Read the certification
The certification says the information is true and complete and that this exemption has not been allowed on the property in the past five years. Confirm both statements before signing.
Sign and date the form
The owner signs and dates on the Owner line. An agent signing for the owner uses the Agent line.
Leave the assessor's block blank
The Assessor's Use Only section holds the values before and after construction, the amount of the exemption and the assessment years. The assessor or deputy completes it.
Review and download the completed PDF
Check names, parcel number and dates, then download or print the completed PDF from FillingPDF and file it with the county assessor as described under How to submit.
How to submit REV 64 0009
The form names one destination: it says to file it with your local county assessor. For Snohomish County, the Exemption Division administers the county's property tax exemption programs.
- Exemption Division contact: phone 425-388-3540, fax 425-388-3615, at 3000 Rockefeller Ave. M/S 510, Everett, WA 98201-4046. The division is in the Customer Service Center of the Administration East building of the county campus.
- Timing: the claim must be filed before the improvement is completed.
- Completion notice: after the work is done, you give the assessor written notification of completion so the dwelling can be revalued.
The form itself does not list mailing, fax, portal or walk-in rules, so call the Exemption Division to confirm how it accepts the signed form. No filing fee or attachment is printed on the form. FillingPDF lets you fill out and download the PDF; submission follows the county's channels above.
Common mistakes to avoid
- Filing the claim after the improvement is already completed; the rules printed with the form say no exemption is allowed unless the claim is filed before completion.
- Claiming the exemption on a dwelling that already received it within the past five years, which the owner's certification on the form rules out.
- Listing a swimming pool, outbuilding or fence as the improvement; the instructions exclude items not normally components of a dwelling unit.
- Using the form for a building that is not a detached dwelling unit designed for, and occupied by, no more than one family.
- Leaving the building permit and permit date lines blank when a permit was issued for the work.
- Assuming a higher project cost means a higher exemption; the cost is not the dominant factor, and the amount cannot exceed 30% of the value before construction.
- Filling in the Assessor's Use Only block, which the assessor's office completes.
- Not giving the assessor written notice when the work is complete, which the assessor needs to revalue the dwelling.
Frequently asked questions
What is the Thirty Percent Home Improvement Exemption?
It is Snohomish County's application for a property tax exemption on a physical improvement to an existing single family dwelling, based on RCW 84.36.400. The exemption amount is capped at 30% of the dwelling's value before the improvement.
Do I have to file before I finish the work?
Yes. WAC 458-16-080, printed with the form, says no exemption is allowed unless the claim is filed with the county assessor before the improvement is completed. After completion, you give the assessor written notification so the dwelling can be revalued.
How long does the home improvement exemption last?
The exemption is allowed for the three assessment years following completion of the improvement. It is canceled if the property stops meeting the single family dwelling definition in WAC 458-16-080(2).
How much is the exemption?
It is the difference between the dwelling's value before the improvement and its value after completion, capped at 30% of the value before. The assessed value after the deduction cannot be lower than it was before the improvement.
What counts as a physical improvement?
Any addition, improvement, remodeling, renovation, structural correction or repair that materially adds to the value or condition of an existing dwelling, including attached garages, carports and patios. Swimming pools, outbuildings and fences are excluded.
Can I claim the exemption more than once?
Not on the same dwelling within a five-year period, counted from the date the exemption first affected the assessment roll. The form's certification states the exemption has not been allowed on the property in the past five years.
Does a higher project cost increase the exemption?
No. The instructions say the cost of the improvement is not the dominant factor. The assessor sets the amount from the before-and-after values, up to 30% of the value before construction.
Where do I file the form?
The form says to file it with your local county assessor. In Snohomish County, the Exemption Division handles exemptions: call 425-388-3540 or write to 3000 Rockefeller Ave. M/S 510, Everett, WA 98201-4046 to confirm how it accepts the signed form.
Can I fill out this form online on FillingPDF?
Yes. You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the form with Snohomish County; you submit it through the county's channels.
Ready to fill out REV 64 0009?
Fill out REV 64 0009 now